
Disc Medicine (IRON) Reports Encouraging RESTORE PV Data, Is The Stock Undervalued?
Disc Medicine (IRON) is back in focus after new Phase 2 RESTORE-PV data on its antibody DISC-3405 in polycythemia vera reported controlled hematocrit, fewer phlebotomies, and improved patient-reported symptoms.
Despite the positive RESTORE-PV update, Disc Medicine’s share price has slipped over recent weeks. The 7-day share price return is down 10.38% and the 30-day share price return is down 14.34%, while the 1-year total shareholder return of 12.35% suggests longer term holders have still seen gains, even as recent momentum has faded.
Capitalize on the renewed interest in Disc Medicine and compare it with other hematology focused biotechs by scanning our hand picked 16 high quality undiscovered gems now.Disc Medicine now trades at US$68.57 while analyst targets and intrinsic value estimates sit much higher. Are investors looking at a temporary pullback, or is there a deeper mismatch between price and fair value?
DCF suggests Disc Medicine could be materially undervalued
The SWS DCF model estimates a future cash flow value for Disc Medicine of $228.43 per share compared with the recent $68.57 trading price, which points to a wide valuation gap.
This framework projects the company’s expected future cash flows and then discounts them back to today using a required return, so you get a single present value number instead of a loose range of opinions. It treats the stock as a claim on all those future cash streams rather than just next quarter’s headlines.
For a clinical stage biotech like Disc Medicine, with minimal current revenue and a forecast revenue growth rate of 67.1% per year, this kind of model puts more weight on long dated potential than near term losses. That also means small changes in assumptions around future success rates or timing can move the fair value materially. This helps explain why the model value can sit far above or below the latest share price for long periods.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF fair value of $228.43 (UNDERVALUED)
Still, the story around Disc Medicine can change quickly if clinical timelines slip or if ongoing trials fail to support the current valuation gap.
Find out about the key risks to this Disc Medicine narrative.
Price ratios send a more cautious signal
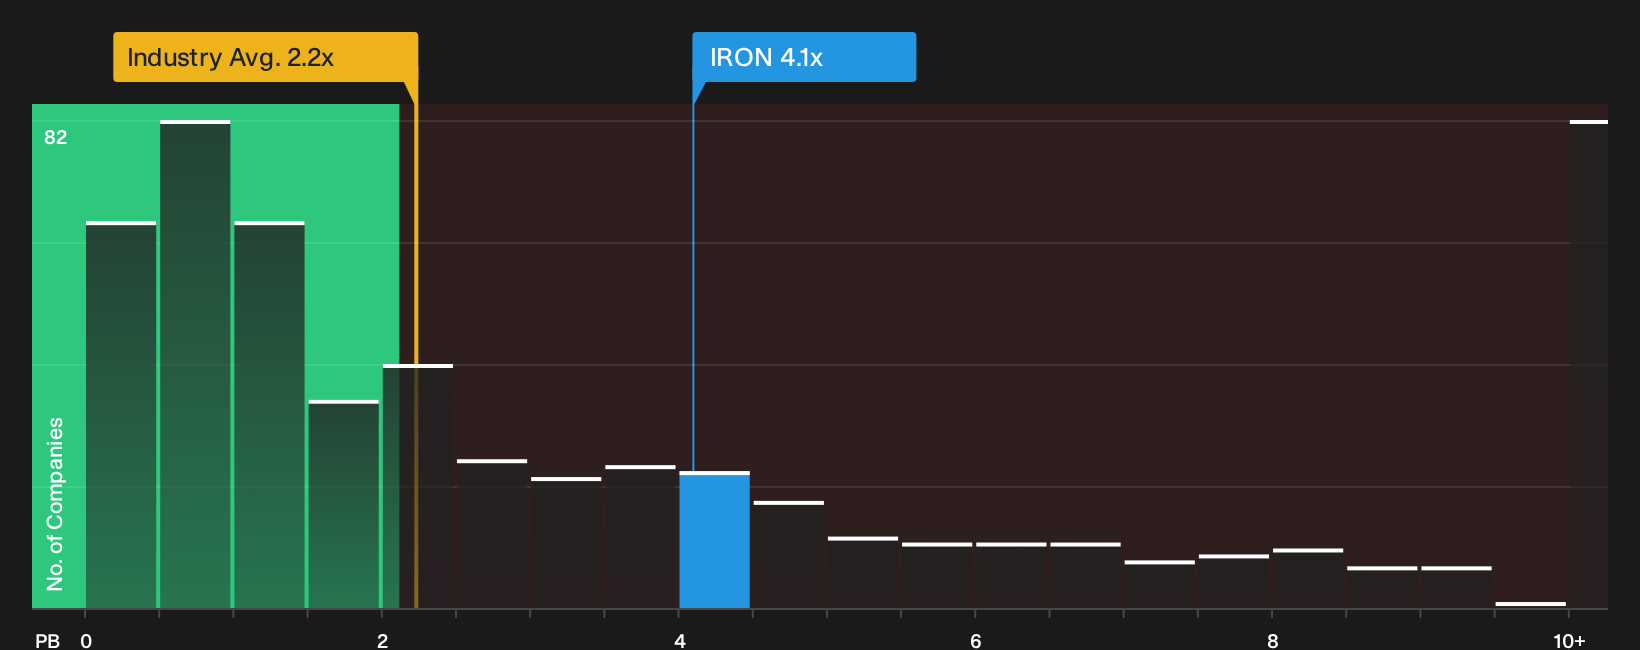
On simple price ratios, Disc Medicine looks less clear cut. The stock trades at a P/B of 4.1x, which is richer than the US Biotechs group at 2.2x, yet below its closer peer average of 7.7x. That mix suggests some optimism is already baked in, even if peers trade on loftier multiples.
For investors, this means the upside hinted at by other models could come with meaningful valuation risk if sentiment cools or trial news disappoints. The fair ratio, which reflects where the P/B could move toward over time, becomes important context. Is the current premium justified by the pipeline and balance sheet, or is it leaning too hard on future success?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Disc Medicine for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Disc Medicine is mixed, with both clear concerns and meaningful upside signals on the table, so move quickly and test the numbers for yourself. To weigh those trade offs directly, start by reviewing the 3 key rewards and 2 important warning signs
Looking for more Disc Medicine style ideas?
Do not stop your research with Disc Medicine. Broaden your opportunity set now using focused stock lists that highlight different strengths and risk profiles.
- Target potential mispricing by scanning our curated pool of undervalued opportunities through the 33 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by zeroing in on companies from the 11 resilient stocks with low risk scores.
- Strengthen your foundation with businesses backed by healthier finances using the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com