
What Could the Fallout Be to the Fed's Rate Hike?
The FOMC voted 12-0 in favor of a 25-basis point rate hike, sending US stock markets lower Wednesday afternoon.
As expected, the US president's feathers were ruffled as he wants interest rates at 0%, so he turned his anger on Canada and the EU overnight through early Thursday morning.
The Grains sector was mostly higher to start the day, albeit quietly, as rains continue to move across the US Midwest.
Morning Summary: A couple things went through my mind while watching Fed Chairman Warsh announce a 25-basis point rate hike Wednesday afternoon. What stood out to me was the vote went 12-0 in favor of the first hike in three years, despite the dictate from on high that rates come down. And while this agreed with what most in the industry were saying ahead of the announcement, it did not fit with what the Fed fund futures forward curve had been showing since the end of the July meeting. Recall the curve indicated the first cut would be in October, another in December, with no meeting in November. I wondered what I missed, so I looked at the charts again and still saw the same thing. The second thing that came to mind was the US president’s feathers were ruffled by his puppet not doing what he was told. There were two possible outcomes Wednesday afternoon through Thursday morning: 1) The US president would say the only line he is known for, “You’re fired”, to Mr. Warsh or 2) the US president would take out his anger by needlessly increasing the bombing on Iran or attack some other country. As it looks Thursday morning, the latter seems to have played out as he vents his ire at Canada for seeking a stronger trade alliance with the EU.
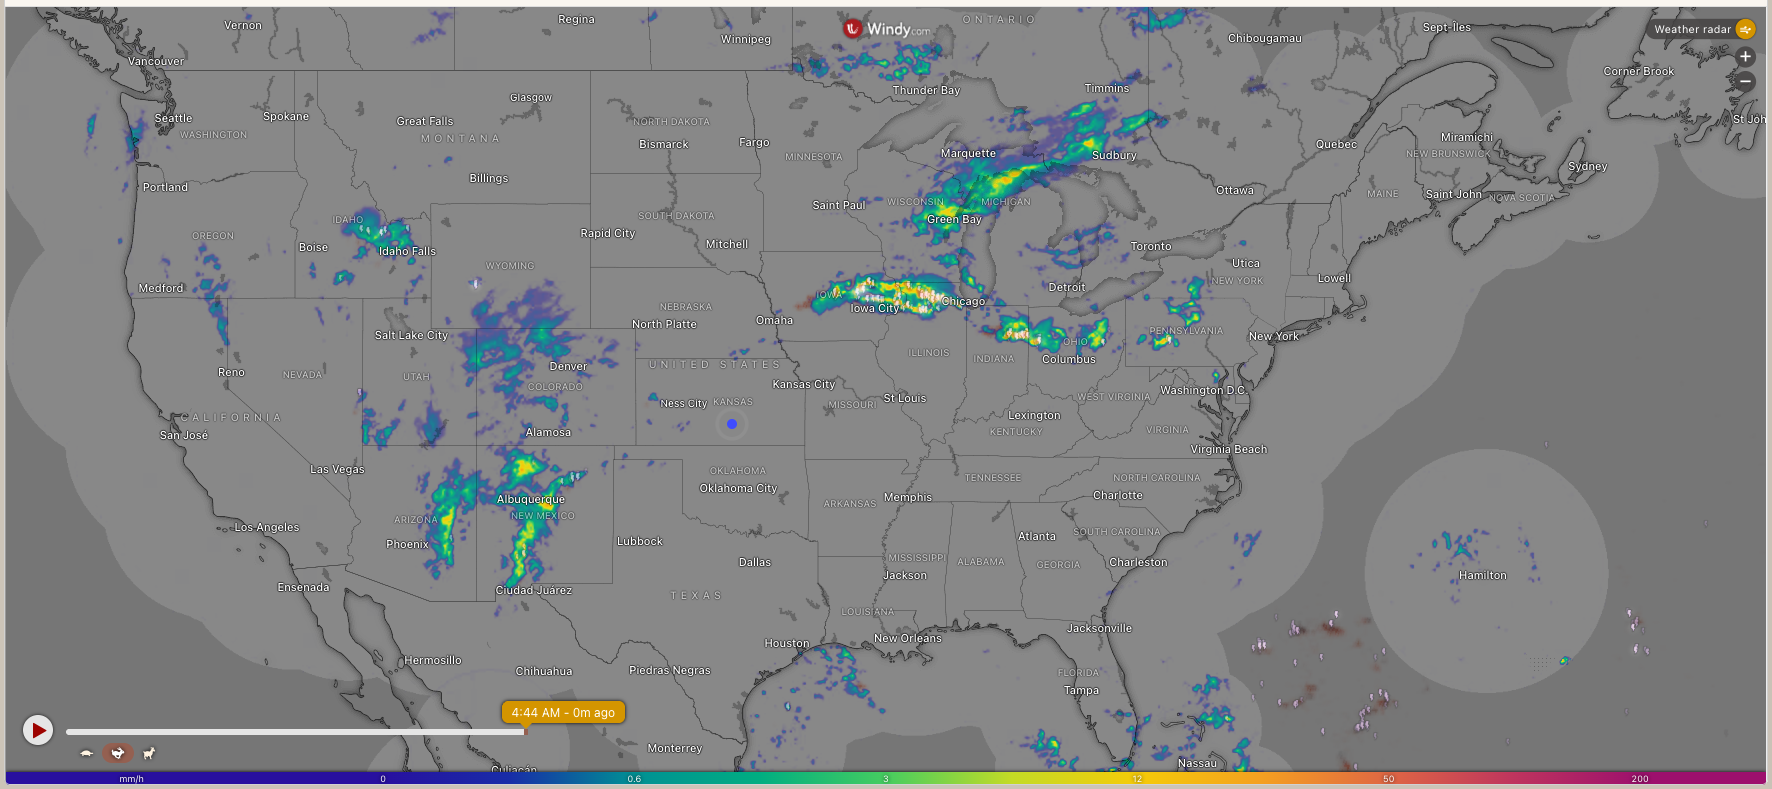
Corn: It was more of more of the same in the corn market pre-dawn Thursday with contracts sitting quietly in the green. After sitting higher Wednesday morning as well, also on low trade volume, the December issue (ZCZ26) finished yesterday’s session 1.5 cents in the red while the Dec-March futures spread was unchanged at a carry of 14.5 cents. In other words, not much happened. Fast forward to this morning and we see Dec posted a 5.5-cent overnight trading range, from down 3.0 cents to up 2.5 cents while registering fewer than 20,000 contracts changing hands and was sitting 1.25 cents in the green as of this writing. While I still think the December issue could see harvest pressure over the coming weeks, continued rains across the US Midwest could push this back a bit. Thursday’s radar shows the system now over eastern Iowa, slowly making its way eastward. Later this morning we will get weekly updates of the US Drought Monitor map, through Tuesday, September 15, and export sales and shipments through Thursday, September 10. From a technical point of view, Dec continues to consolidate within last week’s range, but let’s see how the rest of the week plays out.
Soybeans: The oilseed sub-sector was mostly higher early Thursday morning, once again led by soybean meal. Here we see the December contract up $6.20 and only $0.50 off its overnight high on decent trade volume of 20,000 contracts. And while futures spreads hint at possible commercial buying, we’ll see if this holds true as the rest of the day plays out. What about soybean oil? Well, the December issue was down 0.6 cent after falling as much as 0.94 cent. Why? The US president also said the other thing he is known for, his war with Iran “hopefully” nearing its end. One has to wonder exactly how stupid ANY entity, including algorithms, are to continue to react to these obvious untruths. But it is what it is, and what it is has diesel fuel down 16.0 cents to start the day. As for soybeans, the November issue (ZSX26) was up 5.25 cents after posting a 16.0-cent trading range overnight, from down 4.75 cents to up 11.25 cents on trade volume of less than 20,000 contracts. (Yes, Dec bean meal showed more activity than Nov soybeans as of this writing.) The November issue bounced late Wednesday to finish 1.75 cents higher for the day.
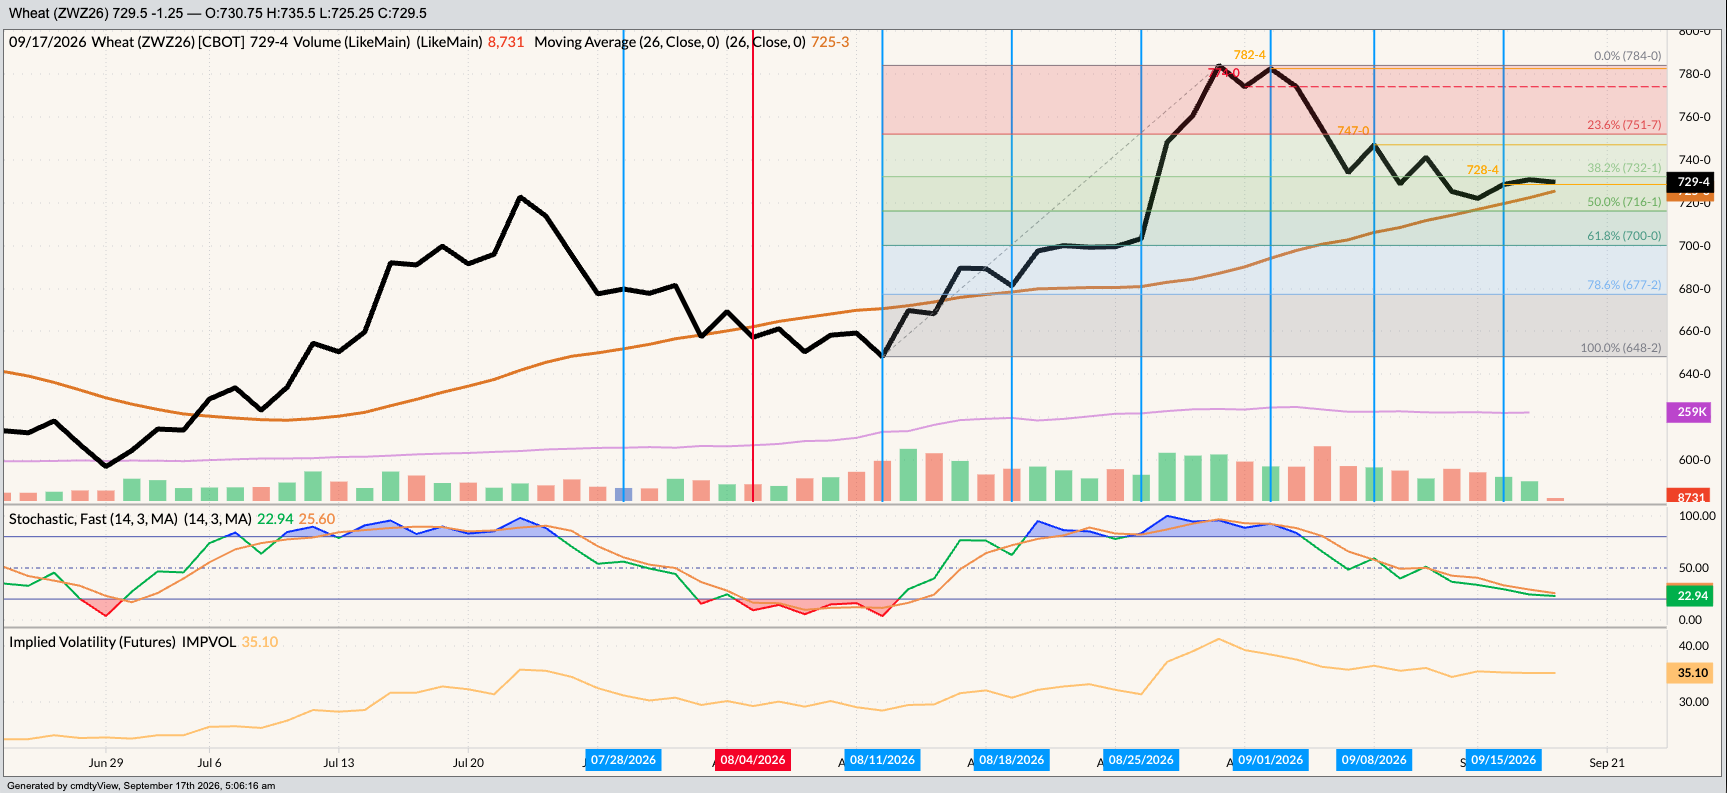
Wheat: The wheat sub-sector was mixed pre-dawn with HRW and HRS in the green while SRW was back in the red. Regarding the latter, the December issue (ZWZ26) was down 1.25 cents at this writing after posting a 10.25-cent trading range from up 4.75 cents to down 5.5 cents, all on trade volume of fewer than 9,000 contracts. While not much has changed fundamentally with the Dec-March futures spread continuing to cover a bearish-leaning 67% calculated full commercial carry, the technical view is quietly getting more interesting. Recall earlier this week the December SRW (and HRW) issue was flirting with a close below its 26-day moving average, what would’ve been the first since mid-August. However, after dipping below this technical statistic during the session, buying from algorithms kicked in caused some separation. Since then, though the two prices have slowly been converging again. Early Thursday morning finds the Dec contract priced near $7.2950 with the 26-day calculated at roughly $7.2525. It’s a similar story in HRW. Here, though, we see the December issue up 1.5 cents and priced at $8.01 as compared to its 26-day moving average near $7.95. Fundamentally, HRW remains neutral with the Dec-March spread covering 48%.
On the date of publication, Darin Newsom did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.