
Restar (TSE:3156) After AI Demand Fueled Earnings, Does The Valuation Still Fit
Restar (TSE:3156) has drawn fresh attention after its shares most recently closed at ¥5,690, leaving investors weighing how the current valuation lines up with the company’s earnings profile and recent business performance.
Recent trading has been strong, with a 1-month share price return of 16.84% and a 90-day gain of 29.02% building on a year-to-date share price return of 102.64%. The 1-year total shareholder return of 121.03% shows how momentum in Restar has extended beyond short-term moves.
Scan beyond Restar and see how other semiconductor and electronics players with strong momentum stack up using our hand picked 17 high quality undervalued stocks as a starting point.
After a run like Restar’s, some investors lean into the momentum, while others wait for the next pullback. At ¥5,690, does the current price already reflect the story, or not yet?
Most Popular Narrative: 120% Overvalued
Restar’s most followed narrative pegs fair value around ¥2,588 per share, which sits well below the recent ¥5,690 close and frames the current rally as rich against that benchmark.
Trend to remain positive. Registering OP growth of 487% YoY, Q1 FY3/27 results were significantly ahead of expectations, with Restar strongly positioned to benefit from AI-driven data center investment demand and rising prices for key products. Taking these factors into account, the company has revised FY guidance and DPS upward. We believe the earnings outlook remains strong, with continued high order visibility, rather than scenarios where demand is driven by a temporary supply shock or customer pre-buying. We have raised our earnings estimates for FY3/27 and beyond.
See why 1 investors see Restar as 120% overvalued.
Result: Fair Value of ¥2,587.96 (OVERVALUED)
Still, this upbeat Restar narrative could be challenged if AI data center demand cools faster than expected, or if M&A and new business units underdeliver.
Find out about the key risks to this Restar narrative.
Another View On Restar’s Valuation
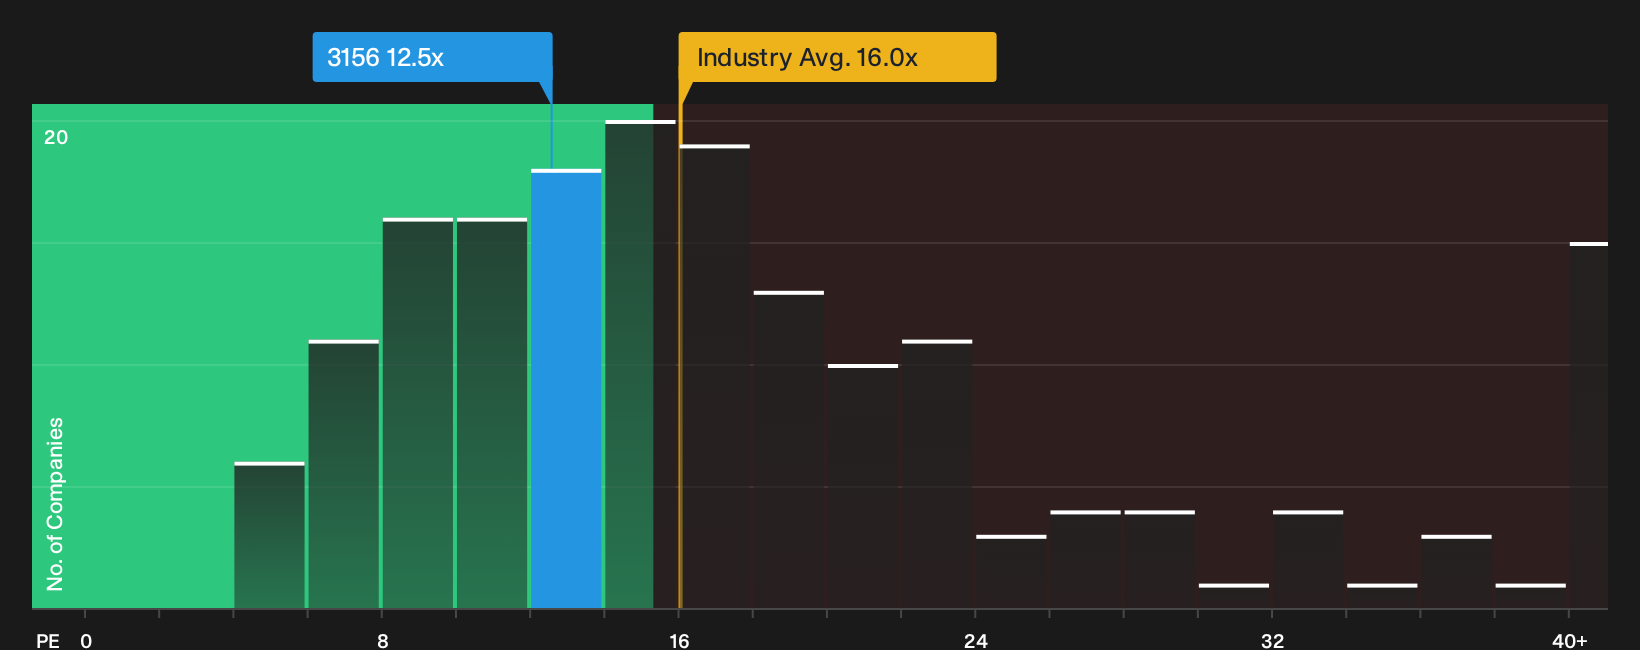
The first narrative paints Restar as roughly 120% overvalued at ¥5,690, using an implied fair value of about ¥2,588 per share. A different lens tells a very different story. On a P/E of 12.5x, Restar trades below the JP Electronic sector at 16x, the peer group at 12.9x, and even the 16.5x fair ratio that the market could move toward over time.
If earnings hold anywhere near current forecasts, that gap can either close through price, through profit shifts, or both. Which adjustment do you think is more realistic?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Restar story so far feels split between excitement and caution, use that tension as a prompt to check the underlying numbers yourself. To see both sides of the ledger in one place, start with our breakdown of 4 key rewards and 3 important warning signs
Ready For More Ideas Beyond Restar?
If Restar has sharpened your thinking on price and quality, do not stop here. Broadening your watchlist now can help you spot opportunities others overlook.
- Target sturdier compounding by scanning companies that combine earnings strength with healthy finances using our list of solid balance sheet and fundamentals (20 results).
- Hunt for potential mispricings by checking businesses that pair quality fundamentals with attractive entry prices through the 17 high quality undervalued stocks.
- Focus on cash returns by reviewing stocks aiming to deliver meaningful income through the 15 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com