
How Higher Rosebery Sales Caps Will Impact MMG Stock Investors
- MMG Limited reported that its Rosebery Mine is now forecast to produce about 6,600 dry metric tonnes of concentrate per year in 2026 and 2027, prompting directors to approve higher annual caps of US$225 million under the existing sales deal with Minmetals North-Europe.
- The unchanged treatment and refining charges, alongside higher forecast production and stronger copper, gold and silver reference prices, suggest MMG is leaning more heavily on Rosebery to support concentrate offtake volumes within its broader copper focused portfolio.
- We will look at how MMG’s investment narrative is affected by the higher Rosebery production forecast and the increased Rosebery sales caps.
MMG Investment Narrative Recap
To hold MMG, you need to believe the copper focused portfolio can keep delivering volume and cost discipline while handling country and project risk. The Rosebery update fits that picture. Higher forecast concentrate volumes and US$225 million annual caps in 2026 and 2027 help underpin near term offtake and revenue visibility from a relatively small but reliable asset.
The key near term swing factor still sits with operational consistency at Las Bambas and execution across Kinsevere and Khoemacau. That remains the biggest risk, given project complexity and jurisdiction exposure. Rosebery’s higher production outlook looks helpful, but not large enough to change the overall risk profile on its own.
The Rosebery Concentrate Sales Agreement revision is the most relevant recent announcement here. Management kept treatment and refining charges unchanged while lifting the annual caps from US$150 million to US$225 million for 2026 and 2027. That points to an operating setup in which improved throughput and recoveries in Tasmania are being locked into an existing offtake channel.
For you, the interest is in how this supports MMG’s broader copper strategy. A fully contracted 100% of Rosebery production at higher forecast volumes may smooth cash flow from that segment and add some cushion around group earnings. Las Bambas disruptions, power reliability at Kinsevere and capital execution across the portfolio still shape the main catalysts and risks.
MMG's narrative points to forecast revenue of $8.8b and projected earnings of $1.7b by 2029, based on analyst assumptions of 12.1% yearly revenue growth and an earnings step up of about $1.2b from $509.4m today.
Uncover how MMG's fair value indicates a 38% potential upside to its current price before wider copper investors close that discount.
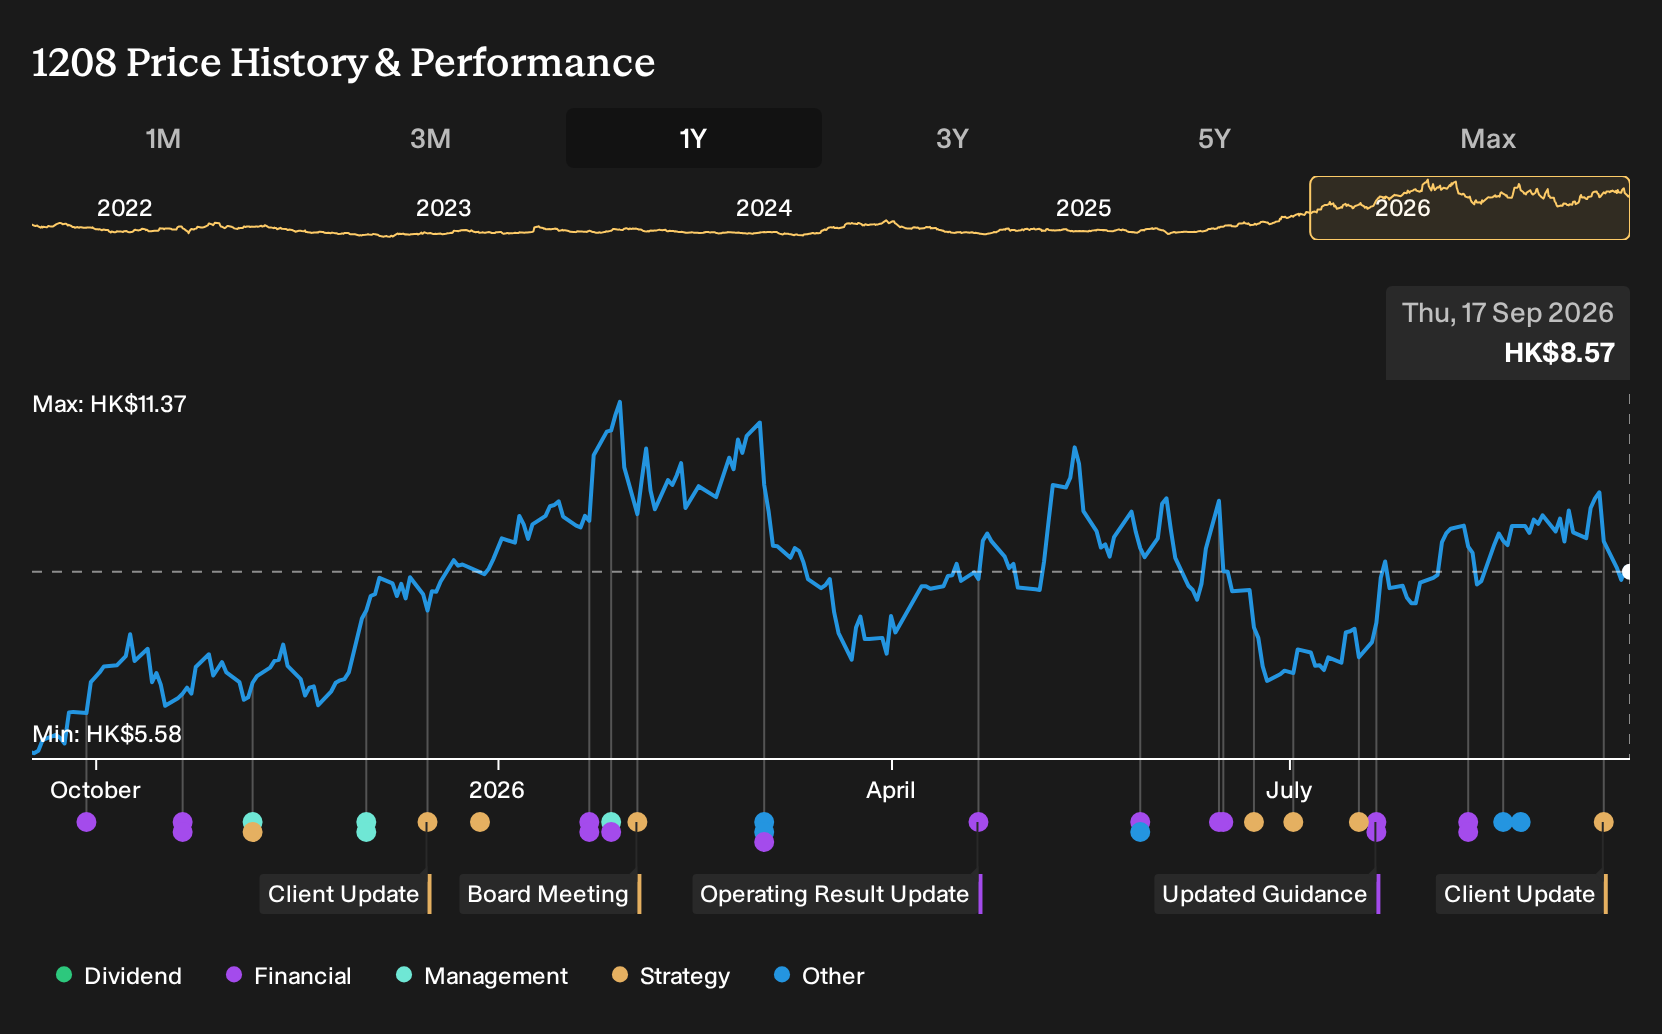
Exploring Other Perspectives
One optimistic twist in the alternate MMG story is Khoemacau. The most bullish analysts were already pencilling in earnings around $2.6b on roughly $10.3b of revenue by 2029, assuming stronger copper output and wider margins. Those views were set before this Rosebery sales cap news, so you may see forecasts shift as opinions update.
Explore another MMG fair value estimate, including one that suggests as much as 111% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MMG research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for MMG. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MMG's overall financial health at a glance.
Looking For More Ideas Beyond MMG?
Once you have a working view on MMG, it can help to compare that thesis with other companies that share similar qualities or offer something very different. The Simply Wall St Screener gives you a fast way to line up those options side by side and pressure test where MMG really fits in your broader watchlist.
- If you care most about strong balance sheets and underlying financial strength, check out our list of solid balance sheet and fundamentals (194 results) that can help you focus on resilience first.
- For investors hunting for mispriced opportunities, use the 184 high quality undervalued stocks to zero in on companies where fundamentals and price are out of sync.
- If you prefer early stage potential with higher risk, scan through our 143 elite penny stocks with strong financials and see which smaller stocks line up with your own criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com