
Should Expanded HIV Access Require Action From Gilead (GILD) Investors?
- Gilead Sciences broadened royalty-free licensing for lenacapavir to cover 120 high-incidence countries and signed a separate agreement with the Pan American Health Organization to expand twice-yearly HIV prevention access across Latin America and the Caribbean.
- The push to align voluntary licenses, technology transfer and regional procurement channels signals a focus on long-acting HIV prevention at scale. This has meaningful implications for manufacturing complexity, access economics and the future product mix at Gilead Sciences.
- We will now examine how Gilead Sciences' expanded lenacapavir access strategy could reshape the broader investment narrative around its HIV franchise.
Gilead Sciences Investment Narrative Recap
To own Gilead Sciences, you need to believe its HIV engine can fund a steady shift toward a broader portfolio, while access commitments do not overly strain margins. The key near term catalyst is execution on new HIV products like Yeztugo and Bixlenvo, and the lenacapavir access moves mainly support that long game rather than radically changing it today.
The biggest current risk is still concentration in HIV and exposure to pricing and policy pressure just as Gilead Sciences is investing heavily in new facilities and R&D. Expanded licensing and no profit supply can add complexity to pricing and profitability, so the trade off between reach, costs and future patent cliffs stays front of mind.
The Pan American Health Organization agreement is the clearest echo of this week’s licensing update, because it shows how Gilead Sciences is building real world channels for long acting prevention, not just signing deals on paper. A coordinated regional pathway for twice yearly lenacapavir gives investors a concrete test of whether the access model can scale operationally.
For catalysts, that PAHO framework links directly to questions on uptake, reimbursement and logistics that matter for any long acting HIV franchise. It also sits alongside the Assembly Biosciences HSV collaboration and the Foster City Research Center expansion, which speak to diversification, but the near term proof point for this story is still how well Gilead Sciences turns the lenacapavir access web into sustainable, repeatable demand.
Gilead Sciences' current analyst framework points to revenues of US$34.5b and earnings of US$10.8b by 2029, based on 5.1% yearly revenue growth and an earnings increase of about US$1.6b from US$9.2b today.
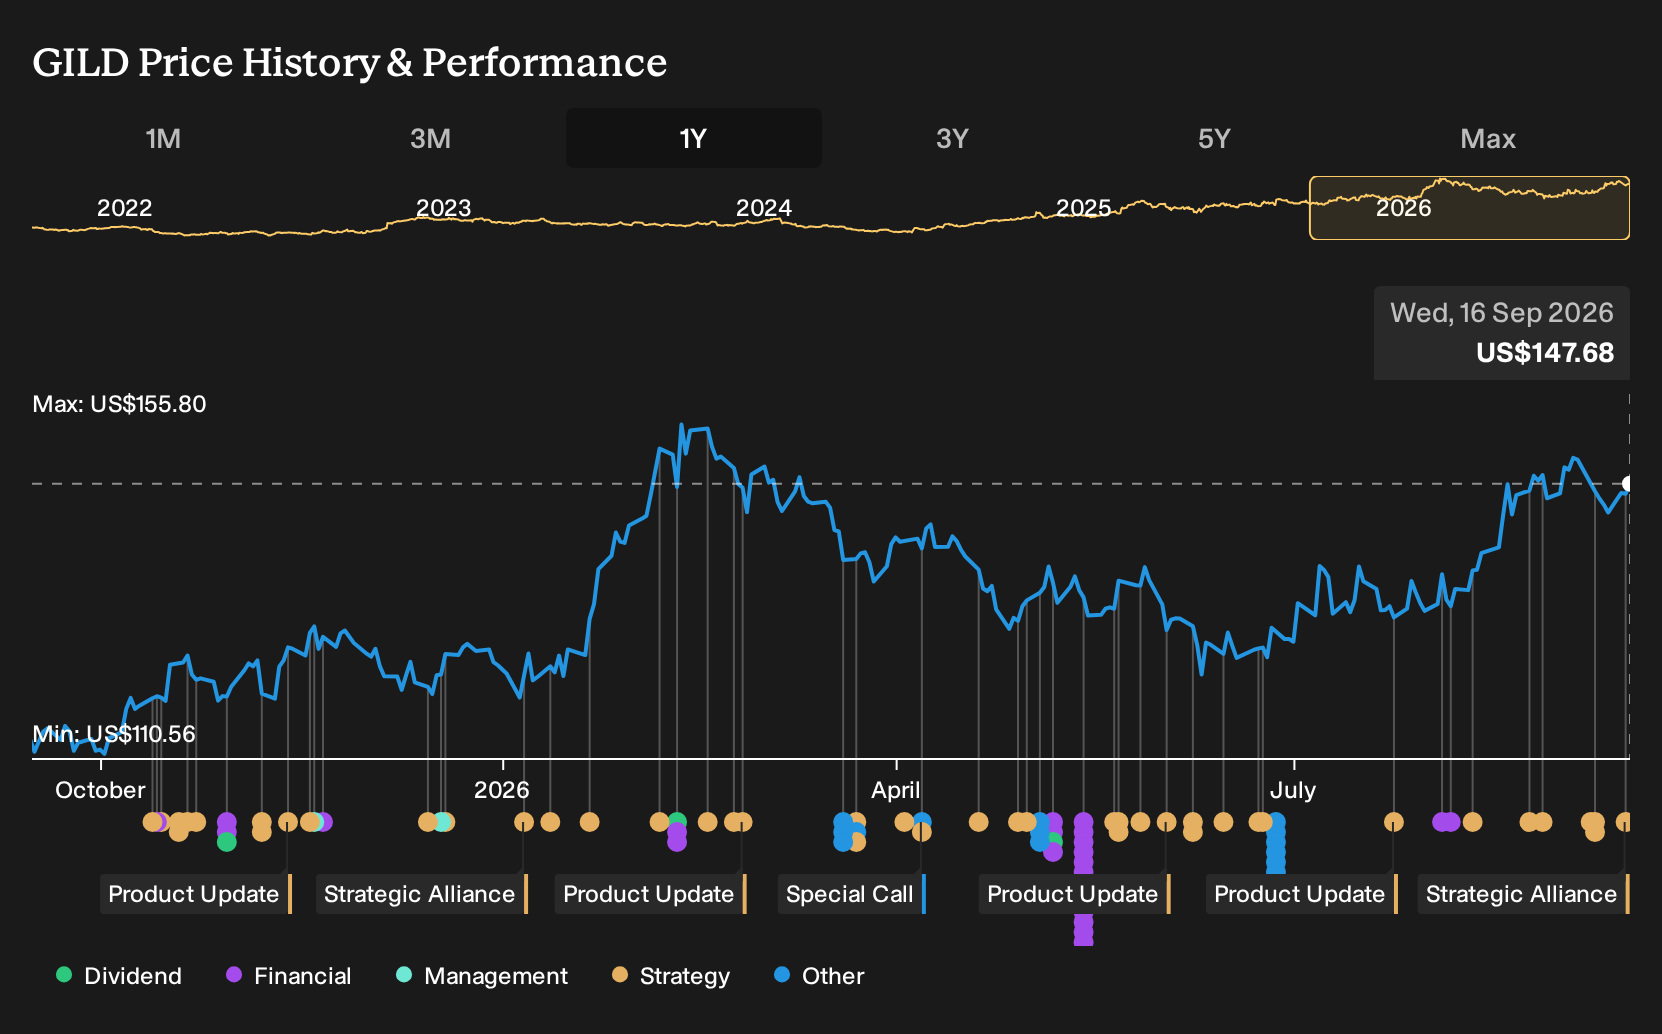
Uncover why Gilead Sciences' fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish alternative story around Gilead Sciences leans hard into long acting HIV prevention as the swing factor. Those analysts were already modeling about US$38.1b of revenue and US$12.7b of earnings by 2029, before this licensing news. You can treat those higher estimates as one possible view that may shift as access deals evolve.
Explore 4 other Gilead Sciences fair value estimates, including one that suggests as much as 111% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gilead Sciences research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gilead Sciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gilead Sciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Gilead Sciences?
Once you have a working view on Gilead Sciences, it often helps to compare that thesis with other businesses that share similar financial traits or risk profiles. The Simply Wall St Screener can narrow the field for you so you spend time only on stocks that fit your preferred mix of quality, valuation and resilience.
- If capital preservation sits high on your list, focus on resilience first by scanning 11 resilient stocks with low risk scores that keep overall risk scores in check while still offering equity upside potential.
- For investors who care most about balance sheet strength, filter for companies with cleaner debt profiles and robust fundamentals through the list of solid balance sheet and fundamentals (22 results).
- If you want to get ahead of the crowd, widen your watchlist with a 16 high quality undiscovered gems that pair strong underlying metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com