
Is IDEAYA Biosciences (IDYA) Fully Valued As Its Phase 3 Trial Begins?
IDEAYA Biosciences (IDYA) is in focus after dosing the first patient in OptimUM-11, a global Phase 3 trial of darovasertib plus crizotinib as adjuvant therapy for high risk primary uveal melanoma.
IDEAYA Biosciences has seen building momentum, with a 90-day share price return of 20.81% and an 11.46% year-to-date gain at a last close of US$37.73. The 1-year total shareholder return of 43.90% points to strong longer term interest as pipeline milestones like OptimUM-11 move forward.
Scan beyond IDEAYA Biosciences to see how other oncology-focused players with strong pipelines stack up using our curated list of 16 high quality undiscovered gems
The rally in IDEAYA Biosciences after the OptimUM-11 milestone puts real expectations into the price. Does the current setup still leave enough upside to justify the clinical and valuation risk from here?
Preferred Price-to-Sales of 15.5x: Is It Justified for IDEAYA Biosciences?
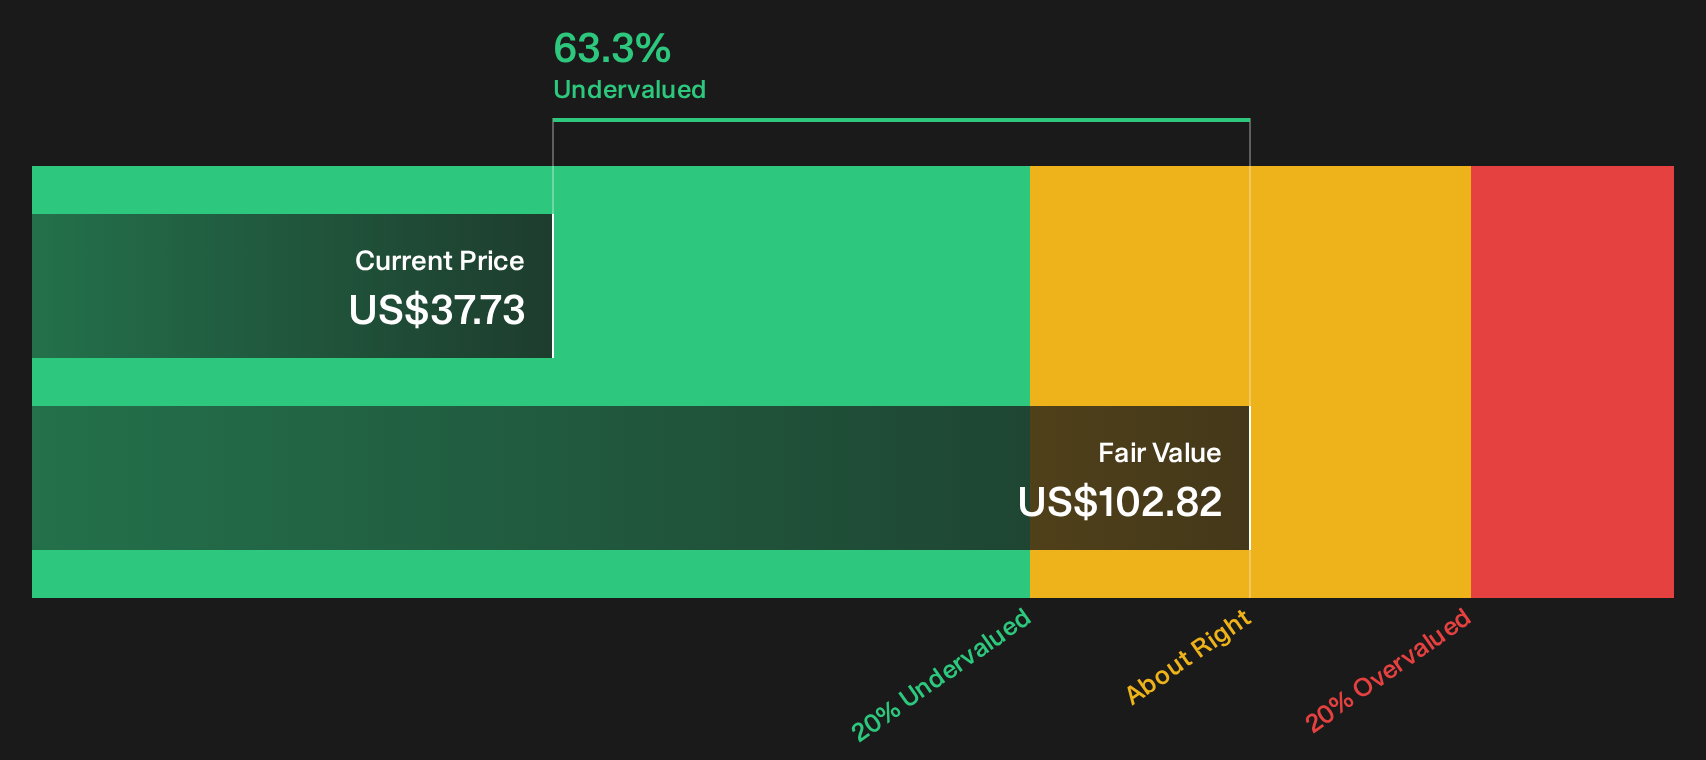
Valuation on IDEAYA Biosciences is split. The stock trades at a P/S of 15.5x, which screens as expensive, yet it is described as trading 63.3% below an estimated fair value based on future cash flows.
The P/S ratio compares the company’s market value to its revenue. For a business like IDEAYA Biosciences that is still loss making, investors often lean on P/S and growth expectations because earnings do not yet provide a clean anchor. A higher multiple usually reflects strong confidence in future sales expansion and the potential to convert that revenue into profit further out.
For IDEAYA Biosciences, that confidence shows up in the numbers. The stock is viewed as expensive on P/S when lined up against the estimated fair P/S of 2.6x and the US Biotechs industry average of 12.5x, as well as a 14.7x peer group average. The current 15.5x level sits well above all three reference points. This suggests the market price already builds in a lot of optimism and could move closer to the lower fair ratio level if sentiment cools or execution disappoints.
Explore the SWS fair ratio for IDEAYA Biosciences.
Result: Price-to-sales of 15.5x (OVERVALUED)
Still, the IDEAYA Biosciences story can wobble if key trials, such as darovasertib combinations, underperform or if partnerships fail to translate into steady revenue.
Find out about the key risks to this IDEAYA Biosciences narrative.
Another View On IDEAYA Biosciences: DCF Signals Undervaluation
While the P/S of 15.5x makes IDEAYA Biosciences look expensive next to peers, the SWS DCF model points in the other direction. On that framework, IDYA at $37.73 trades well below an estimated future cash flow value of $102.82, which frames the stock as undervalued. Which yardstick do you trust more for a business that is still loss making?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out IDEAYA Biosciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around IDEAYA Biosciences is clearly split, with real risks in the story but also meaningful upside angles that investors are watching closely. Act while the information is fresh and test the thesis yourself by weighing both sides in the 2 key rewards and 1 important warning sign
Looking for more IDEAYA Biosciences style investment ideas?
If IDEAYA Biosciences has sharpened your focus on high conviction setups, do not stop here, fresh opportunities rarely wait for latecomers.
- Target rock solid fundamentals and let a list of solid balance sheet and fundamentals (22 results) guide you toward businesses where financial strength does the heavy lifting.
- Hunt for pricing gaps by scanning a 33 high quality undervalued stocks that highlights companies trading below what their quality might justify.
- Prioritize sleep easy positions by filtering for 11 resilient stocks with low risk scores that keep balance sheets and volatility in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com