
Lithium Recycling Move Might Change The Case For Investing In TDK Stock (TSE:6762)
- TDK, through TDK Ventures, invested in R3 Lithium, which is upgrading a commercial lithium carbonate recovery facility in Covington, Georgia for recycled battery materials, targeting continuous production in 2027 to support a more reliable domestic supply of lithium carbonate.
- The move pulls TDK further into the battery materials loop, tying passive components and battery know how to closed loop lithium recovery at commercial scale.
- We now assess how TDK's lithium recycling push with R3 Lithium could reshape its investment narrative around supply chain security.
TDK Investment Narrative Recap
To own TDK, you need to believe its mix of passive components, sensors and energy products can keep compounding earnings, even when end markets wobble. The lithium recycling move fits that story only at the edges in the near term. The more immediate swing factor remains demand for automotive, industrial and rechargeable battery products, where past sluggish orders and competition already pressured some segments.
The biggest near term risk still sits with macro sensitive demand and tariff policy, not with whether the R3 Lithium project succeeds. Currency is another key variable, since past results leaned on FX support and a stronger yen could work against margins. The recycling push looks directionally aligned with supply chain security, but operationally it appears immaterial to near term earnings volatility for now.
The clearest linked announcement is TDK’s Passive Components Factory Tours and Business Strategy Meeting in 2026. That event focuses squarely on core capacitors, inductors and related parts that feed into EVs, industrial equipment and AI hardware. Those lines remain central to the catalyst that analysts highlight, namely steady revenue expansion and efficiency gains driven by quality, productivity and technology investment.
Seen together, the passive components strategy session and the R3 Lithium deal point to tighter integration between front end materials and high volume component output. For investors, the question is whether management can execute on capacity, cost and product mix while tariffs, EV demand and FX move around. That operational follow through, rather than the venture investment alone, is what would likely matter most for TDK’s earnings path.
TDK's current analyst narrative points to revenues of ¥3,147.2b and earnings of ¥330.6b by 2029, based on an assumed 7.9% yearly revenue growth rate and an earnings increase of about ¥134.9b from ¥195.7b today.
Discover why TDK's fair value indicates a 36% potential upside to its current price, which could close faster than many investors expect.
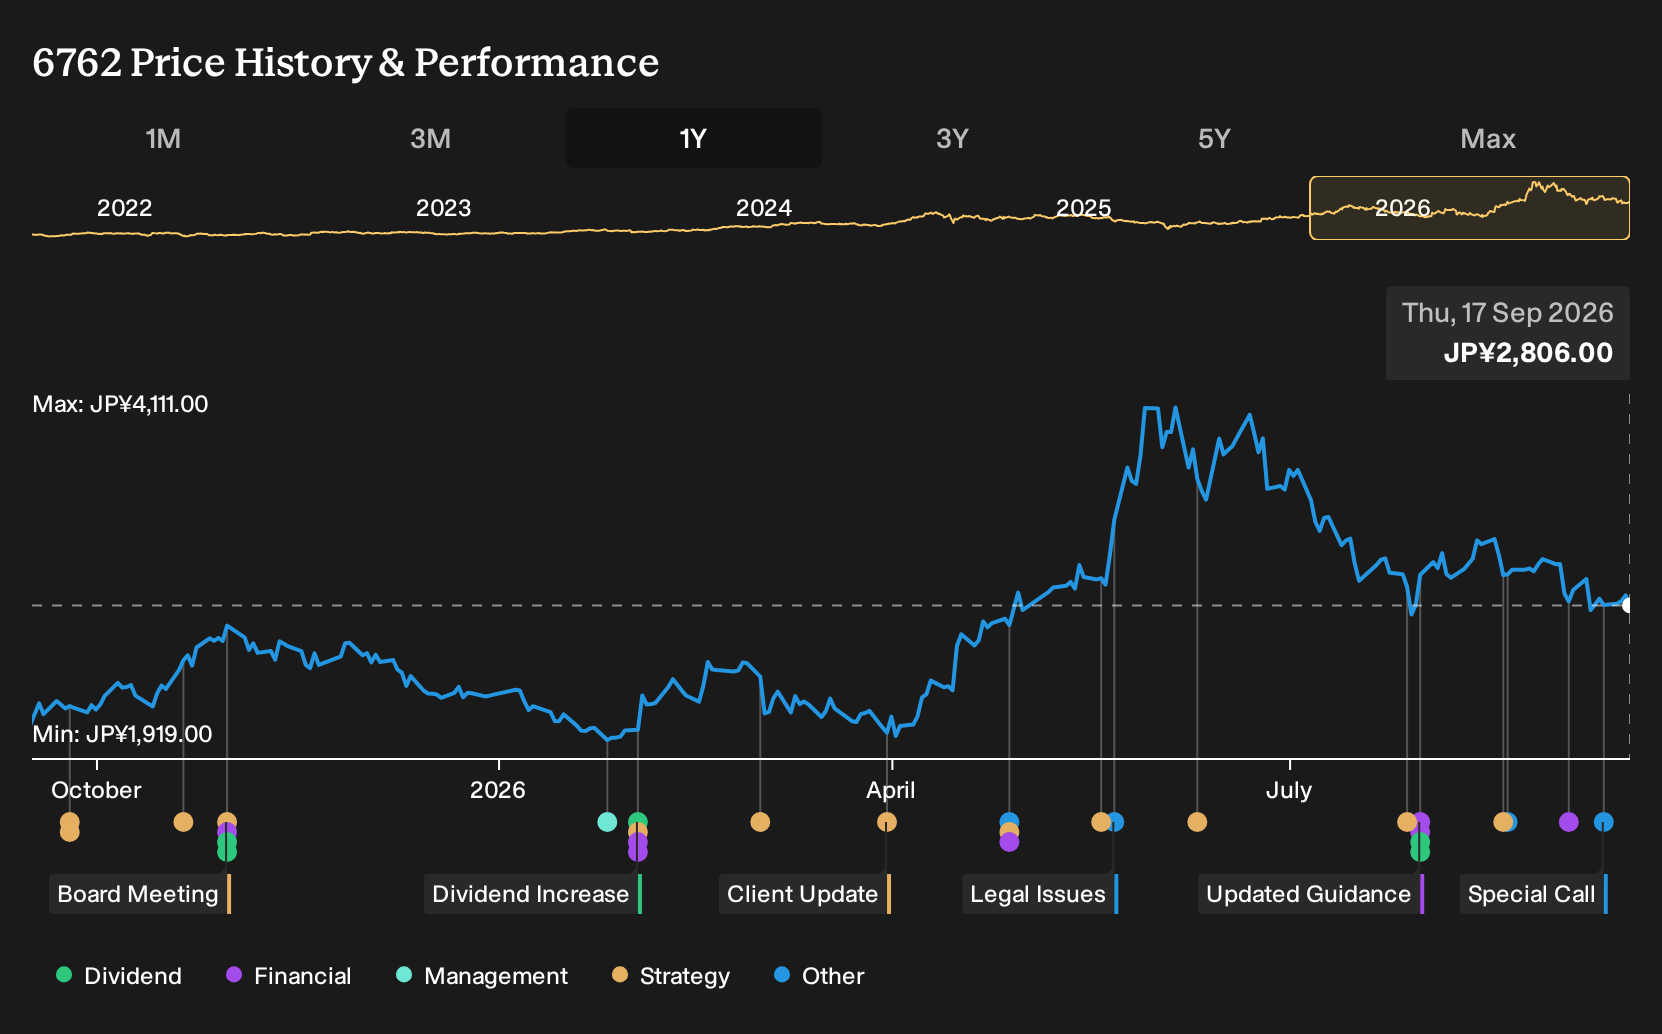
Exploring Other Perspectives
Some of the most optimistic analysts frame TDK’s AI and battery exposure as the real swing factor, not tariffs or FX. Before this R3 Lithium news, that camp was sketching out ¥3,956.1b of revenue and ¥445.2b of earnings by 2029. You can treat those richer forecasts as one possible path that might shift again as new information lands.
Explore 2 other TDK fair value estimates, including one that suggests up to 36% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TDK research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TDK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TDK's overall financial health at a glance.
Looking for more ideas beyond TDK?
Once you have a view on TDK, it can help to compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential upside without paying up for quality, scan a focused set of undervalued candidates through 17 high quality undervalued stocks.
- If capital preservation is your first filter, start with companies that aim for resilience using the 12 resilient stocks with low risk scores.
- Income seekers who care about consistency as much as yield can zero in on stocks offering robust payouts through the 15 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com