
Avantor (AVTR) Raises Guidance, Is The Stock Already Overvalued?
Avantor (AVTR) moved back into focus after reporting second quarter 2026 results, raising its full year organic revenue and adjusted earnings guidance while flagging ongoing softness in Bioscience & Medtech Products.
Avantor’s recent guidance raise comes on the back of strong share price momentum, with a 30 day share price return of 15.6% and a 90 day gain of 62.9%. The 1 year total shareholder return of 25.9% still sits against a 3 year total shareholder return that declined 29.2% and a 5 year total shareholder return that fell 64.5%, signaling a sharp rebound in sentiment but a longer track record that remains pressured.
Scan how Avantor’s rebound compares with other lab supplies and life sciences enablers by reviewing a curated group of 16 high quality undiscovered gems.
Avantor’s sharp rebound and higher guidance leave investors debating what is left to capture. Is most of the upside already reflected in the price, or does valuation still suggest room ahead?
Most Popular Narrative: 7% Overvalued
Avantor’s most followed narrative pegs fair value at $14.56, which sits below the recent $15.61 close and frames the Q2 rebound as slightly ahead of fundamentals.
The analysts have a consensus price target of $14.56 for Avantor based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $19.0, and the most bearish reporting a price target of just $12.0.
See why 10 investors see Avantor as 7% overvalued.
Result: Fair Value of $14.56 (OVERVALUED)
Still, the bullish narrative around Avantor can crack if bioprocessing setbacks persist or aggressive price cuts continue to squeeze margins for longer than analysts currently model.
Find out about the key risks to this Avantor narrative.
Another View: Avantor’s P/S Ratio Sends A Different Signal
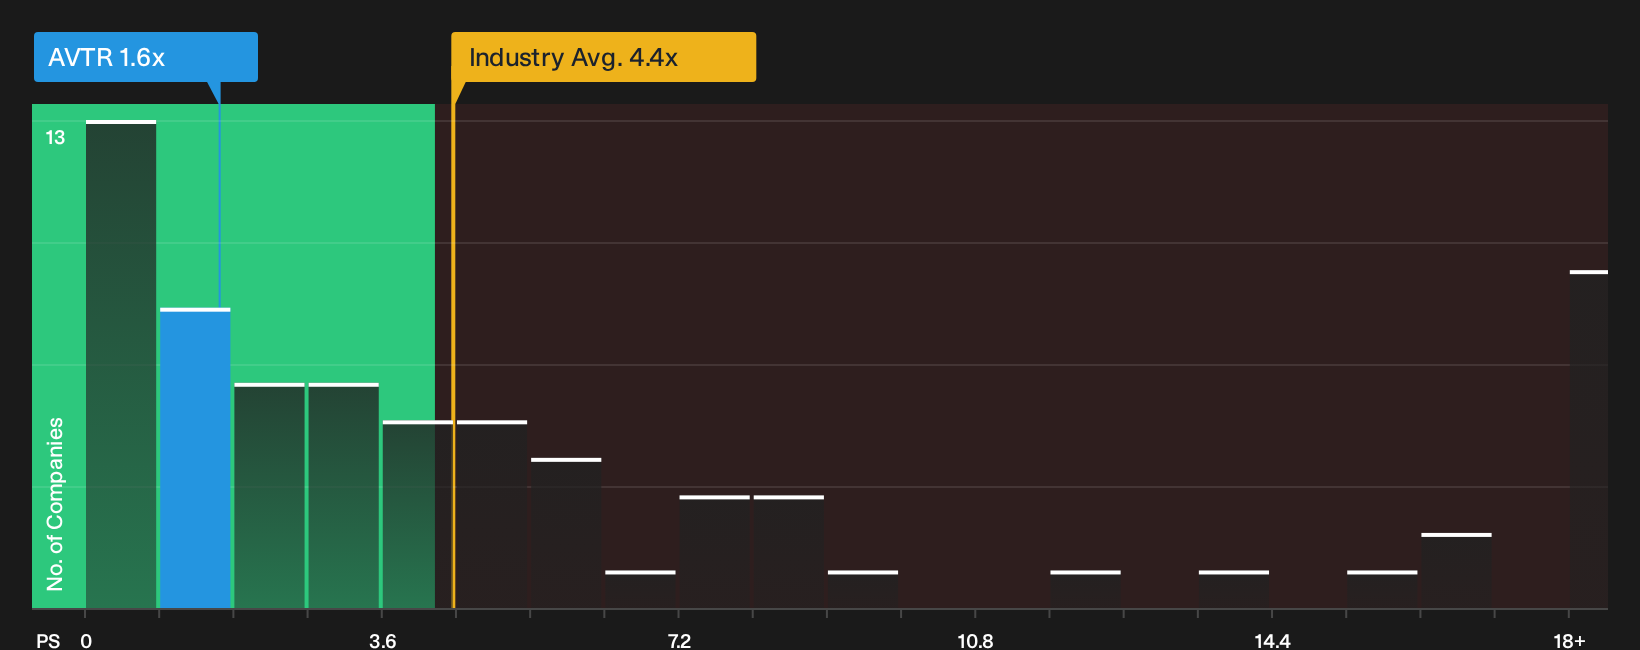
Analyst targets frame Avantor as roughly 7% overvalued on a fair value of $14.56 versus a $15.61 share price. The market is still pricing the business on only 1.6x P/S, compared with 4.3x for the US Life Sciences industry, 8.2x for peers, and a fair ratio estimate of 3.3x.
That gap suggests the stock price already reflects some of the near term risks while still leaving room for the multiple to move closer to the fair ratio if confidence in the turnaround improves. Alternatively, the discount could simply be the market’s way of indicating that the recovery story needs more proof.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Avantor so far, or leaning one way? Either way, move quickly and stress test the story yourself by weighing the 3 key rewards and 1 important warning sign.
Looking for more Avantor sized investment ideas?
Do not stop your research with Avantor alone. Broaden your watchlist with a few focused idea lists built to surface opportunities you might otherwise miss.
- Target resilient balance sheets and consistent fundamentals by scanning a curated list of solid balance sheet and fundamentals (22 results) that keeps financial strength front and center.
- Hunt for potential value gaps by reviewing a 33 high quality undervalued stocks that filters for quality businesses trading at what could be appealing prices.
- Secure more predictable income streams by checking a focused group of 6 dividend fortresses that aim for higher yields with durability in mind.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com