
Will Higher Fuel Costs Change American Airlines Stock Narrative
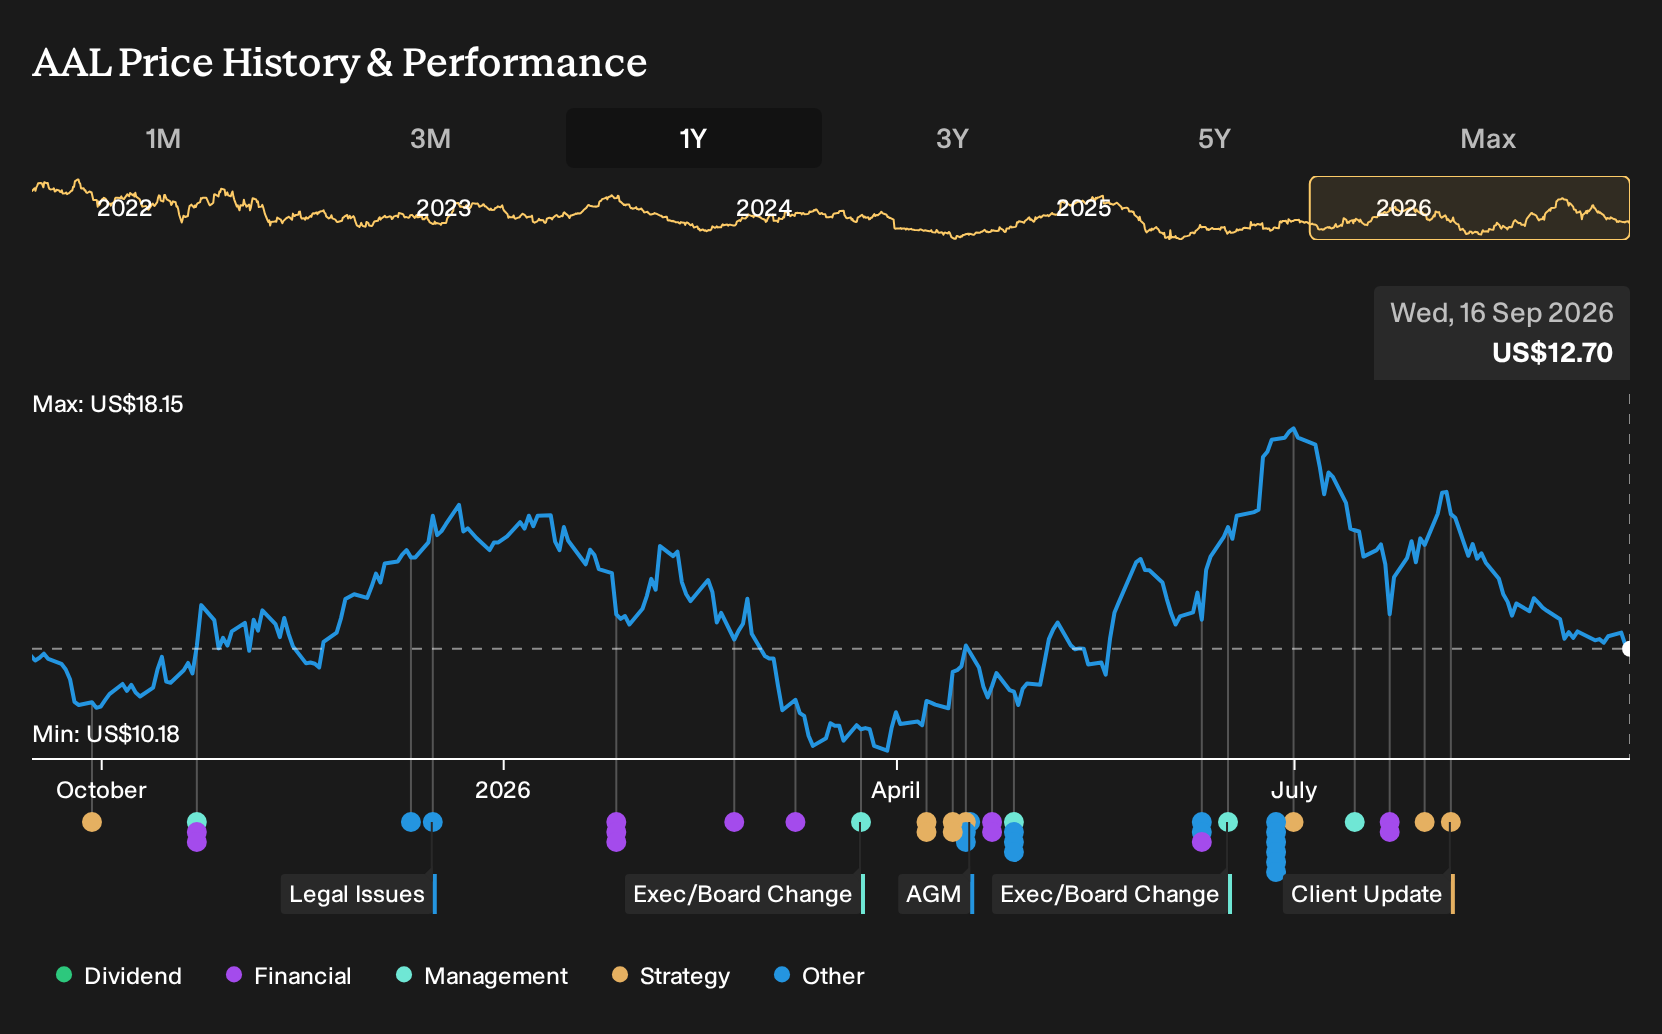
- American Airlines Group recently highlighted at Morgan Stanley's Laguna conference that higher jet fuel costs could add about US$1b in expenses for the final quarter, with management openly discussing possible flight capacity cuts to protect profitability.
- The carrier is prioritizing profitability over market share as rising energy costs squeeze margins, while analysts have trimmed near term earnings expectations despite projections for revenue growth.
- We will now look at how American Airlines Group's investment narrative could be reshaped by the shock of sharply higher fuel costs.
Compare how American Airlines Group is handling fuel cost pressure with other carriers by scanning a curated list of list of solid balance sheet and fundamentals (22 results) that may be better positioned for shocks like this.
What Is American Airlines Group's Investment Narrative?
To own American Airlines Group, you have to buy into a simple idea. A large, global carrier with a 1,013 aircraft fleet and deep US and international networks can turn its scale into durable cash generation once fuel and financing costs are kept in check. The recent Laguna conference appearance fits that story. Management is clearly prioritizing profitability, even if that means trimming capacity or accepting softer near term revenue momentum while jet fuel and Brent pricing stay elevated.
The near term swing factors are now pretty clear to you as a shareholder: fuel costs, pricing discipline and how tightly American Airlines Group controls capital spending and leverage. The airline is still unprofitable, carries negative equity and interest costs that are not well covered, which makes a US$1b fuel headwind feel very material for upcoming quarters. Analysts still model revenue growth and a path to profitability over the next three years, but the bar for execution just moved higher.
Even so, there is one balance sheet detail that could matter far more than the airline’s fuel bill...
There's only one way to know the right time to buy, sell or hold American Airlines Group. Head to Simply Wall St's company report for the latest analysis of American Airlines Group's Fair Value.
Exploring Other Perspectives
One alternate view focuses less on fuel and more on long term demand risk for American Airlines Group. The most pessimistic analysts were only penciling in about 2.8% annual revenue growth to roughly US$60.8b by 2029 and earnings of US$1.3b before this fuel shock, so their already cautious story may need a further rethink.
Explore 7 other American Airlines Group fair value estimates, including one that suggests there may be as much as 21% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Airlines Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for American Airlines Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Airlines Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Airlines Group?
If the fuel story at American Airlines Group has sharpened your focus on risk and balance sheet strength, it can help to widen the lens and scan other companies that line up with your preferred traits using the Simply Wall St Screener.
- If capital preservation comes first for you, start with a basket of relatively sturdy businesses by reviewing 11 resilient stocks with low risk scores that may offer a more measured risk profile.
- Income focused investors can zero in on companies with stronger yields by running through 6 dividend fortresses that concentrate on higher payout opportunities.
- For those hunting for potential mispricings, cast a wider net across 33 high quality undervalued stocks that combine solid fundamentals with more appealing valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com