
Earnings Guidance Raised Is Altering The Investment Case For Sekisui House Stock (TSE:1928)?
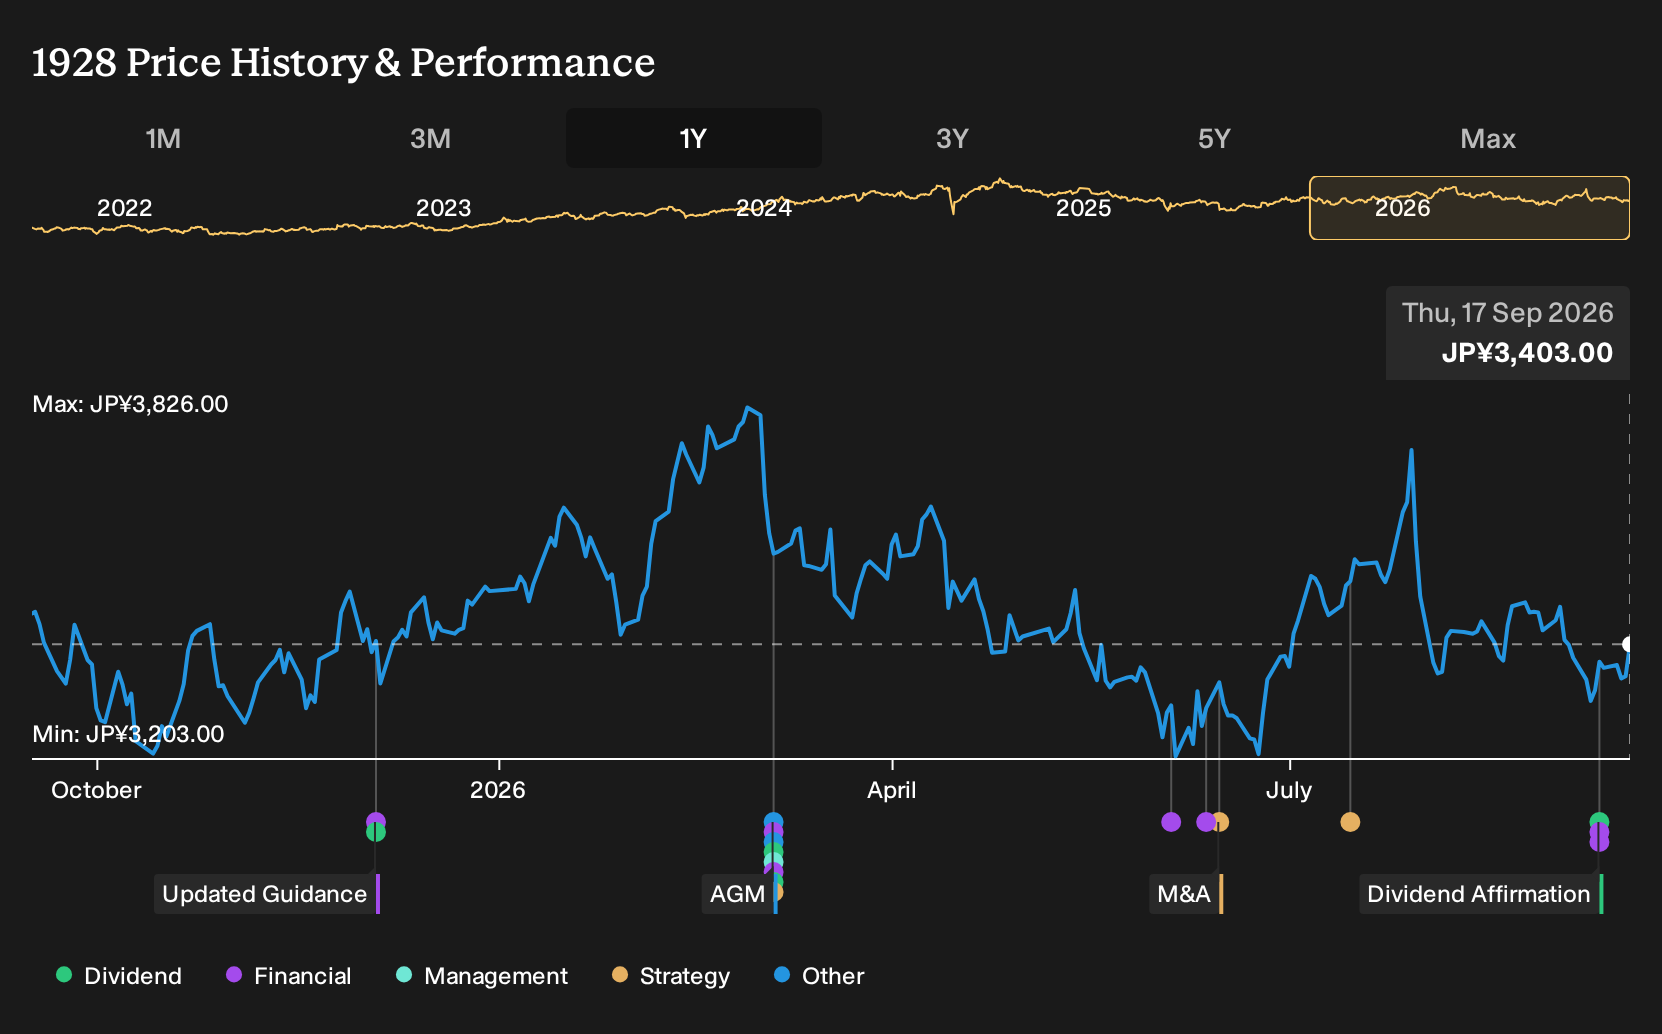
- Sekisui House reported half-year sales of JPY 1,965,644 million and net income of JPY 125,053 million, with earnings per share from continuing operations above the prior year, and affirmed an interim dividend of JPY 72.00 per share, payable from September 30, 2026.
- The company raised full-year profit guidance while slightly lowering its net sales outlook, which indicates a tighter focus on profitability and cost control within Sekisui House's operations.
- We will now look at how Sekisui House's higher earnings guidance might influence the investment narrative around its profit quality and resilience.
What Is Sekisui House's Investment Narrative?
The big picture for Sekisui House is simple. You need to believe in a capital intensive housing platform that can keep converting a broad mix of projects into steady earnings and cash, even when top line momentum is uneven. The latest half year update fits that idea. Sales were lower than a year ago, yet profit and earnings per share from continuing operations were higher, and management felt comfortable affirming the JPY 72.00 interim dividend.
The raised full year profit guidance, despite a slightly lower net sales outlook, suggests that near term catalysts are mostly about execution and pricing discipline across detached houses, rental housing and overseas developments. That can support the current payout, but it also sharpens the focus on balance sheet usage and funding, since this is a business that leans on external borrowing and still needs healthy operating cash flow to keep everything moving.
Even so, there is one pressure point in Sekisui House's financial profile that deserves a closer look before assuming this resilience can comfortably continue.
There's only one way to know the right time to buy, sell or hold Sekisui House. Head to Simply Wall St's company report for the latest analysis of Sekisui House's Fair Value.
Exploring Other Perspectives
Simply Wall St Community members have only two fair value estimates on Sekisui House so far, ranging from about JPY 3,844 to JPY 4,724 per share. Those views were set before the September 2026 earnings, dividend affirmation and updated guidance, so treat them as a starting point and explore several contrasting opinions.
Explore another Sekisui House fair value estimate, including one that suggests there may be as much as 39% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sekisui House research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sekisui House. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sekisui House's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sekisui House?
If the Sekisui House update has you thinking more broadly about how earnings resilience and dividends fit into your portfolio, it can help to scan a wider set of opportunities with similar traits.
- For investors who want income that does not rely on a single payer, consider dividend-focused opportunities through 14 dividend fortresses that aim to balance yield with underlying earnings strength.
- If capital preservation and calmer drawdowns matter most to you, filter for steady operators using a 12 resilient stocks with low risk scores that screens for businesses with more resilient profiles and lower risk scores.
- When you want something off the beaten path but still grounded in fundamentals, search for potential future leaders through 74 high quality undiscovered gems that combine solid financials with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com