
ServiceTitan (TTAN) Wins Canopy Services Business After Sell Off But Is The Value Case Priced In
ServiceTitan (TTAN) is back in focus after Canopy Services, a roofing platform, moved its growing portfolio of brands onto the company’s software, centralizing sales, production, customer management, and reporting.
For investors, the Canopy Services win lands at an awkward time for the stock. ServiceTitan’s share price has fallen 33.6% over the past 30 days and is down 42.3% year to date, with a 1-year total shareholder return declining 48.5%. This signals that recent momentum has been fading even as earnings, guidance and new customer announcements keep the story in the headlines.
Spot opportunities beyond ServiceTitan by scanning a curated set of resilient software and infrastructure platforms in our 11 resilient stocks with low risk scores.The question now is simple. After a sharp reset in ServiceTitan’s share price, does the current valuation still reward new risk, or are recent buyers already leaning too far out on the growth story?
Most Popular Narrative: 21% Undervalued
ServiceTitan’s most followed narrative values the stock at $74.62 per share, compared with the last close at $58.67. This frames the current reset as a discount to that fair value line rather than a premium story waiting to be corrected.
The latest call opened with a frame that had not been fully settled previously. Management described Max as an increasing priority, with Vahe acknowledging "there''s definitely been an increase in the weight in terms of Max and what resources we''ve been putting into it over the last few quarters." He added: "We''re trying very hard not to have a huge pullback in other areas." The language was incremental, representing a shift in emphasis rather than a structural reorientation.
See why 1 investors see ServiceTitan as 21% undervalued.
According to LunaRodas, the writer behind the narrative, that $74.62 view implies ServiceTitan trades at roughly a 21% gap to perceived fair value, even after factoring in the firm’s current loss making position and the forecast that it is expected to remain unprofitable over the next three years.
The same storyline leans heavily on revenue that is forecast to grow 13.4% per year, slightly ahead of the wider US market at 13.3%. It also accepts that the business carries a negative Return on Equity of 8.03% today and is not expected to clear that profitability hurdle within the next three years.
Analysts contributing to the broader picture are also in tight agreement on direction, with a consensus target price of $97.53 that sits 66.2% above the last close. The narrative’s $74.62 estimate is more conservative than that and is grounded in Simply Wall St’s DCF view that values future cash flows at $111.39 per share.
In simple terms, the narrative treats ServiceTitan as a growth platform with improving loss levels over the past five years, a forecast revenue line still rising in the mid teens, and a share price that has fallen enough relative to those assumptions to make valuation the central debate rather than growth credibility.
Result: Fair Value of $74.62 (UNDERVALUED)
Still, the ServiceTitan narrative could be disrupted if Max adoption slows against management’s stated goals, or if ongoing losses at $129.003 million weigh more heavily on sentiment.
Find out about the key risks to this ServiceTitan narrative.
Another View On ServiceTitan’s Valuation
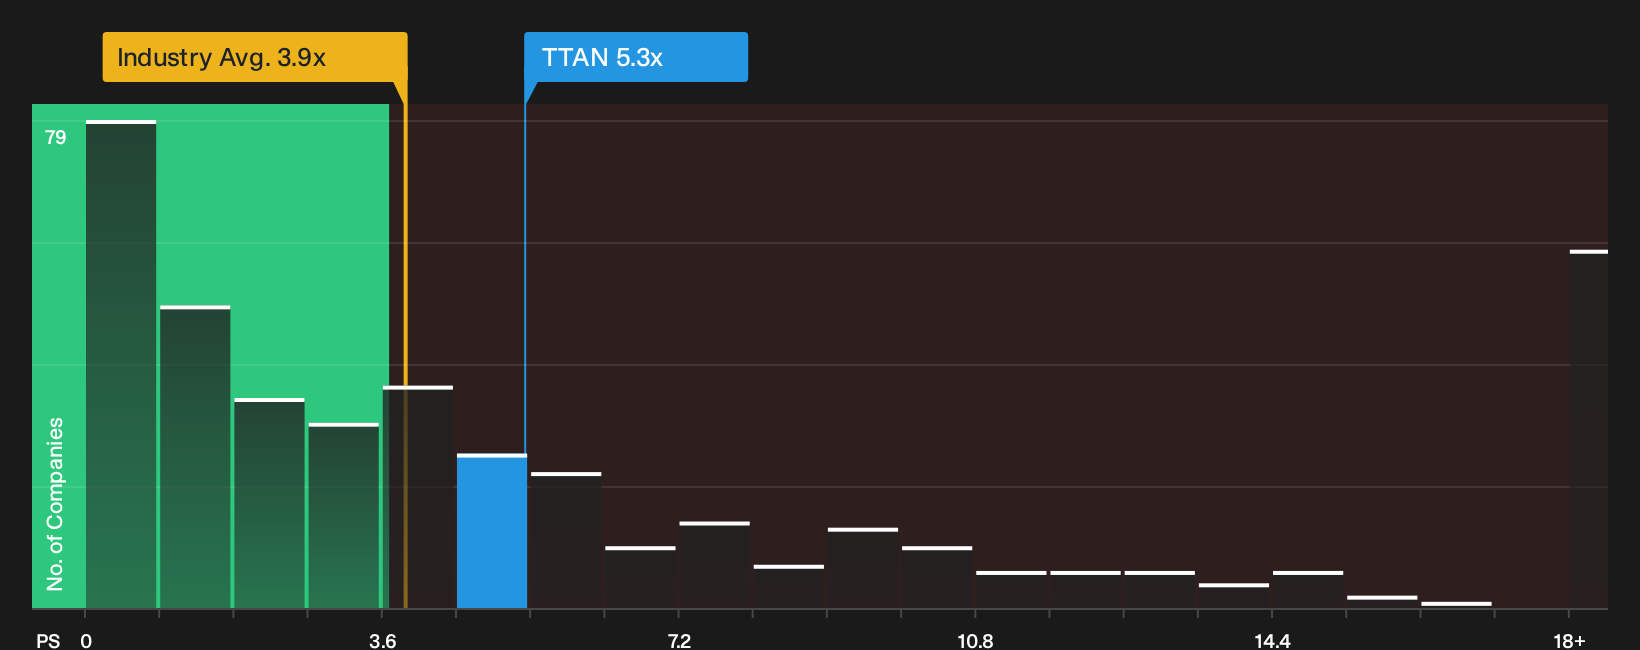
There is a twist once you step away from the SWS DCF model. On a simple P/S lens, ServiceTitan trades at 5.3x sales, which is higher than both the US Software industry at 3.9x and peer average at 4.7x, and slightly above a fair ratio of 5.2x. That richer multiple can either be a justified premium or a signal that expectations still leave less room for error than the DCF suggests.
If you want to see how those P/S gaps stack up in practice and where the numbers could pull the price over time, See what the numbers say about this price — find out in our valuation breakdown..
Here is how ServiceTitan’s current market multiple lines up next to the sector and that fair ratio reference point visually, so you can judge whether the premium feels stretched or still reasonable relative to the story investors are pricing in:
Next Steps
Mixed signals can feel uncomfortable, especially with a reset like ServiceTitan’s. Move quickly through the full picture and weigh both sides of the story with 4 key rewards and 3 important warning signs
Looking for more ideas beyond ServiceTitan?
If you stop here, you only see one corner of the market. Cast the net wider now so you do not miss the next move.
- Target potential mispricings by scanning a curated pool of quality stocks trading below their implied worth using the 33 high quality undervalued stocks.
- Secure more dependable cash flows by focusing on companies with robust payouts through the 6 dividend fortresses.
- Prioritize resilience and capital protection by filtering for businesses with strong finances using the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com