
Medline (MDLN) Moved Higher, What Is Drawing Fresh Attention?
Medline (MDLN) heads into the Morgan Stanley 24th Annual Global Healthcare Conference on September 15 in New York, giving investors a fresh chance to hear directly from CEO Jim Boyle and CFO Mike Drazin.
Medline’s share price has been under pressure in 2026, with the year-to-date share price return down 18.78% and the recent 90-day share price return down 8.21%. However, the 1-day and 7-day share price returns of 2.74% and 1.85% suggest short-term momentum has begun to improve ahead of the conference.
See how Medline compares to other healthcare suppliers under pressure and showing fresh momentum by tracking our hand-picked list of solid balance sheet and fundamentals (22 results).
Medline’s bulls point to solid revenue and net income growth, as well as a discount to analyst targets. Bears focus on the weak share price performance. Which side does the current valuation actually support?
Most Popular Narrative: 26% Undervalued
Medline’s most followed valuation narrative pegs fair value at $44.62 per share, above the recent $32.99 close. This places significant importance on what management can execute from here.
Rollout of Mpower, the AI enabled supply chain control tower, and broader automation such as AutoStore and Symbotic is expected to lift throughput, reduce labor intensity and improve inventory efficiency, which can support net margin and earnings quality over time.
See why 1 investors see Medline as 26% undervalued.
Result: Fair Value of $44.62 (UNDERVALUED)
Still, the Medline story carries real tension, with FDA compliance issues and potential tariff changes both capable of challenging the upbeat valuation narrative that investors are leaning on.
Find out about the key risks to this Medline narrative.
Another View: Medline Through The P/E Lens
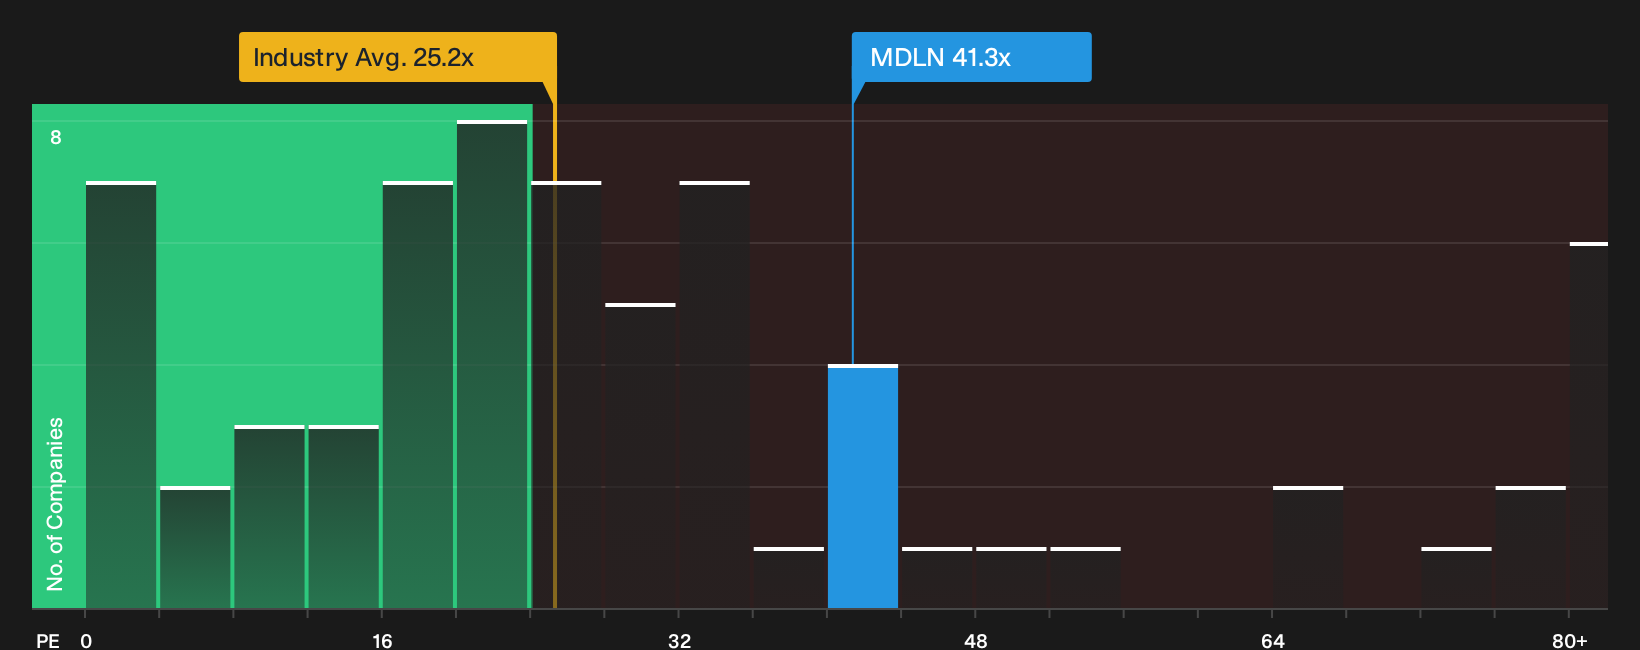
DCF work suggests Medline looks appealing, yet the simple earnings multiple tells a different story. The stock trades on a P/E of 41.3x, which is higher than the US Medical Equipment sector at 25.1x, the peer group at 19.6x, and even above its own fair ratio of 40.4x. That gap points to less room for error if earnings fall short. How comfortable are you paying a premium price for a company already flagged as undervalued on cash flows?
To see how that premium multiple stacks up against the underlying numbers, take a closer look at our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Medline after all this. Move quickly from headline takes to hard numbers and compare both sides of the story with the 3 key rewards and 3 important warning signs.
Looking for more Medline sized investment ideas?
If Medline has your attention, do not stop here. Use this momentum to scan other opportunities so you are not leaving potential winners on the table.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (22 results).
- Hunt for quality at a discount by checking the 33 high quality undervalued stocks before prices move away from you.
- Unearth potential future leaders early by reviewing the 16 high quality undiscovered gems while they are still off most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com