
3 Australian AI Stocks To Own In September 2026
Higher US interest rates are pushing up borrowing costs worldwide, which puts pressure on heavily indebted giants and pushes investors to think harder about where growth might actually justify the risk. That is where smaller Australian companies building real-world AI tools can look interesting. In this article you will see three early stage AI small caps from our screener that could deserve a spot on your watchlist.
These stocks are just a starting sample from the AI Small Caps idea, with our full screen surfacing 3 more companies with equally compelling narratives that are not covered below. To hunt for your own edge, head straight to the AI Small Caps screener to identify, filter, and analyze the highest conviction opportunities that match your risk profile.
Pureprofile (ASX:PPL)
Pureprofile is a data and insights business that runs online research for brands and agencies, with most of its A$65 million in revenue tied to Data & Insights services and AI-enabled tools like Datarubico and Audience Builder. The stock is tiny, with a market value around A$36 million.
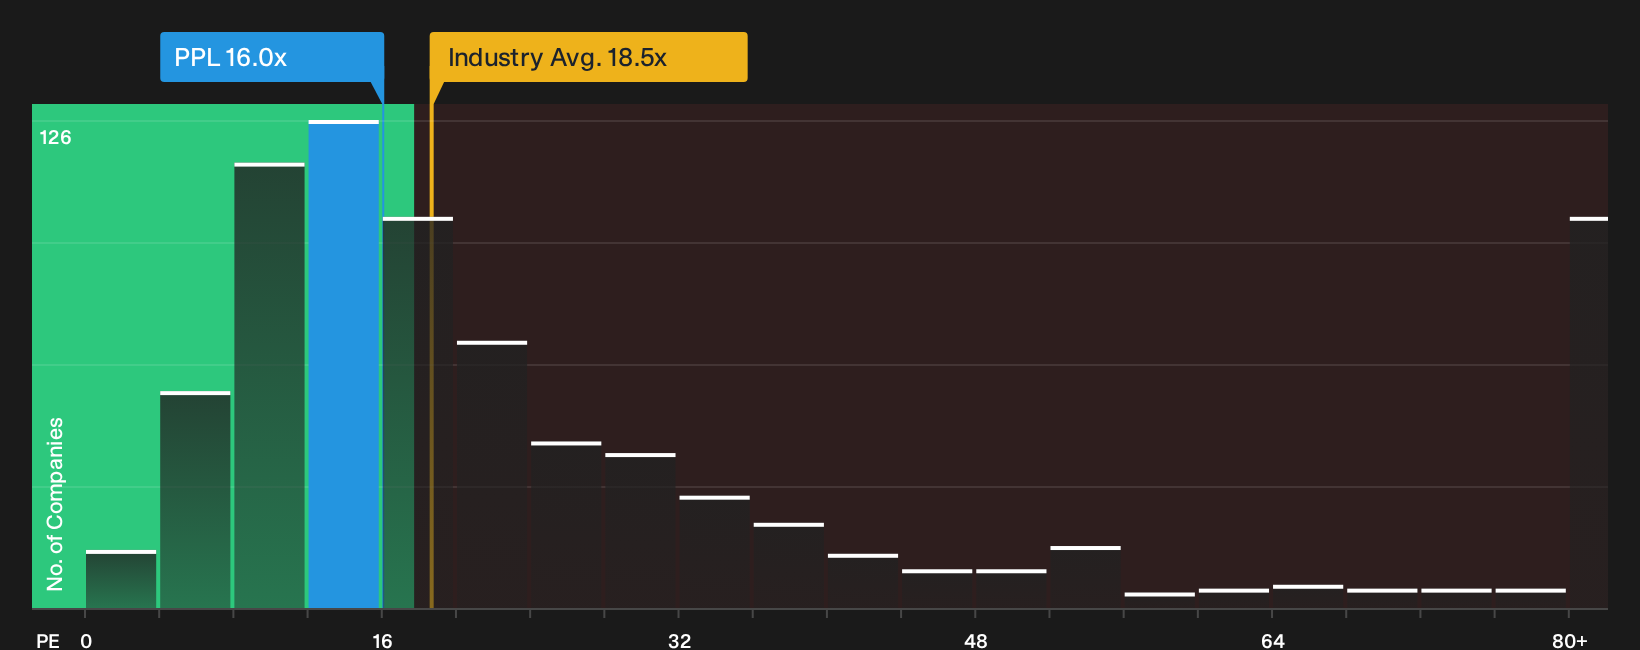
For an AI Small Caps investor, Pureprofile brings a commercial AI product already embedded in its survey and audience targeting engine, yet still priced on a P/E of about 16x. Earnings and net income are growing. The real question is how margins evolve if one unseen pressure on its AI platforms shifts.
If that margin picture matters to you, start with the 4 key rewards and 1 important warning sign to see where Pureprofile’s AI upside could be capped or could accelerate.
Dicker Data (ASX:DDR)
Dicker Data is a wholesale distributor supplying AI-capable hardware, software, and cloud infrastructure across Australia and New Zealand, including Copilot+ PCs and data center gear that underpin machine learning and automation. It generates about A$2.6b from computer peripherals and is valued around A$2.7b.
Dicker Data plugs straight into the AI Small Caps theme by supplying the servers, storage, and Copilot+ PCs that let enterprises actually run machine learning workloads, rather than just talk about them, which is why its AI infrastructure expansion matters so much.
"Expansion into AI infrastructure and solutions, including the delivery of Australia's first AI factory in partnership with Dell and further AI pipeline opportunities, aligns the company with accelerating enterprise digital transformation and creates substantial upside for advanced solutions revenue, especially as AI adoption grows across Australia and New Zealand."
What really moves the needle from here is how one subtle shift in deal mix filters through to future margins and earnings power.
That deal mix question is exactly what the full narrative for Dicker Data unpacks, including how AI factory projects could reshape Dicker Data’s earnings quality and risk profile.

Data#3 (ASX:DTL)
Data#3 plugs into the AI Small Caps idea through its data and AI solutions arm, which layers machine learning and analytics onto a much broader IT services base across software, infrastructure, and support work.
Data#3 runs a diversified IT services model across Australia, earning about A$552.9 million from Infrastructure Solutions, A$276 million from Services, and A$78.1 million from Software Solutions, with a market value around A$1.7b.
"The accelerating shift by customers to multiyear subscription and as-a-service models (evidenced by recurring revenue increasing to 69% and rapid expansion in Device-as-a-Service), positions Data#3 for higher, more stable, and predictable revenue and margin growth over time as the mix continues to improve."
The real swing factor is how one quiet change in customer demand shapes future pricing power across Data#3’s higher margin AI-focused work.
That quiet shift is exactly what the full narrative for Data#3 unpacks. It reveals how Data#3’s recurring models and AI work could be accelerating faster than headline figures suggest.

Seeking Fresh Alternatives Beyond AI?
Markets move fast and the strongest breakout stories rarely stay under the radar for long. Scan fresh ideas with real momentum before the crowd catches on and consider researching them promptly.
- Spot potential income workhorses with staying power by tracking the 4 dividend fortresses before yields change and the most attractive entry points become less available.
- Explore the next wave of electrification by scanning the 37 power grid technology and infrastructure stocks while these infrastructure opportunities are still less widely held in many portfolios.
- Prepare for possible shifts in commodity sentiment by reviewing the 36 elite gold producer stocks while the strongest operators may still be quietly priced as if conditions are unchanged.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com