
JetBlue (JBLU) Stock Looks Undervalued Based On Its Sales Story
JetBlue Airways shares have been under pressure for years, and that kind of slide naturally raises a blunt question for investors who still follow the stock. Is the current price around US$4.30 really supported by the airline's ability to generate sales?
- The share price has fallen 72.7% over the past 5 years, which puts the focus squarely on whether the business now justifies even this lower valuation through its revenue base.
- With investor attention likely to be tied to how efficiently JetBlue converts ticket and ancillary sales into cash, any shift in costs or balance sheet strength can change how much investors are willing to pay for each dollar of revenue.
- Your read on JetBlue Airways is one view; the desks covering it have another. See what analysts think JetBlue Airways's shares could be worth.
The issue now is whether JetBlue's current market price lines up with what its sales profile can rationally support.
If you are considering whether JetBlue Airways at around US$4.30 still makes sense based on its sales, it can be helpful to compare that question against a wider group of 33 high quality undervalued stocks
Does JetBlue Airways Look Undervalued on Sales?
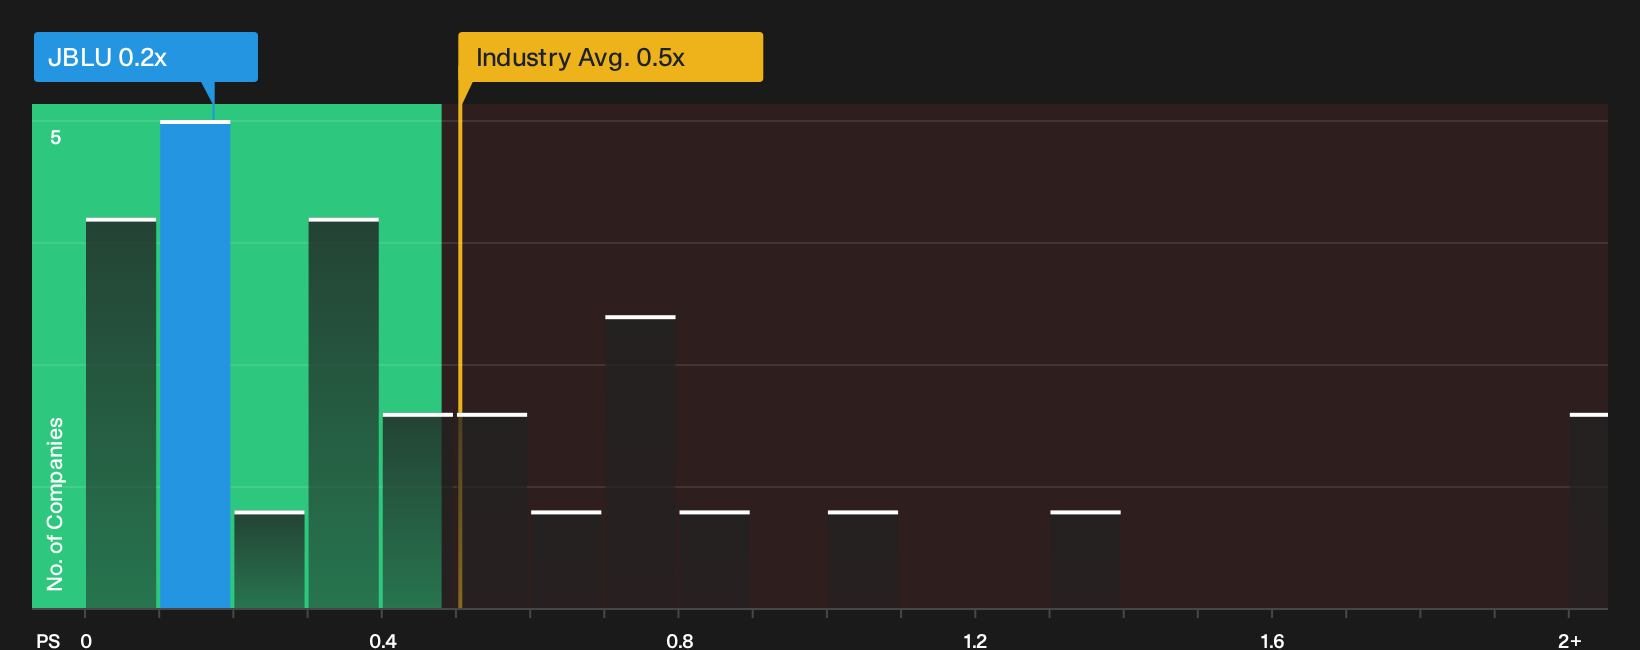
P/S works well for JetBlue Airways because investors often look at how much revenue an airline can produce relative to its market value when profits are uneven. In this context, the stock trades on a P/S of about 0.2x, which is well below the Airlines industry average of roughly 0.5x and also below the peer group around 0.5x. That is a wide gap in how the market currently values each dollar of JetBlue's sales compared with many other carriers.
The Fair Ratio model, which adjusts the benchmark P/S for JetBlue's own growth profile, margins, scale and risk, suggests the current multiple sits below what might be expected for this business. That indicates the shares screen as undervalued on revenue compared with this tailored yardstick, although you still need to judge whether the balance sheet, costs and cash generation justify closing any gap. Explore the numbers behind JetBlue Airways's P/S valuation.
The JetBlue Airways Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for JetBlue Airways pick up where the valuation puzzle leaves off. They spell out which paths for future growth, margins and earnings would need to play out for JetBlue Airways' share price to look meaningfully higher or lower than it does today. Each scenario links its numbers to a clear view on where the business, profitability and key risks could head next as fresh information comes through.
Community views on JetBlue Airways split between those who see the JetForward plan creating upside and those who focus on balance sheet risk and possible restructuring.
Bull case: 21% undervalued
"Major operational improvements, including leading on-time performance, network optimization, and elevated customer satisfaction, are expected to support better load factors and boost both revenue and net earnings through increased preference for JetBlue..."
Discover why this Narrative puts JetBlue Airways at 21% undervalued.
Bear case: 23% overvalued
"Several bearish analysts point to JetBlue's capital structure, including the conversion price of its convertible debt around US$6.12, as a ceiling on share upside and a reason to consider a Chapter 11 restructuring as a potential tool to reset the balance sheet..."
Explore why this Narrative puts JetBlue Airways at 23% overvalued.
One more crucial angle on JetBlue Airways that this valuation has not touched
Price, revenue and scenarios only tell part of the story, because the people setting JetBlue Airways' priorities and how they are rewarded can heavily shape where the business goes next. See who runs JetBlue Airways and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com