
Glanbia (ISE:GL9) Could Be 18% Undervalued On CFO Handover
Glanbia (ISE:GL9) drew fresh attention on 10 September 2026 after announcing a planned CFO handover, with long-serving finance chief Mark Garvey set to be succeeded by Wendy Chang Smith.
That leadership update landed during a sharp pullback in Glanbia’s share price. The stock has fallen around 12% over the past month and about 9% over 90 days, even though the year-to-date share price return is up 37.6% and the 1-year total shareholder return is 44.8%. This suggests longer term holders have still seen strong gains while short term momentum has faded.
Capitalize on the leadership shake-up at Glanbia by scanning a hand-picked 618 high quality undiscovered gems that could be next in line for a rerating.The share price reset has left Glanbia trading at a sizeable discount to both analyst targets and one estimate of fair value. Is that caution sensible given the CFO transition, or has the pullback gone too far on price?
Most Popular Narrative: 18% Undervalued
On the most followed narrative view, Glanbia’s fair value of €24.40 sits well above the last close at €19.93. This puts the recent pullback against a backdrop of upgraded long term earnings and margin assumptions.
Ongoing expansion and investment in Health & Nutrition and Dairy Nutrition divisions, supported by growing global demand for functional foods, supplements, and high-protein offerings (including plant-based), position Glanbia to capture rising revenue and achieve mid-single-digit volume-led growth, especially in international and emerging markets like Asia and Latin America (positively impacting top-line growth).
See why 16 investors see Glanbia as 18% undervalued.
Result: Fair Value of €24.40 (UNDERVALUED)
Still, the bullish Glanbia story relies on easing whey input costs and smooth execution of its transformation plan. Setbacks could quickly challenge those fair value assumptions.
Find out about the key risks to this Glanbia narrative.
Another View: Glanbia On Earnings Multiples
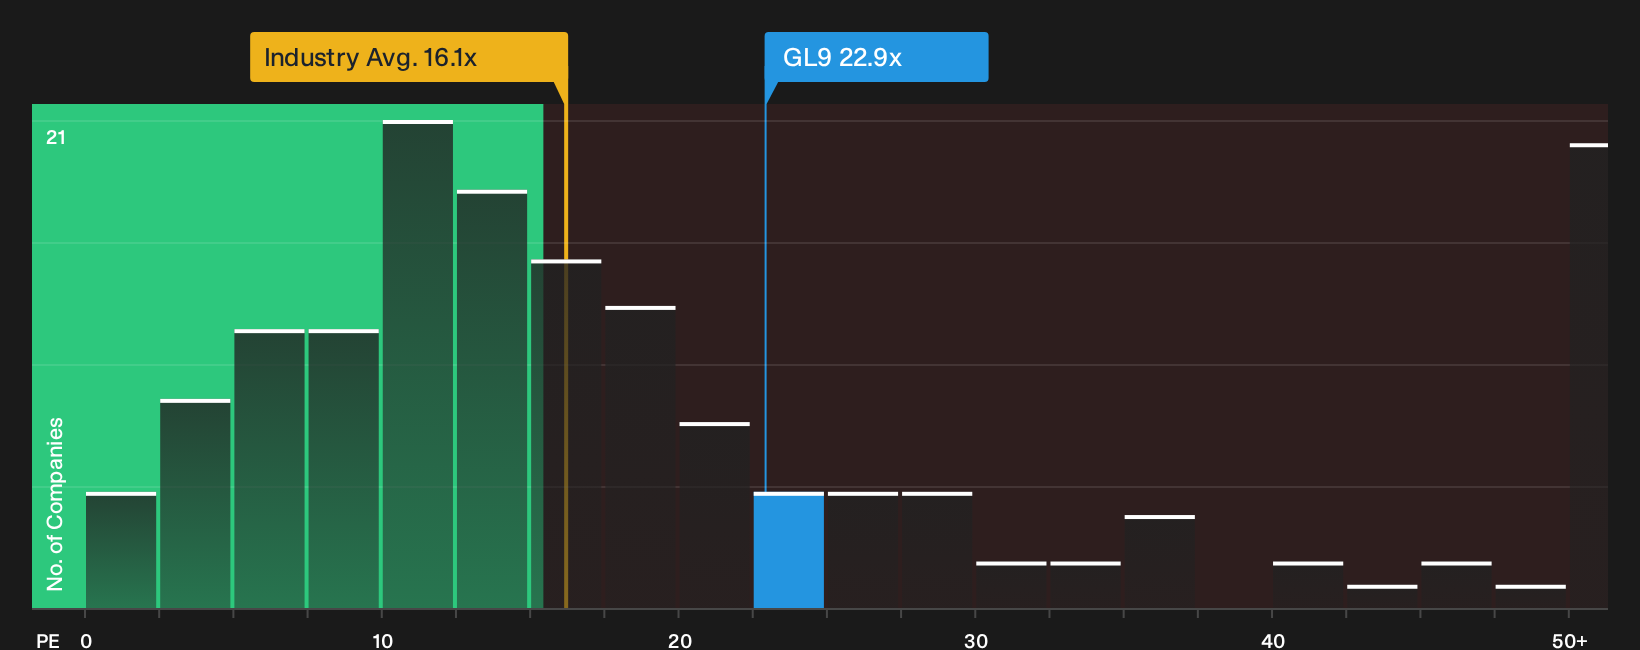
The catch with Glanbia is that the share price looks cheap against one fair value line, yet rich on another. The stock trades on a P/E of 22.9x, compared with a fair ratio of 20.4x, a peer average of 19.4x and a European food sector level of 16.1x. That premium suggests investors are already paying up for quality and growth, which can leave less room for error if forecasts or sentiment cool. So is this a mispriced bargain, or simply a good business on a full earnings multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Glanbia leaves you undecided, move quickly, review the data yourself and weigh both sides of the argument. To help frame that view, take a look at 3 key rewards and 3 important warning signs.
Looking for more Glanbia-sized investment ideas?
If Glanbia has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to explore a broader range of opportunities.
- Target resilient growth by scanning a curated pool of 177 high quality undervalued stocks that combine quality fundamentals with appealing pricing.
- Focus on financial strength and stability by reviewing a list of solid balance sheet and fundamentals (194 results).
- Consider overlooked opportunities by examining a 618 high quality undiscovered gems that the wider market may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com