
Valvoline (VVV) Could Be 38% Undervalued As Strong Guidance Meets A Sharper Pullback
Broyhill Asset Management recently called out Valvoline (VVV) as a top contributor in its second quarter 2026 letter after the auto service provider raised guidance following an 18% quarterly gain and improvements in operating metrics.
That strong second quarter for Valvoline sits against a tougher tape, with the share price down 19.7% over the past month and 28.7% over 90 days, while the 1-year total shareholder return has declined 33.1%. This suggests recent enthusiasm has cooled despite the earlier guidance upgrade.
Spot opportunities beyond Valvoline by scanning a curated set of service and consumer-focused operators through the 16 high quality undiscovered gems.Valvoline just paired stronger guidance and faster store growth with a share price that has given back ground in a hurry. The business looks solid. The bigger question is whether the current quote reflects that strength or not.
Most Popular Narrative: 38% Undervalued
Against Valvoline's last close at $27.13, the most followed narrative pins fair value at $43.60, which implies a wide gap that hinges on how same store sales and margins play out over the next few years.
The consistent growth in same-store sales, driven by both increased transactions and higher ticket sizes from premium service offerings, suggests the company continues to benefit from a durable trend of more vehicles on the road aging and requiring ongoing maintenance. This supports stable and potentially growing revenue and earnings over the long term.
See why 2 investors see Valvoline as 38% undervalued.
Result: Fair Value of $43.60 (UNDERVALUED)
Still, the narrative around Valvoline can crack if electric vehicle adoption shrinks oil change demand faster than expected, or if rising labor and raw material costs squeeze margins.
Find out about the key risks to this Valvoline narrative.
Another View On Valvoline’s Valuation
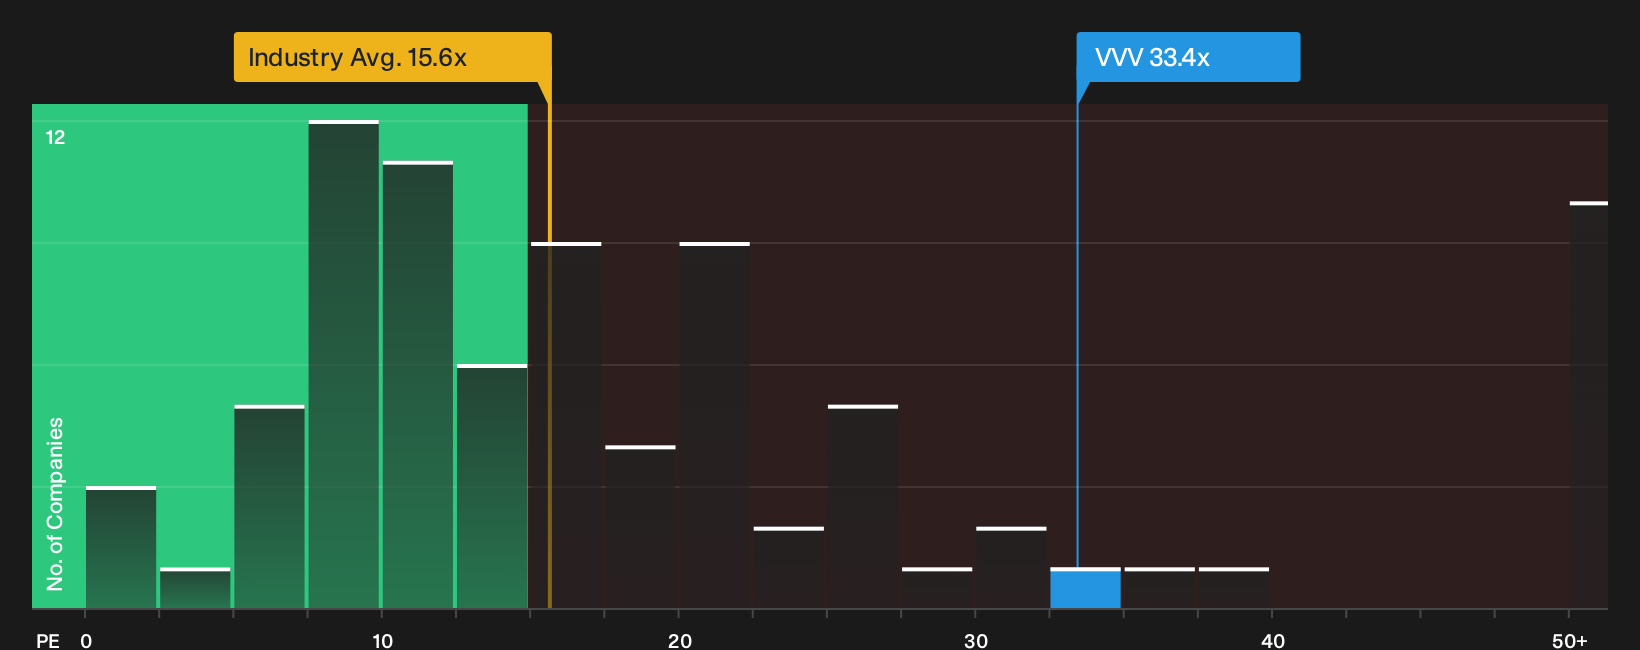
Analysts and narrative followers see upside in Valvoline from a fair value of $43.60 against a $27.13 share price. The P/E picture tells a different story. At 33.4x earnings, the stock trades at more than double the US Specialty Retail average of 15.7x and above peer levels at 12.9x. The fair ratio sits at 37.2x. That leaves a tight margin for error if the future plays out even slightly differently to the bullish script.
For a closer look at how this price compares with earnings power over time, including where the fair ratio could shift next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Valvoline can be confusing, so pull up the underlying numbers, pressure test both sides, and then weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Valvoline?
If Valvoline has sharpened your interest, do not stop here. Use the Simply Wall Street Screener to surface fresh candidates that fit your approach before others spot them.
- Target potential mispricing by scanning a focused set of quality opportunities through the 33 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by filtering for companies on the 11 resilient stocks with low risk scores.
- Lean into financial strength by zeroing in on businesses from the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com