
Is Hydro One (TSX:H) Trading At A Discount On Its Debt Deal And Grid Push?
Hydro One (TSX:H) is back in focus after a US$1.0b debt offering and a regulatory filing for its North Shore Link transmission project, both tied to Ontario's rising electricity demand trends.
The Hydro One share price has eased over the past month, with a 30 day share price return of down 6.85% and a 90 day move of down 9.05%. This comes as the latest financing and project news lands against a backdrop of long term total shareholder returns of 9.19% over one year, 54.09% over three years and 92.27% over five years, suggesting momentum has been built over a longer horizon than the recent pullback implies.
Scan beyond Hydro One and see how other grid and infrastructure players are positioned for electrification trends by reviewing the hand picked 37 power grid technology and infrastructure stocks shaping this theme.
Hydro One looks like a solid regulated utility with long term projects lined up. Yet the recent share pullback raises a simple question: Are you paying a fair price for that stability today?
Most Popular Narrative: 10% Undervalued
At a last close of CA$51.64 versus a most followed fair value estimate of about CA$57.29, Hydro One is framed as trading at a discount, with that gap resting on a specific view of how Ontario's power buildout will feed into regulated earnings and cash flows.
Surging electricity demand in Ontario, projected to grow 70% by 2050, along with government policy accelerating transmission and distribution infrastructure expansion, position Hydro One for sustained, rate base-driven revenue and earnings growth as electrification of transportation and industry advances. The provincial Integrated Energy Plan explicitly prioritizes new transmission and grid modernization projects for Hydro One, enhancing multi-year capital investment visibility and supporting higher regulated asset base, which should boost future allowed revenues and long-term EPS growth.
See why 31 investors see Hydro One as 10% undervalued.
Result: Fair Value of CA$57.29 (UNDERVALUED)
Still, that fair value story can wobble if Hydro One faces higher than expected capital spending needs or if Ontario regulators approve less favourable returns on new projects.
Find out about the key risks to this Hydro One narrative.
Another Angle On Hydro One’s Valuation
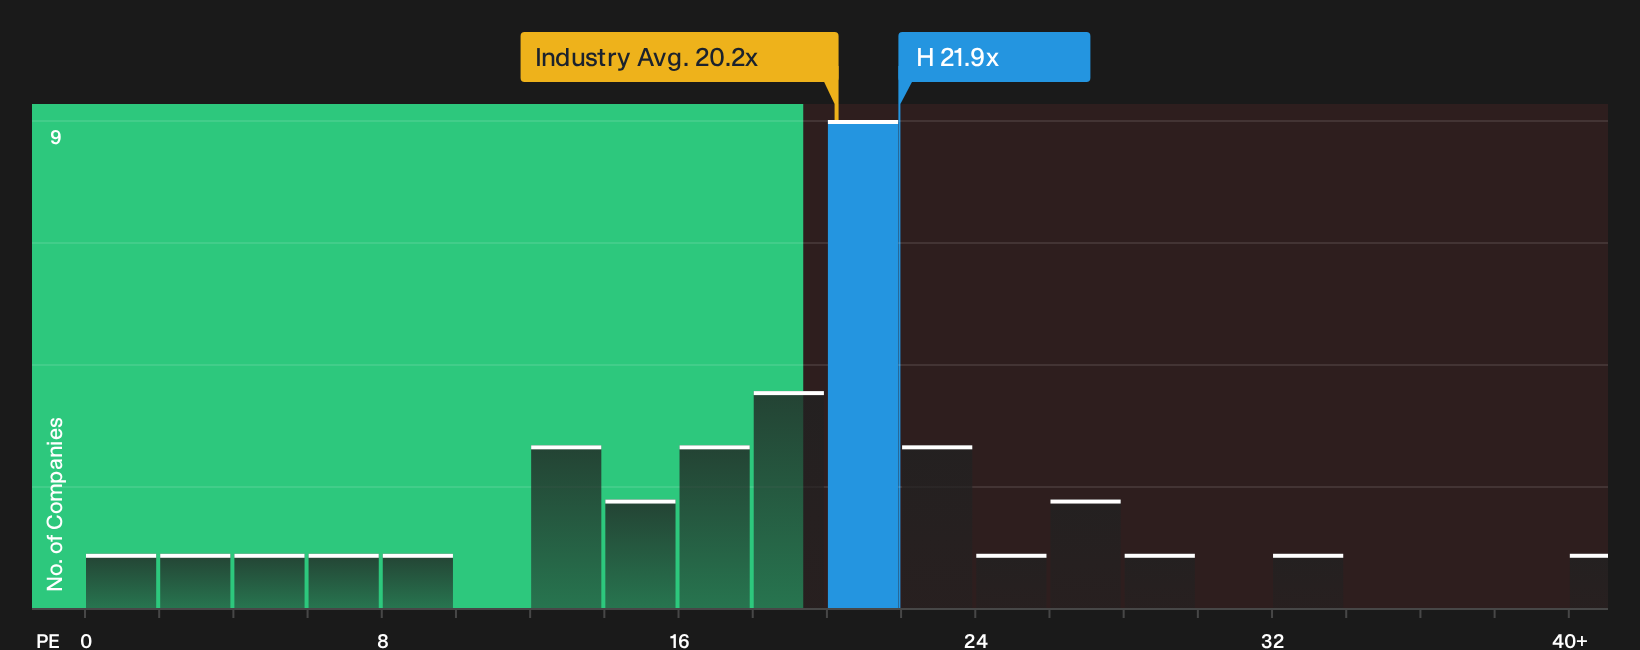
That CA$57.29 fair value relies on long term cash flows, but the market’s simple P/E check tells a different story. Hydro One trades at 21.9x earnings, above both Canadian peers at 20.8x and the wider North American utilities group at 20.1x. However, it is still below a 28.1x fair ratio that the market could move toward. Is this a cushion or a warning signal for you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear story forming around Hydro One today. If you want to move quickly and own your view, weigh both sides of the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hydro One?
If Hydro One sharpens your thesis, do not stop there. Broadening your watchlist today helps you spot opportunities before they feel obvious to everyone else.
- Target resilient balance sheets and sturdy fundamentals by scanning the list of solid balance sheet and fundamentals (6 results) tailored to financially robust businesses.
- Hunt for mispriced quality by reviewing the 4 high quality undervalued stocks that filters for strong companies trading below their implied worth.
- Stack potential income streams by checking the 2 dividend fortresses designed for investors who want higher yield alongside stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com