
3 U.S. Refiners With High Diesel Exposure as Marathon Petroleum Stock Stays in Focus
Diesel at US$6.31 a gallon nationwide and even higher in California is not just a pain at the pump. It reshapes costs for everything that moves by road, rail or ship, and it pulls inflation and interest rate expectations into the spotlight. That kind of pressure can squeeze some U.S. oil refiners while opening the door for others. This article walks through three stocks from our high distillate exposure screener that appear positioned on the right side of that divide.
The stocks covered below are only a small sample of the opportunities that meet this high distillate exposure theme, and the full screen surfaced 18 more U.S. refiners and integrated energy companies with equally compelling narratives that are not discussed here. To identify your own highest conviction plays, head straight to the U.S. Oil Refiners and Integrated Energy Companies with High Distillate Exposure screener.
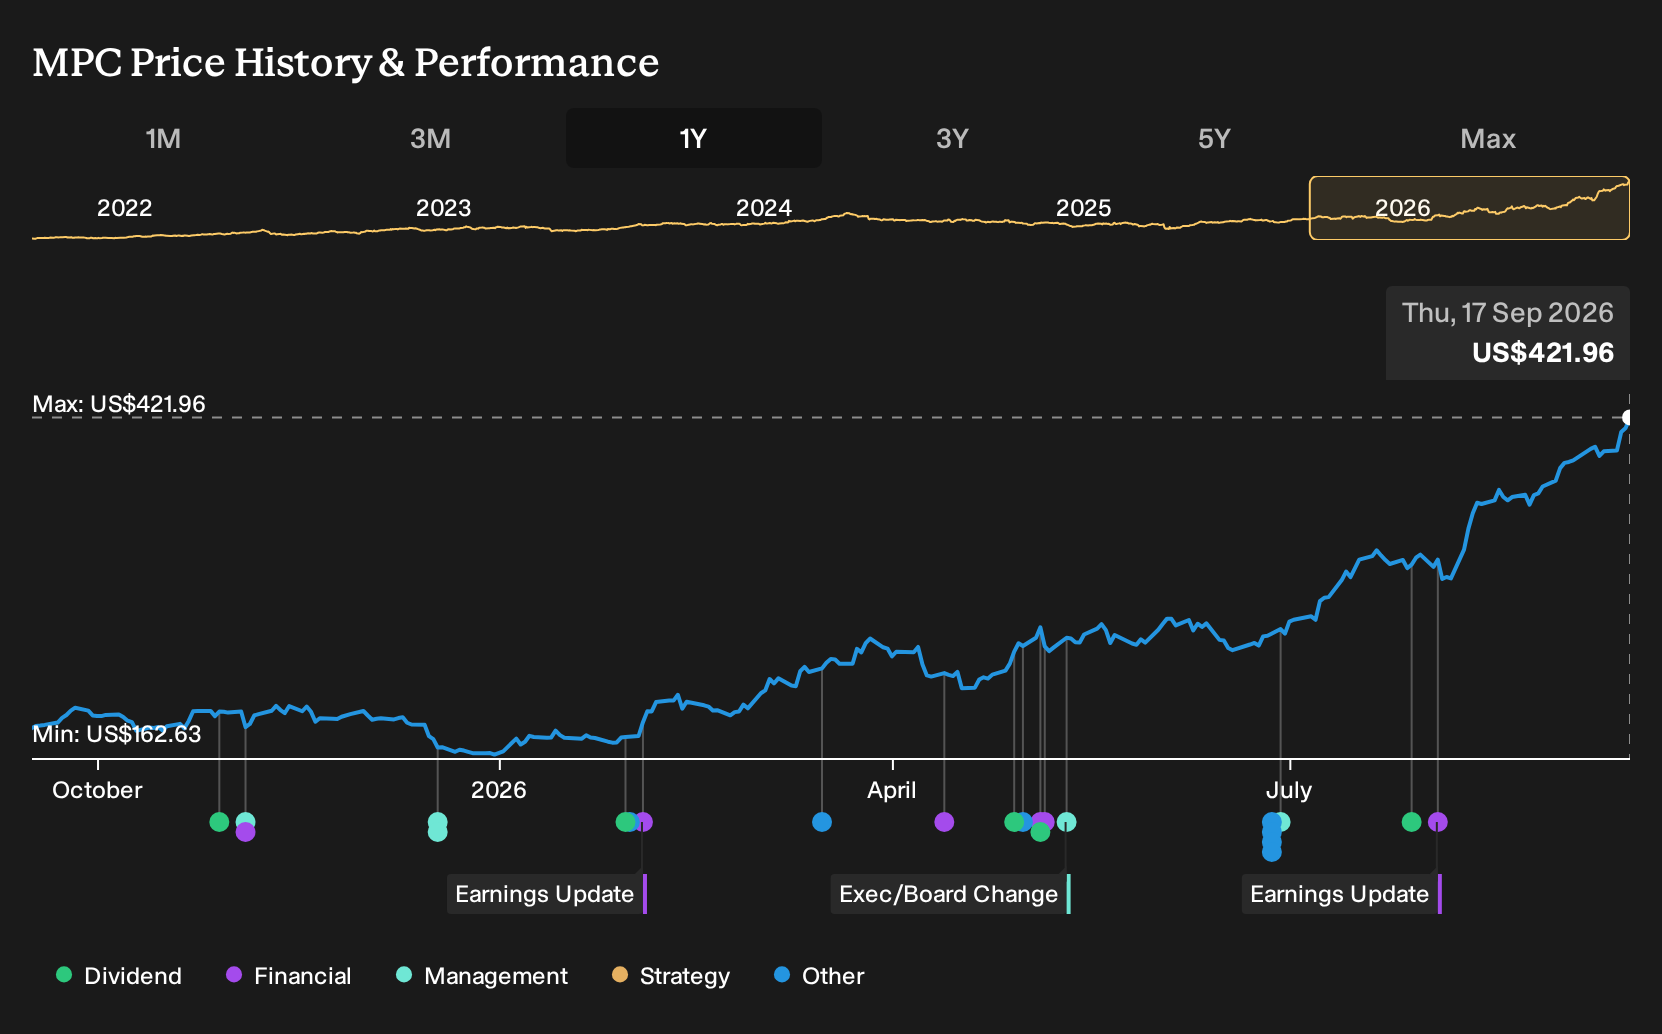
Marathon Petroleum (MPC)
Overview: Marathon Petroleum is a large U.S. refiner and fuel marketer that earns most of its money turning crude oil into diesel and other transportation fuels.
Operations: Marathon Petroleum generates about US$144.6b from Refining & Marketing, US$11.7b from Midstream and US$3.4b from Renewable Diesel, almost entirely in the United States.
Market Cap: US$115.4b
Marathon Petroleum matters for this high distillate exposure theme because its refineries are directly linked to diesel crack spreads, so tight fuel supplies can quickly shift earnings power.
"Structural industry capacity reductions, especially on the U.S. West Coast with peer refinery closures, are causing regional product shortages. Marathon's investments in efficiency, reliability, and emissions reduction at its LA refinery are expected to improve utilization and allow capture of higher margins and revenues in increasingly supply-constrained markets."
The real swing factor is what happens if a single key assumption about refined product tightness and pricing eventually breaks.
If that key assumption matters to you, read the full narrative for Marathon Petroleum to see how crack spreads, capital returns and refining optionality could be decoupling.
Valero Energy (VLO)
Overview: Valero Energy is a large refiner that turns crude oil into diesel, jet fuel and other transportation fuels sold worldwide.
Operations: Valero Energy generates about US$132.2b from Refining, US$6.7b from Renewable Diesel and US$5.0b from Ethanol.
Market Cap: US$114.3b
Valero Energy sits right in the slipstream of today’s diesel squeeze, with a refining system geared to distillates that can swing earnings as crack spreads move.
"The SEC unit optimization project at St. Charles, expected to start up in 2026, is projected to increase the yield of high-value products, potentially boosting future revenues and earnings."
What matters next is how one less visible pressure on distillate margins resolves while those higher value barrels start to flow.
That hidden pressure on margins is exactly why the full full narrative for Valero Energy analyzes how Valero Energy could address today’s squeeze and potentially increase its leverage on distillate cycles.

PBF Energy (PBF)
Overview: PBF Energy is a pure-play refiner and supplier that turns crude oil into diesel, heating oil, gasoline and other fuels.
Operations: PBF Energy generates about US$34.4b from Refining and US$379 million from Logistics, with US$357 million of eliminations.
Market Cap: US$8.9b
PBF Energy is a direct way to tap into diesel and distillate pricing, because its refining system depends heavily on those margins.
"PBF is uniquely positioned to benefit from sustained global demand growth and inadequate capacity additions, as capacity rationalizations and refinery closures accelerate in both North America and Europe, materially tightening global supply-demand and elevating refining margins for years, directly boosting PBF's revenue and profitability."
What really matters for PBF Energy now is how one emerging constraint on future refining capacity shapes the next phase of distillate margins.
As that constraint tightens, read the full narrative for PBF Energy to see how PBF Energy’s refining footprint, balance sheet moves and capital choices could reshape its cycle leverage.

Seeking Fresh Alternatives Beyond Refiners
Fresh opportunities move fast. Some are already building breakout momentum while others are still flying under the radar for now. Before the crowd catches up, act now.
- Spot resilient cash generators early by scanning the list of solid balance sheet and fundamentals (22 results) and focus on businesses with the financial strength to withstand shocks while others are still adjusting.
- Ride the income wave by tracking the 6 dividend fortresses and zero in on companies offering high yields while prices have not fully caught up.
- Get ahead of the next infrastructure cycle by checking the 37 power grid technology and infrastructure stocks and focus on operators positioned to benefit as grid spending ramps up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com