
How New AI Brand Will Impact EXL Stock Investors
- ExlService Holdings marked 20 years as a public company by rolling out its new Go Beyond brand, emphasizing data, AI, domain expertise and execution, following its acquisition of iMerit to deepen AI model training and frontier AI capabilities.
- An interesting shift is that more than 60% of ExlService Holdings revenue is now data and AI led. This aligns the refreshed brand with how the business already operates rather than just where it aspires to go.
- We will look at how ExlService Holdings investment narrative is shaped by the Go Beyond repositioning as a global data and AI leader.
ExlService Holdings Investment Narrative Recap
To hold ExlService Holdings, you need to believe the pivot to being a data and AI partner is durable and monetisable across its core verticals. The Go Beyond brand does not fundamentally change the near term story. It mainly clarifies that more than 60% of revenue already comes from data and AI led work.
The key short term swing factor remains execution on AI heavy deals while managing wage pressure and complex regulation in areas like insurance and healthcare. The main risk is that clients accelerate in house or cloud automation, which could slow new outsourcing commitments even as ExlService upgrades its offering.
The Go Beyond launch is the clearest recent signal that management is aligning the external story with a business that already derives most revenue from data and AI led services. This is backed by the iMerit acquisition for model training and frontier AI work, which in turn supports the existing catalyst around higher margin, analytics driven contracts.
For you, the question is whether ExlService Holdings can keep converting that positioning into steady bookings while absorbing higher talent costs and tight data privacy rules. If growth in regulated sectors or international markets softens, the heavy focus on AI and analytics could magnify both upside and operational risk.
ExlService Holdings is currently anchored on analyst assumptions that its top line reaches US$3.2b and earnings reach US$374.5m by 2029, based on current earnings of US$250.0m. That implies 12.4% yearly revenue growth and an earnings increase of about US$124.5m from today to the 2029 consensus view.
Uncover how ExlService Holdings' fair value indicates a 23% potential upside to its current price before other investors close that gap.
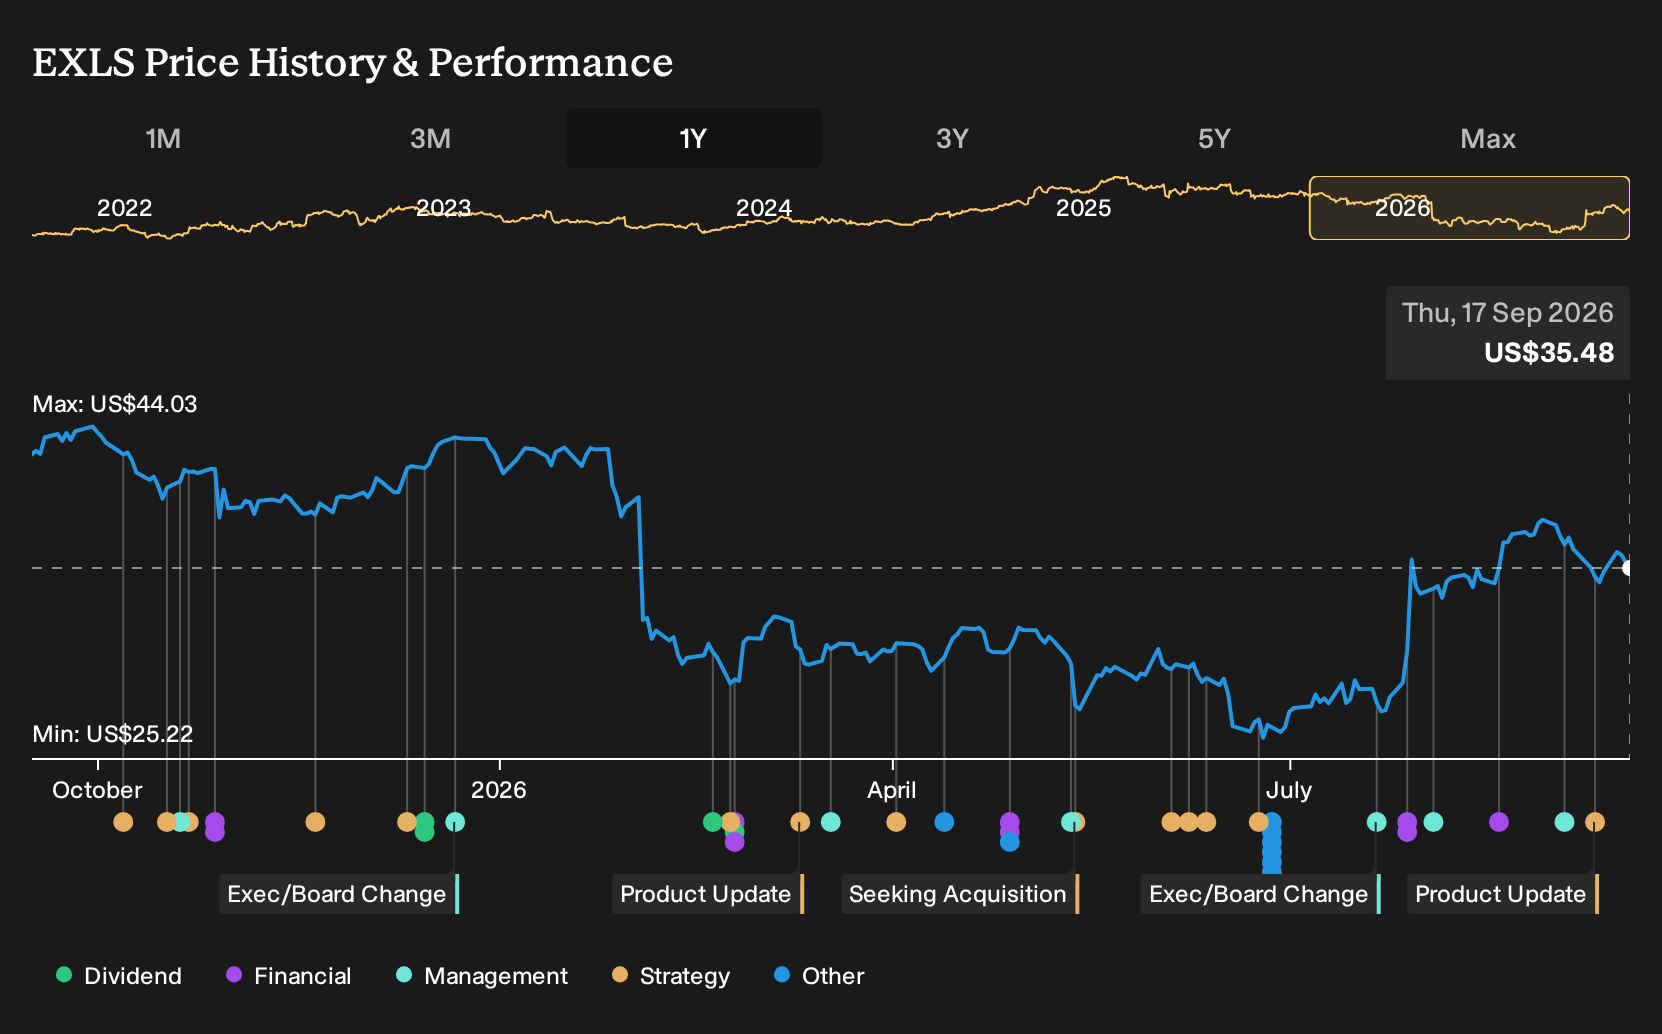
Exploring Other Perspectives
One alternate angle on ExlService Holdings focuses on the bullish catalyst that AI led contracts could support higher earnings than consensus expects. The most optimistic analysts were already pencilling in US$3.3b of revenue and US$397.1m of earnings by 2029 before the Go Beyond launch. That is more upbeat than the baseline US$3.2b and US$374.5m path. You can treat this brand refresh and the iMerit deal as potential story changers and explore which version of the future you find more convincing.
Explore 2 other ExlService Holdings fair value estimates, including one that suggests as much as 131% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ExlService Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ExlService Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ExlService Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond ExlService Holdings?
Once you have a handle on the ExlService Holdings story, it can help to set it beside a few other opportunities so you can judge risk, quality and income potential across a wider watchlist using the Simply Wall St Screener.
- For investors who want potential mispricing on their side, scan a curated set of quality-first ideas through 33 high quality undervalued stocks.
- If capital preservation and steady businesses matter most to you, filter for companies with strong finances using the list of solid balance sheet and fundamentals (22 results).
- When income is a priority, focus on cash return potential with the 6 dividend fortresses and see which payers match your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com