
Asian Growth Leaders With High Insider Ownership September 2026
Amidst a backdrop of geopolitical tensions and fluctuating oil prices, Asian markets have been navigating a complex landscape characterized by inflationary pressures and shifting monetary policies. In this environment, growth companies with high insider ownership can offer unique insights into potential resilience and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's dive into some prime choices out of the screener.
BYD (SEHK:1211)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: BYD Company Limited, along with its subsidiaries, operates in the automobiles and batteries sectors across the People’s Republic of China, Hong Kong, Macau, Taiwan, and internationally with a market cap of approximately HK$835.71 billion.
Operations: BYD's revenue segments include CN¥183.36 billion from Electronics and Other Products, and CN¥624.13 billion from Automobiles and Related Products.
Insider Ownership: 27.6%
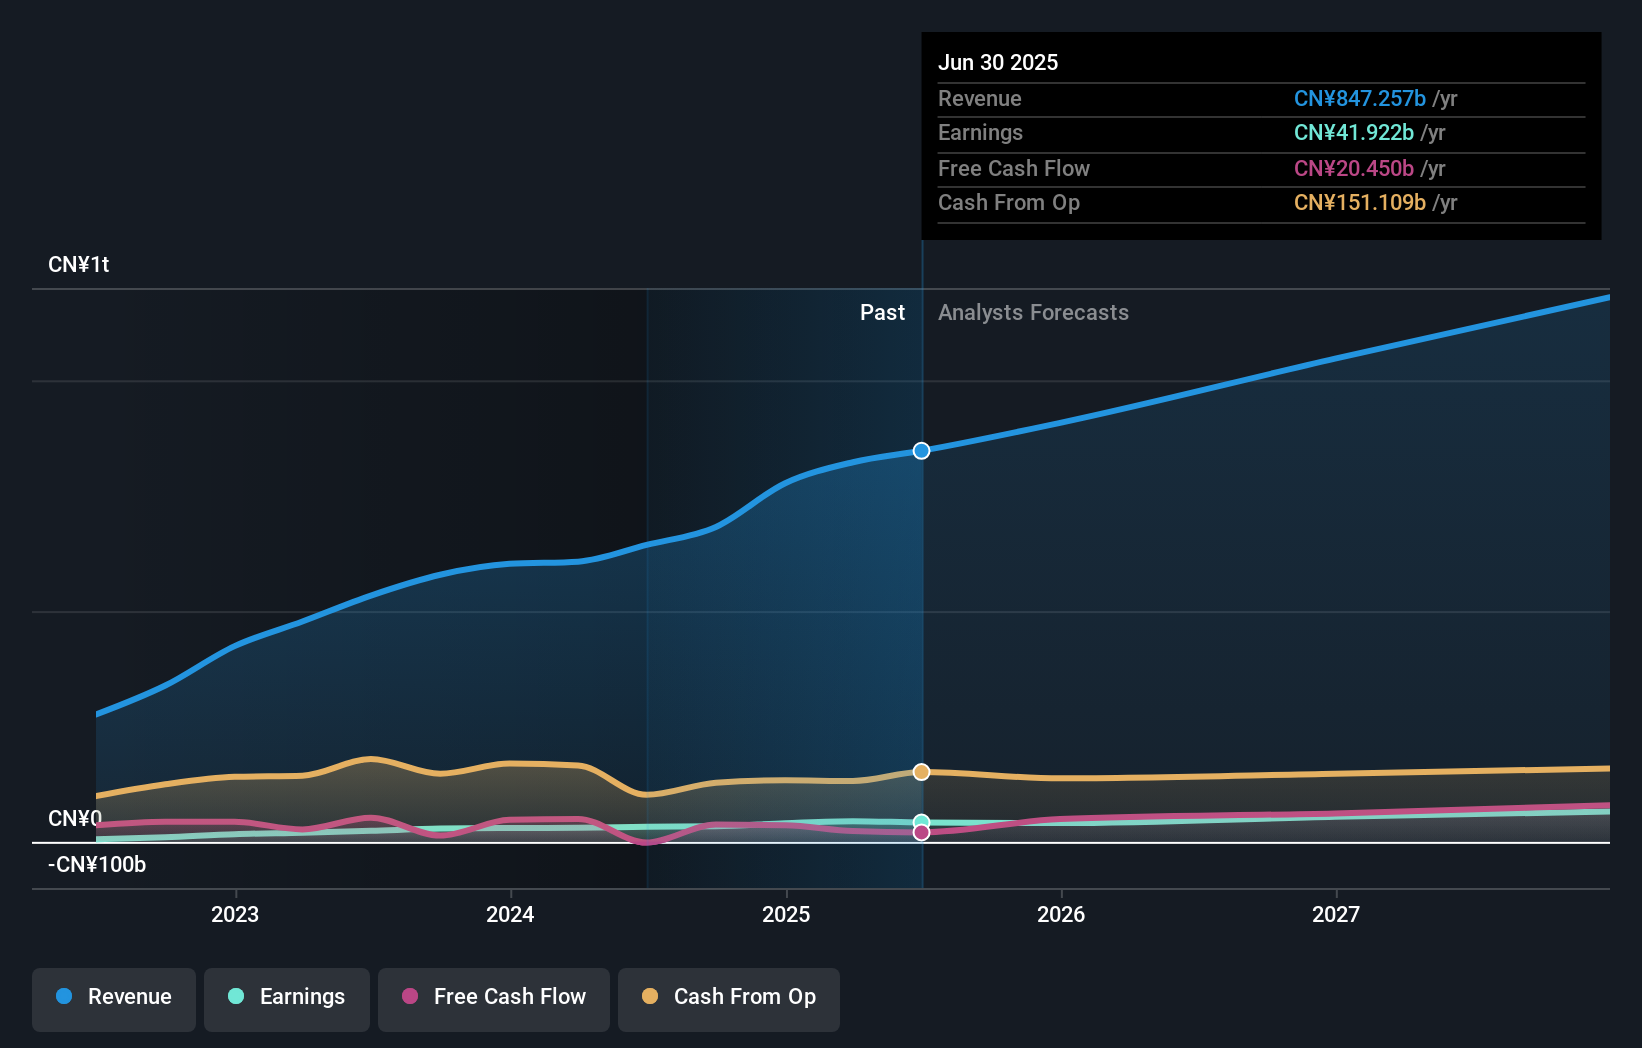
BYD Company Limited, with significant insider ownership, is positioned for robust growth in Asia. Despite a recent dip in sales and net income—CNY 336.10 billion and CNY 12.33 billion respectively for the first half of 2026—the company's earnings are forecast to grow significantly at 21.8% annually over the next three years, outpacing the Hong Kong market average. Recent governance optimizations suggest a focus on long-term strategic alignment and shareholder interests.
- Delve into the full analysis future growth report here for a deeper understanding of BYD.
- Upon reviewing our latest valuation report, BYD's share price might be too pessimistic.
Ningbo Zhenyu Technology (SZSE:300953)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Ningbo Zhenyu Technology Co., Ltd. specializes in the R&D, design, production, and sale of precision progressive stamping dies and downstream precision structural parts both in China and internationally, with a market cap of CN¥23.35 billion.
Operations: The company generates revenue from its Machinery & Industrial Equipment segment, which amounts to CN¥12.08 billion.
Insider Ownership: 37.5%
Ningbo Zhenyu Technology, marked by high insider ownership, shows strong growth potential in Asia. The company reported substantial revenue and net income increases for the first half of 2026, with sales reaching CNY 5.36 billion. Its earnings are forecast to grow significantly at 52.7% annually, surpassing the CN market average. Despite a favorable price-to-earnings ratio of 32.2x compared to the market's 40.5x, its debt coverage remains a concern due to insufficient operating cash flow support.
- Click here to discover the nuances of Ningbo Zhenyu Technology with our detailed analytical future growth report.
- Our comprehensive valuation report raises the possibility that Ningbo Zhenyu Technology is priced lower than what may be justified by its financials.

Guangdong Shenling Environmental Systems (SZSE:301018)
Simply Wall St Growth Rating: ★★★★★★
Overview: Guangdong Shenling Environmental Systems Co., Ltd. operates in the environmental systems industry and has a market capitalization of approximately CN¥38.98 billion.
Operations: Guangdong Shenling Environmental Systems Co., Ltd. generates its revenue from various segments in the environmental systems industry, contributing to its market capitalization of approximately CN¥38.98 billion.
Insider Ownership: 36.7%
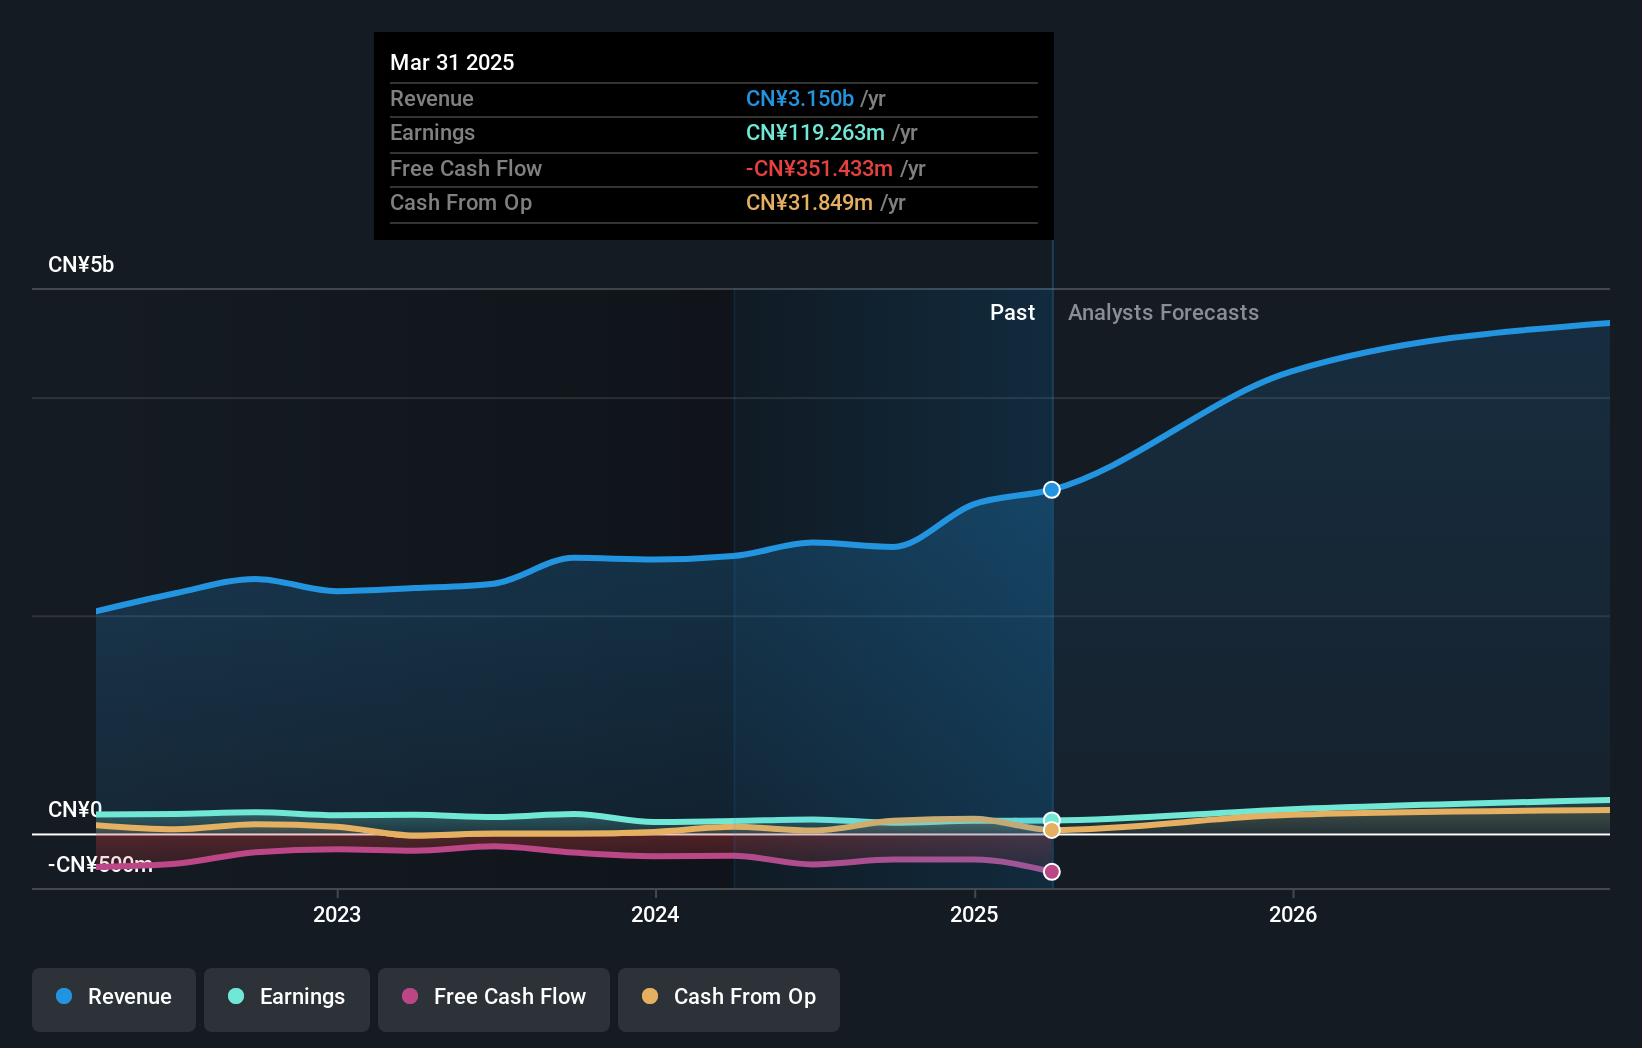
Guangdong Shenling Environmental Systems, with high insider ownership, is poised for robust growth in Asia. Despite a recent dip in net income to CNY 54.05 million for the first half of 2026, revenue increased to CNY 1.76 billion. Earnings are forecasted to grow significantly at 65.43% annually, outpacing the CN market average of 27.2%. However, profit margins have declined and debt coverage by operating cash flow remains inadequate amidst share price volatility.
- Dive into the specifics of Guangdong Shenling Environmental Systems here with our thorough growth forecast report.
- Our expertly prepared valuation report Guangdong Shenling Environmental Systems implies its share price may be too high.
Taking Advantage
- Gain an insight into the universe of 496 Fast Growing Asian Companies With High Insider Ownership by clicking here.
- Want To Explore Some Alternatives? Uncover 27 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com