
Drill Results Might Change The Case For First Majestic Silver Stock
- First Majestic Silver reported positive drill results from its 2026 exploration program at the San Dimas Silver/Gold Mine in Mexico, with around 89,000 metres completed so far and multiple high-grade silver and gold intercepts supporting resource conversion and potential resource additions across several vein systems.
- The identification of new mineralized structures such as the Convencion vein north of Jessica and high-grade hits at El Cristo extends San Dimas' exploration footprint and may influence how investors view the depth of the mine's longer term resource pipeline and production optionality.
- We will now assess how First Majestic Silver's expanded high grade drilling results at San Dimas could influence the broader investment narrative.
First Majestic Silver Investment Narrative Recap
To own First Majestic Silver, you need to believe its heavy investment in exploration and development will keep feeding high quality ore into San Dimas and the wider portfolio rather than just raising costs. The latest drill results point to more potential mineable material around existing infrastructure, which speaks directly to that core belief.
In the short term, the key operational catalyst is whether San Dimas can convert these intercepts into Mineral Resources that support mine plans without pushing unit costs higher. The biggest risk remains elevated spending on drilling and underground development that does not translate into efficient production or offset wider inflation pressures.
The 2026 San Dimas drill update is the most relevant recent announcement for this story. Management has already completed about 89,000 metres of the planned 117,000 metre program, with work split between resource conversion near current workings and step out drilling in areas like El Cristo and Convencion. That mix matters for both near term scheduling and longer term optionality.
For catalysts, the focus is on how quickly intercepts at the Sinaloa Elia complex, Coronado Carmen Escobosa, and the new Convencion structure can be drilled off, modelled, and then reflected in future Mineral Resource estimates. Execution risk sits in the background. Higher exploration intensity at San Dimas and other Mexican assets can pressure cash flow if new zones take longer to prove up or do not deliver the grades implied by early holes.
First Majestic Silver's current analyst storyline points to revenue of $2.1b and earnings of $620.4 million by 2029, based on an assumed 8.7% annual revenue growth rate and an increase in earnings of roughly $272.8 million from $347.6 million today.
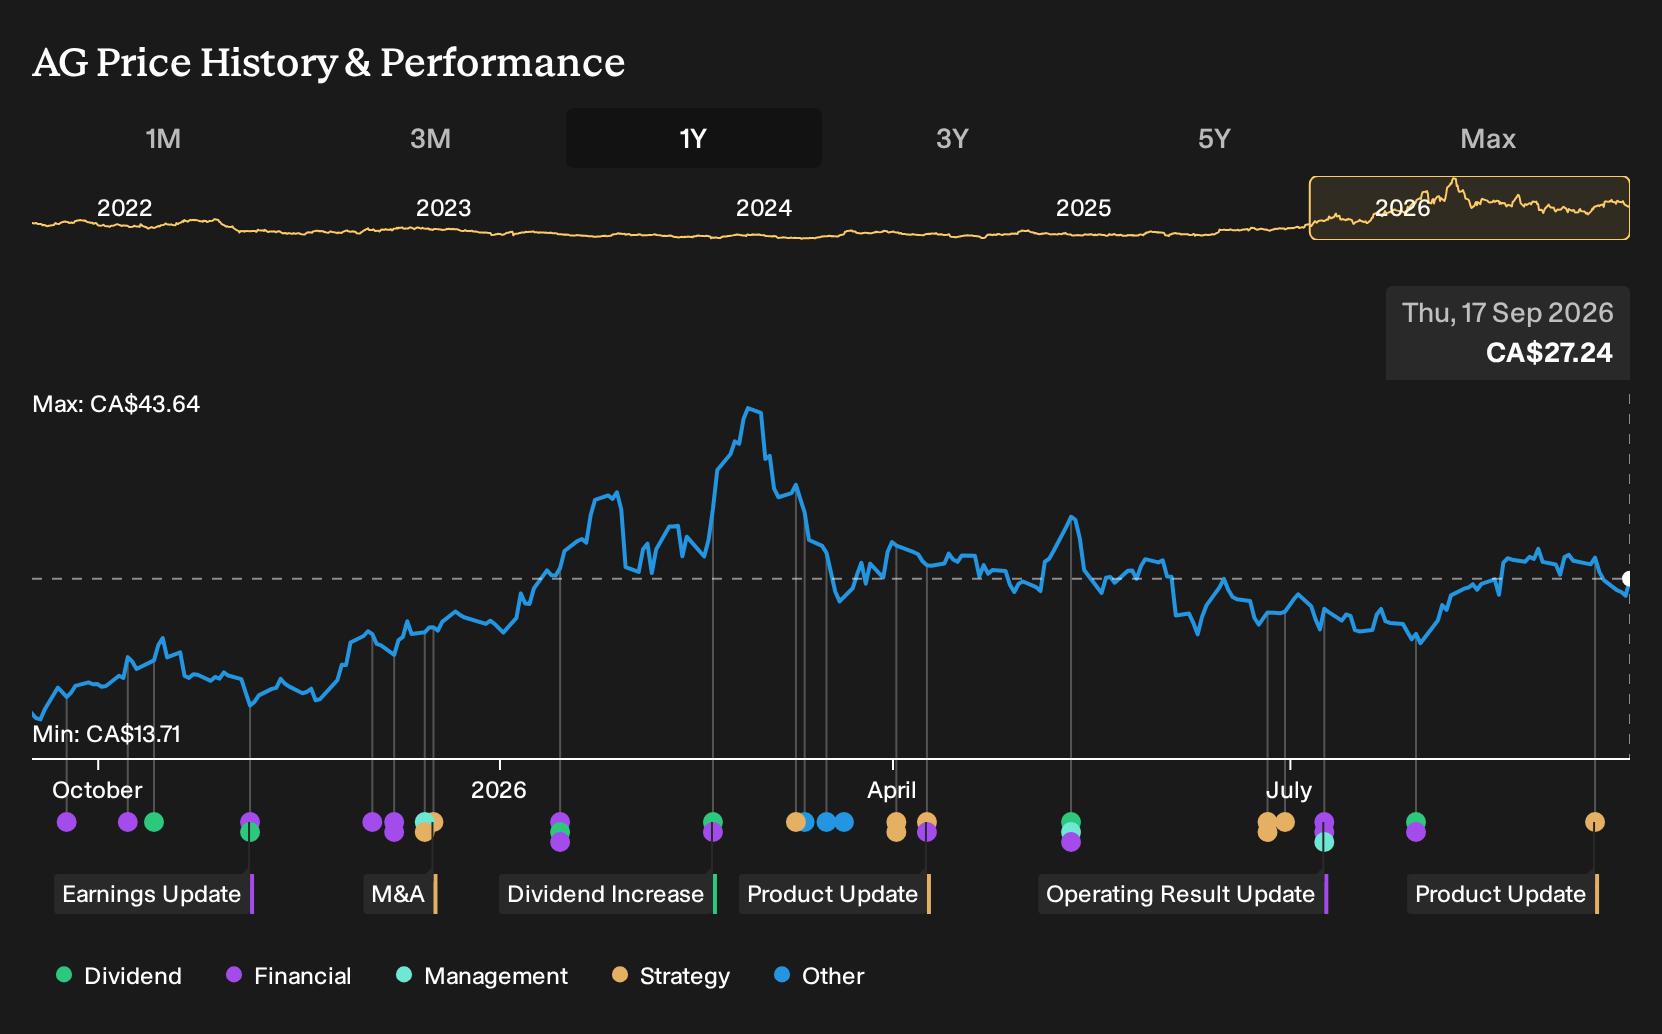
Uncover why First Majestic Silver's fair value signals a 28% potential upside to its current price, a discount that could narrow more quickly than many investors expect.
Exploring Other Perspectives
One alternate view flips the spotlight from San Dimas grades to demand risk. Some of the most cautious yet optimistic analysts still model revenue of about $2.0b and earnings near $554.2 million by 2029, but they worry about long term silver substitution. Those projections came before this drilling news, so your own take may differ.
Explore 5 other First Majestic Silver fair value estimates, including one that suggests as much as 62% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First Majestic Silver research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Majestic Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Majestic Silver's overall financial health at a glance.
Looking for more investment ideas beyond First Majestic Silver?
Once you have a view on First Majestic Silver, it can help to line it up against a wider field of opportunities. The Simply Wall St Screener lets you filter for specific traits so you can build a shortlist that fits your own style rather than relying on headlines.
- If you want potential mispricing on your side, start with companies that combine quality fundamentals with appealing valuations by scanning through the 3 high quality undervalued stocks.
- If capital preservation matters just as much as upside, focus on businesses with stronger balance sheets and resilient metrics by reviewing the list of solid balance sheet and fundamentals (7 results).
- If you are hunting for less crowded opportunities, consider high quality smaller companies that have not yet drawn much attention by checking the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com