
Semtech (SMTC) Stock Looks Overvalued Despite Its 7x Three Year Run
Semtech has seen its stock price move sharply in recent years, and that kind of run always raises a simple question for investors. Is the current share price broadly in line with what the company actually earns today and is expected to earn in the future?
- Over the past 3 years the stock has returned about 7x, which puts more pressure on the earnings story to support where the market now values Semtech.
- Recent product launches around high speed optical connectivity and 10G PON chipsets may support expectations for future profit streams, which matters when you are asking how much to pay for each dollar of earnings.
- Your read on Semtech is one view; the desks covering it have another. See what analysts think Semtech's shares could be worth.
The issue now is whether Semtech's current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you are weighing whether Semtech's sharp move still lines up with its earnings story, it can help to compare it with a wider set of 60 AI infrastructure stocks.
Does Semtech Look Pricey on Earnings?
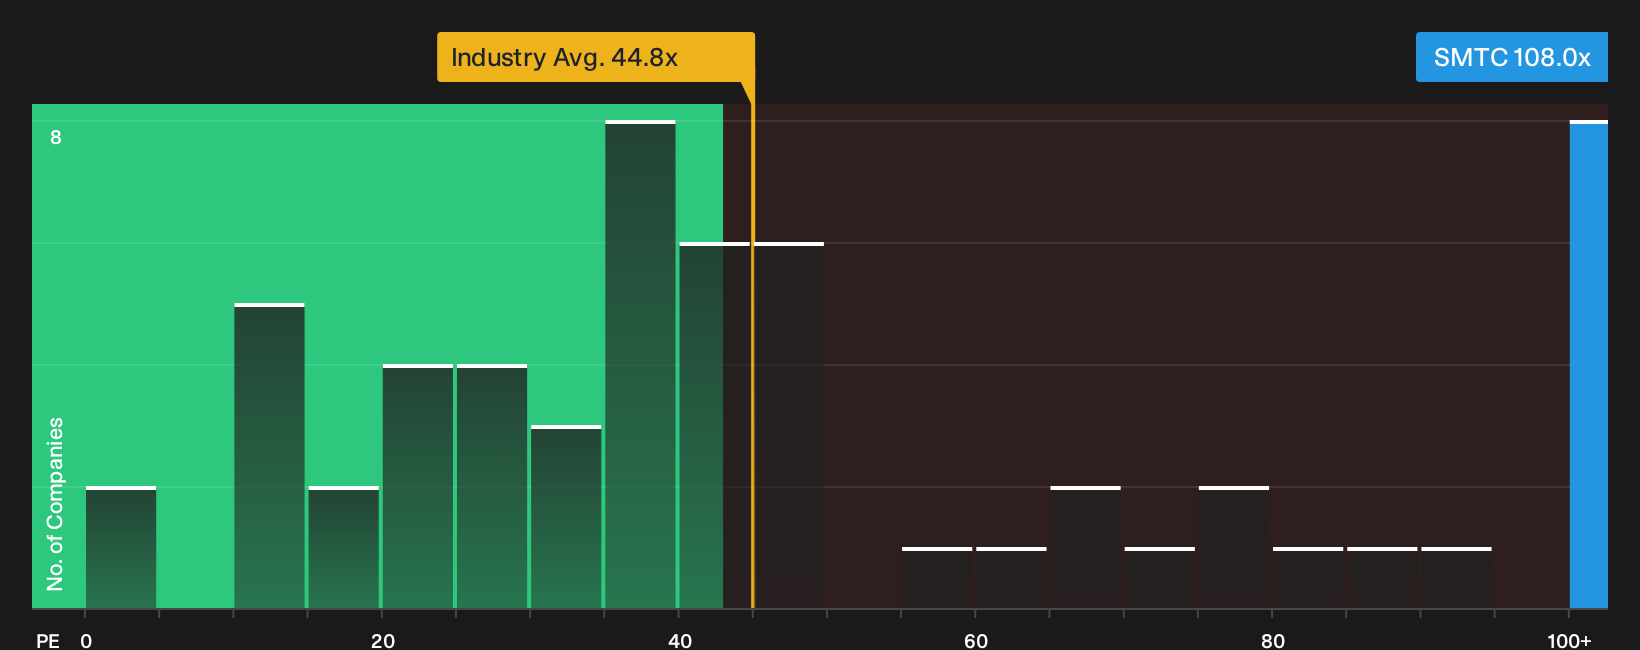
P/E fits Semtech because investors are focused on what the current earnings base implies about the price they are paying for the stock. On this yardstick, Semtech trades on a P/E of 108.0x, which is more than double the broader semiconductor sector average of 44.8x and also well above the peer group on roughly 51.9x. That is a rich headline number for any chip designer, and it tells you the market is attaching a high price tag to each dollar of reported profit.
The Fair Ratio, which blends in factors like Semtech’s margins, growth profile, scale and risk, points to a lower multiple than where the shares currently change hands. As a result, the stock screens as overvalued on this model. Because the recent push into 224G optical connectivity and 10G PON chipsets targets hot areas like AI data centers, investors appear willing to pay a premium even against that tailored benchmark. The key question is whether Semtech’s future earnings can live up to what a triple digit P/E already implies for the business. Explore the numbers behind Semtech's P/E valuation.
The Semtech Narrative: What Would Justify Today's Price?
Narratives on Semtech pick up where this valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or materially less than today’s price on Simply Wall St’s Community page. Each one sets up Semtech’s fair value as a clear thesis about the business that can be tracked over time rather than a single frozen snapshot.
Community views on Semtech are split between those who see meaningful upside still on the table and those who think the optimism has run ahead of itself.
Bull case: 35% undervalued
"Rising AI and cloud data center investment is creating broad demand for high performance, low power optical connectivity, with Semtech’s FiberEdge TIAs, LPO drivers and CopperEdge equalizers positioned to capture more content per port..."
Discover why this Narrative puts Semtech at 35% undervalued.
Bear case: 11% overvalued
"Heavy dependence on hyperscaler AI data center spending leaves Semtech exposed if large customers slow network upgrades, which could weigh on data center net sales and limit earnings growth..."
Explore why this Narrative puts Semtech at 11% overvalued.
One more Semtech check that belongs next to the earnings multiple
Before you stop at the P/E and growth story for Semtech, it is worth asking who is steering the company, how their pay is structured, and whether those incentives truly line up with your interests. See who runs Semtech and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com