
Authenticated Delivery Launch Could Be A Key Test For FedEx Stock
- FedEx launched FedEx Authenticated Delivery, a premium QR code based service for high value and sensitive shipments in the U.S. and Canada that restricts release to authorized recipients and limits delivery changes to protect security.
- The focus on digital proof of delivery and fraud reduction positions FedEx to deepen relationships in security critical segments such as luxury, healthcare, aerospace, and electronics, where shipping reliability directly affects customer trust and switching costs.
- We will now look at how FedEx's investment narrative could be influenced by this new QR authenticated premium delivery offering.
FedEx Investment Narrative Recap
For a shareholder in FedEx, the core belief is that cost programs like DRIVE, Network 2.0 and Tricolor can keep offsetting pressure from weaker industrial B2B demand, pricing strain in international markets and restructuring noise around Freight. In the short term, the main swing factor is how well FedEx holds yields and volumes as customers shift toward lower priced services.
FedEx Authenticated Delivery looks incremental rather than transformational in the near term. It supports the same thesis as Global Trade Navigator and other digital tools, which center on more secure, data rich shipping and better asset use. The biggest current risk remains contract exposure, weather disruption and execution on Freight separation, not this product launch.
Global Trade Navigator is the clearest companion to FedEx Authenticated Delivery right now. One product tightens identity and drop off security for high value parcels in the U.S. and Canada. The other aims to reduce customs headaches and unplanned costs for shippers that move goods across borders and to plug FedEx logic into their own systems.
Viewed together, these rollouts speak directly to the same operational levers that matter most for the stock today, including revenue quality, mix and network efficiency. Better shipment data, earlier trade intelligence and restricted delivery changes may help reduce misdeliveries and clearance issues. The key watchpoint remains execution, especially while industrial demand, pricing pressure and Freight restructuring are already testing the organization.
How FedEx Authenticated Delivery Fits Into The Numbers
FedEx's narrative projects US$97.6b revenue and US$5.5b earnings by 2029. This implies 1.0% yearly revenue growth and an earnings increase of about US$1.1b from US$4.4b today.
Uncover why FedEx's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
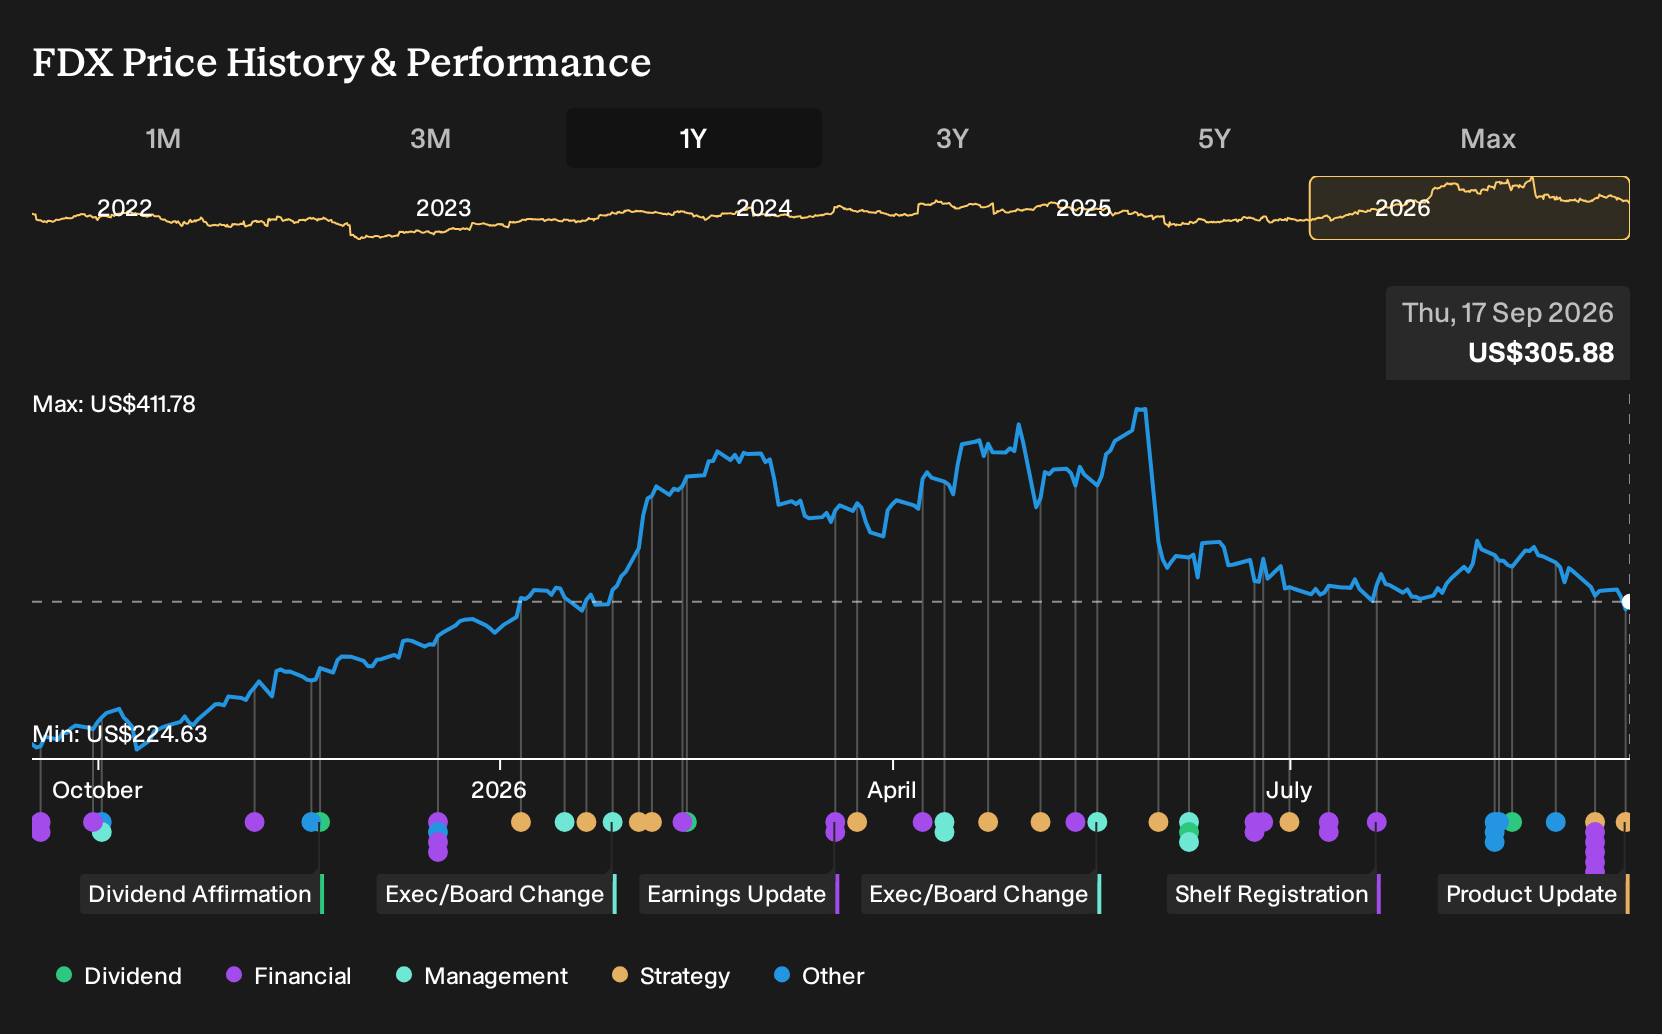
Exploring Other Perspectives
Some of the most optimistic analysts already worked with a much stronger FedEx story, expecting revenue to reach about US$109.5b and earnings of roughly US$7.0b by 2029. That view leans heavily on premium e-commerce and healthcare demand. You can now ask whether QR authenticated delivery strengthens that bullish case or forces a rethink.
Explore 3 other FedEx fair value estimates, including one that suggests as much as 71% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your FedEx research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for FedEx. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FedEx's overall financial health at a glance.
Looking For More Investment Ideas Beyond FedEx?
FedEx might be the focus today, but your portfolio probably needs more than one logistics heavyweight. Use the Simply Wall St Screener to line up other stocks that match your preferred mix of quality, risk and income, then compare them with what FedEx offers.
- If resilience matters most to you, start with a 11 resilient stocks with low risk scores that have historically paired steadier fundamentals with lower risk scores.
- If income is your priority, check out a hand picked set of 6 dividend fortresses that may appeal to dividend focused investors.
- If you want potential future leaders before they are widely followed, scan through 16 high quality undiscovered gems and see which stories you want to research next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com