
Is AGNC Investment (AGNC) Undervalued After Its Latest Dividend Declarations?
AGNC Investment (AGNC) has given income focused investors fresh information to consider after declaring third quarter 2026 dividends on multiple preferred stock series, alongside a September cash payout on its common shares.
Recent trading has been choppy for AGNC Investment, with the share price down 9.3% year to date and 9.3% over the past month, even as the latest preferred and common dividend declarations, along with upcoming inclusion in the S&P MidCap 400, have kept the story in focus. Despite this softer price momentum around the current US$9.91 level, the 1 year total shareholder return of 12.4% and 3 year total shareholder return of 57.4% highlight how income and reinvested payouts have driven a much stronger long run outcome than the share price alone suggests.
Scan beyond AGNC Investment and stress test your income ideas against our hand picked 6 dividend fortresses for comparison.
Bulls point to AGNC Investment’s income record and index upgrade, while bears focus on choppy trading and declining revenue and net income. Which case does the current valuation appear to support?
Price-to-Earnings of 5.6x: Is it justified for AGNC Investment?
AGNC Investment trades on a P/E of 5.6x, which is low compared to both peers and the wider Mortgage REITs group, given the last close of $9.91 and the implied discount to fair value.
The P/E ratio compares the share price with earnings per share and effectively shows how many dollars investors are paying for each dollar of profit. For mortgage focused REITs like AGNC Investment, earnings can be volatile, so a compressed multiple can signal caution around future earnings power as much as it reflects past results.
Recent numbers show high quality earnings and very strong profit growth over the past year, alongside an estimated fair P/E of 10x. That suggests the current 5.6x level prices AGNC Investment at a steep discount to where the market could move if earnings prove more durable than expected, although forecasts pointing to declining revenue and earnings indicate that investors are not giving full credit to recent profit strength.
Against the US Mortgage REITs industry average P/E of 8.4x and a peer average of 13.6x, the 5.6x multiple looks materially cheaper, which reinforces the picture of a stock the market is valuing below both sector and fair ratio benchmarks.
Explore the SWS fair ratio for AGNC Investment.
Result: Price-to-Earnings of 5.6x (UNDERVALUED)
Still, declining annual revenue and net income growth, along with choppy recent returns, could pressure confidence in AGNC Investment if those trends deepen or persist.
Find out about the key risks to this AGNC Investment narrative.
Another View on AGNC Investment’s Value
The earlier P/E workup presented AGNC Investment as inexpensive. The SWS DCF model points in the same direction, with the shares at $9.91 compared with an estimated future cash flow value of $14.43. This implies AGNC trades at a wide discount that income-focused investors may want to examine further.
Look into how the SWS DCF model arrives at its fair value.
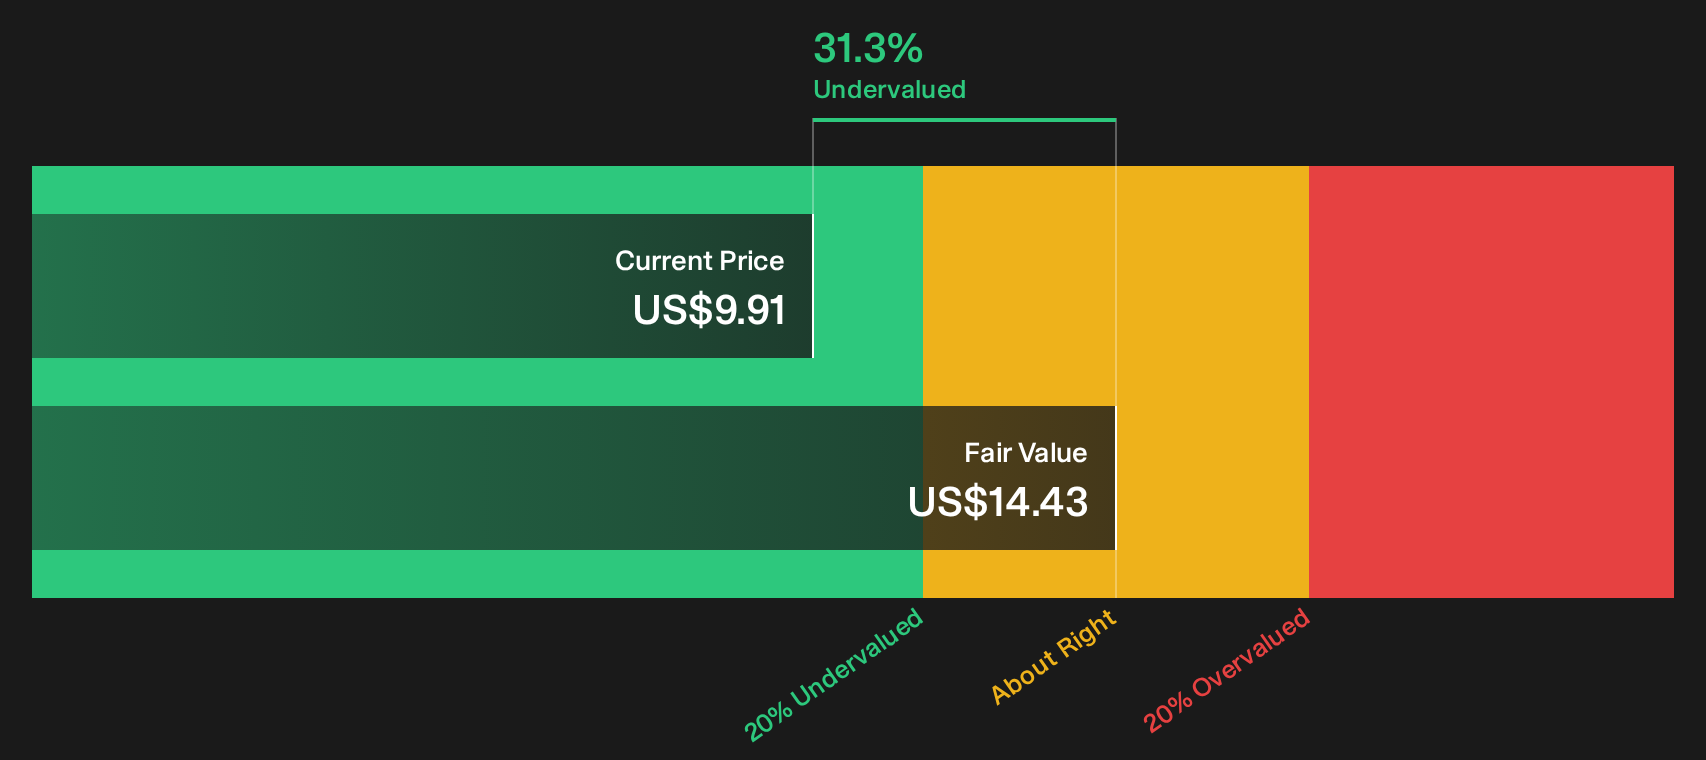
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AGNC Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on AGNC Investment so far. If you want to move quickly and ground your view in the underlying data, consider the 3 key rewards and 3 important warning signs.
Want more ideas beyond AGNC Investment?
If AGNC Investment has sharpened your thinking on income and value, do not stop here. The strongest portfolios usually start with a wider opportunity set.
- Target reliable income streams by reviewing companies in the 6 dividend fortresses that combine higher yields with resilient payout profiles.
- Hunt for potential mispriced opportunities through the 29 high quality undervalued stocks and see which businesses trade below their assessed worth.
- Prioritise capital protection first by checking out the 11 resilient stocks with low risk scores and focus on businesses with sturdier financial risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com