
Does Earnings Miss Change The Bull Case For Whirlpool (WHR)?
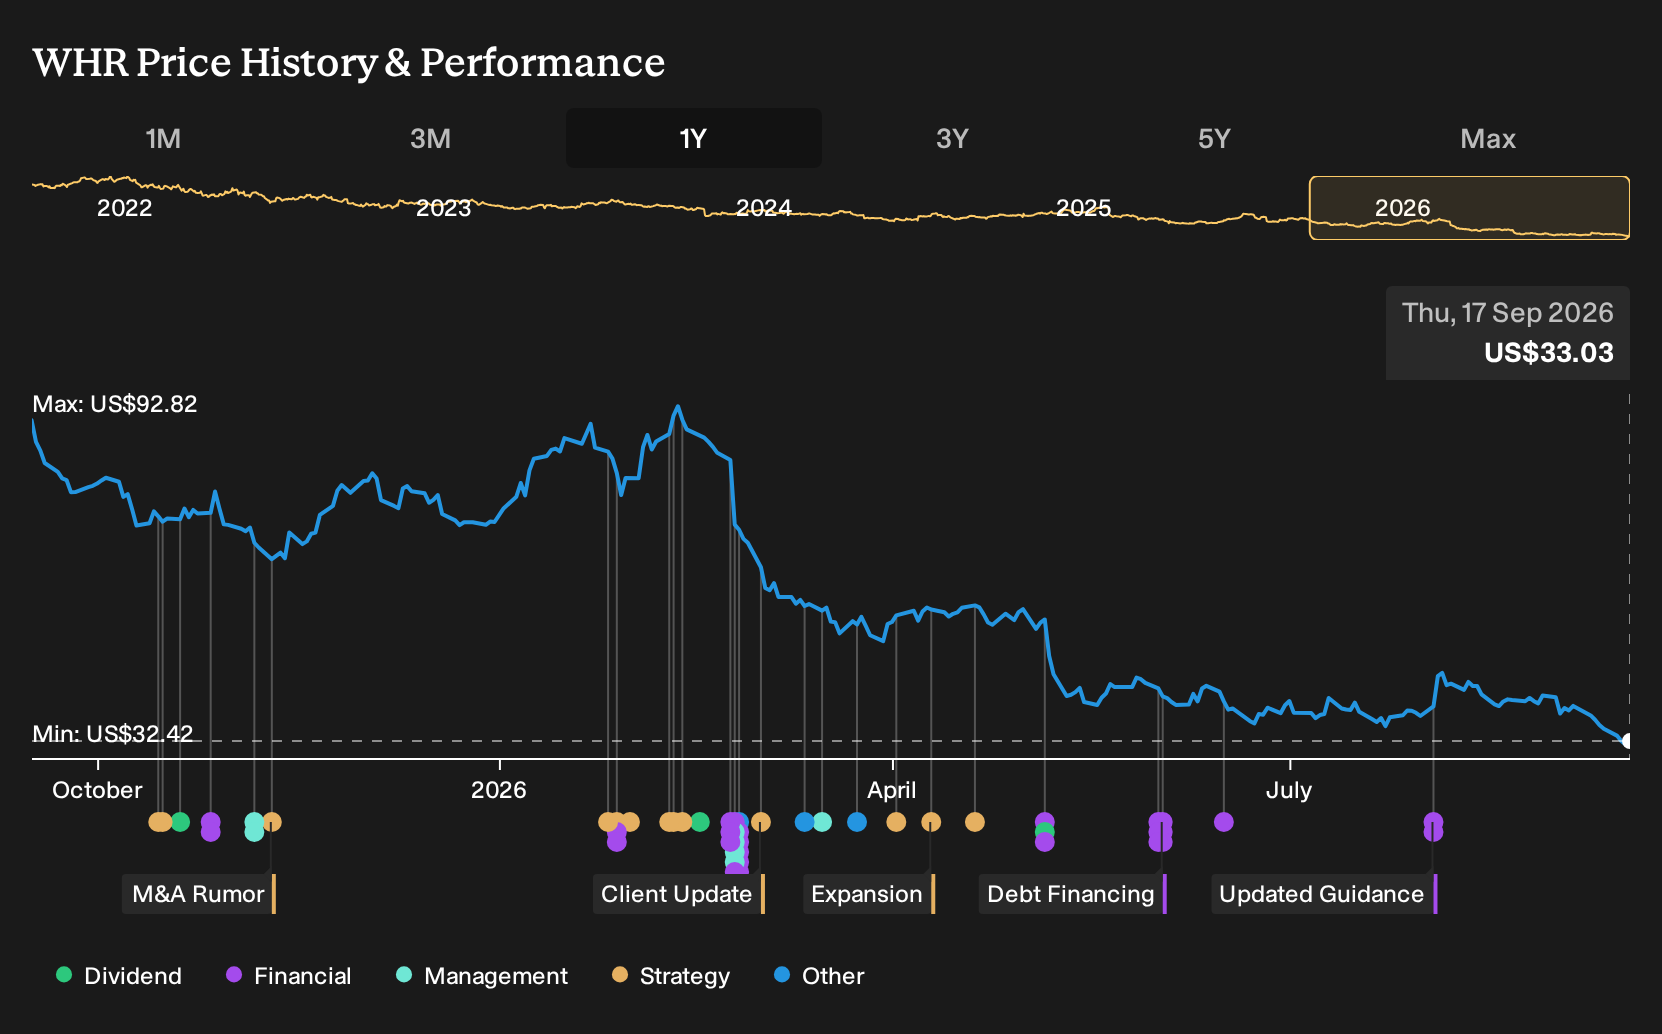
- Whirlpool's latest quarterly update showed net sales down 6.8% year on year, a miss on both revenue and EPS estimates, and a loss per diluted share, while management kept full year earnings guidance and highlighted completed refinancing that pushes major debt maturities out to 2028.
- Under the KitchenAid brand, Whirlpool is leaning on premium product launches such as the 2026 Design Series Luminaire stand mixer and expanded Design Series cookware and ranges, even as Latin America margin pressure and weaker quarterly profitability expose how dependent the group remains on pricing moves and mix to support results.
- We will now look at how Whirlpool's investment narrative is affected by the Q2 earnings miss and reaffirmed full year outlook.
Scan beyond Whirlpool to see how other household-focused businesses with steadier trajectories line up in our curated group of 11 resilient stocks with low risk scores.
Whirlpool Investment Narrative Recap
To stay in Whirlpool after this kind of quarter, you need to believe the appliance maker can convert its heavy product pipeline and cost actions into steadier earnings, even while headline sales stay under pressure. The Q2 miss and loss per share keep the near term narrative focused on execution rather than expansion.
The reaffirmed full year outlook and refinancing that clears big debt maturities until 2028 keep the main short term catalyst intact. That catalyst is proving that pricing, mix and cost cuts can support margins through a slow demand patch. The biggest risk remains margin pressure in Latin America and wider competitive discounting eroding that thesis.
The KitchenAid Design Series Luminaire launch and broader premium range push matter here because they show Whirlpool leaning into higher ticket, design led products rather than chasing volume at the low end. For an investor, the key question is whether this tilt toward premium can offset weaker demand in more price sensitive categories.
If these KitchenAid launches gain traction, they could support mix and help EBIT margins in regions where pricing power is strongest, even as Latin America faces currency and demand headwinds. If uptake disappoints or competitors respond aggressively on features and promotions, that would blunt one of Whirlpool's clearest product led catalysts.
Whirlpool's current analyst narrative points to revenue of $16.3b and earnings of $277.9m by 2029. That profile assumes 3.0% yearly revenue growth and an earnings increase of about $107.9m from $170.0m today.
Uncover how Whirlpool's fair value indicates a 56% potential upside to its current price, which could narrow quickly if Whirlpool executes on this earnings path.
Exploring Other Perspectives
One alternate story around Whirlpool leans heavily on regulation risk. The most cautious analysts were already baking in earnings of about $218.7m by 2029 on the same $16.3b revenue assumption before this Q2 miss and KitchenAid Luminaire launch. That is a much lower profit path. It shows just how far opinions can spread, so explore several viewpoints before deciding what this latest quarter means for you.
Explore 3 other Whirlpool fair value estimates, including one that suggests it could be worth just $50.67!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Whirlpool research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Whirlpool. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Whirlpool's overall financial health at a glance.
Looking for more investment ideas beyond Whirlpool?
Once you have a view on Whirlpool, it can help to widen the lens and compare it with other companies that fit different risk and income profiles. The Simply Wall St Screener is built for that kind of side by side work so you can pressure test your thesis against a broader watchlist.
- If you want stability to anchor a portfolio, start with a 11 resilient stocks with low risk scores that aim to keep volatility in check while still giving you equity exposure.
- For investors hunting for value, focus on businesses trading below what their fundamentals might justify and see where the numbers point across a 29 high quality undervalued stocks.
- Income focused holders can line up cash flow ideas by screening for companies aiming to provide robust payouts with a 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com