
Learn Why The Bull Case For DPM Metals (TSX:DPM) Could Change Following Expanded Drill Program
- DPM Metals reported drilling results from the Dumitru Potok and Rakita North copper gold silver prospects on the Coka Rakita licence, extending skarn mineralization in several directions and expanding the 2026 drilling program to about 32,000 to 35,000 metres.
- The decision to increase drilling by an additional 12,000 to 15,000 metres, ahead of a planned 2027 resource update and Preliminary Economic Assessment, indicates a focus on defining potential resource scale and project economics rather than simply maintaining current exploration activity.
- This article examines how DPM Metals' investment narrative is influenced by the extensive Coka Rakita drill results and the expanded exploration plans.
DPM Metals Investment Narrative Recap
To own DPM Metals, you need to believe the Coka Rakita and broader Balkan portfolio can offset future production pressure from assets like Ada Tepe and any timing risk at Loma Larga. The latest drill results and larger 2026 drill plan support that Coka Rakita remains a core operational focus, but they do not change the near term production gap risk.
The key short term catalyst is still resource and study progress at Coka Rakita ahead of the 2027 resource update and Preliminary Economic Assessment. Rising labor and exploration spending, along with prior shareholder dilution, remain important watchpoints as the program scales up and as management balances growth projects with cost control and capital allocation.
The fresh drilling update on Dumitru Potok and Rakita North is the most relevant announcement for investors focused on catalysts. It ties directly into the goal of refining the Coka Rakita Mineral Resource, which underpins expectations for future high margin production alongside Chelopech and the rest of DPM Metals’ portfolio.
For investors, the key operational question is whether this expanded 32,000 to 35,000 metre 2026 program can keep the Coka Rakita timeline on track while containing cost pressure. Execution on this drilling plan, and how it feeds into the 2027 resource and PEA work, will sit alongside any future decisions on Ada Tepe and Loma Larga as key drivers of sentiment.
DPM Metals' narrative projects $1.3b revenue and $766.2 million earnings by 2029. This implies fairly flat yearly revenue growth and an earnings increase of about $116.9 million from $649.3 million today.
Uncover how DPM Metals' fair value indicates a 7% potential upside to its current price, which could narrow quickly as sentiment shifts.
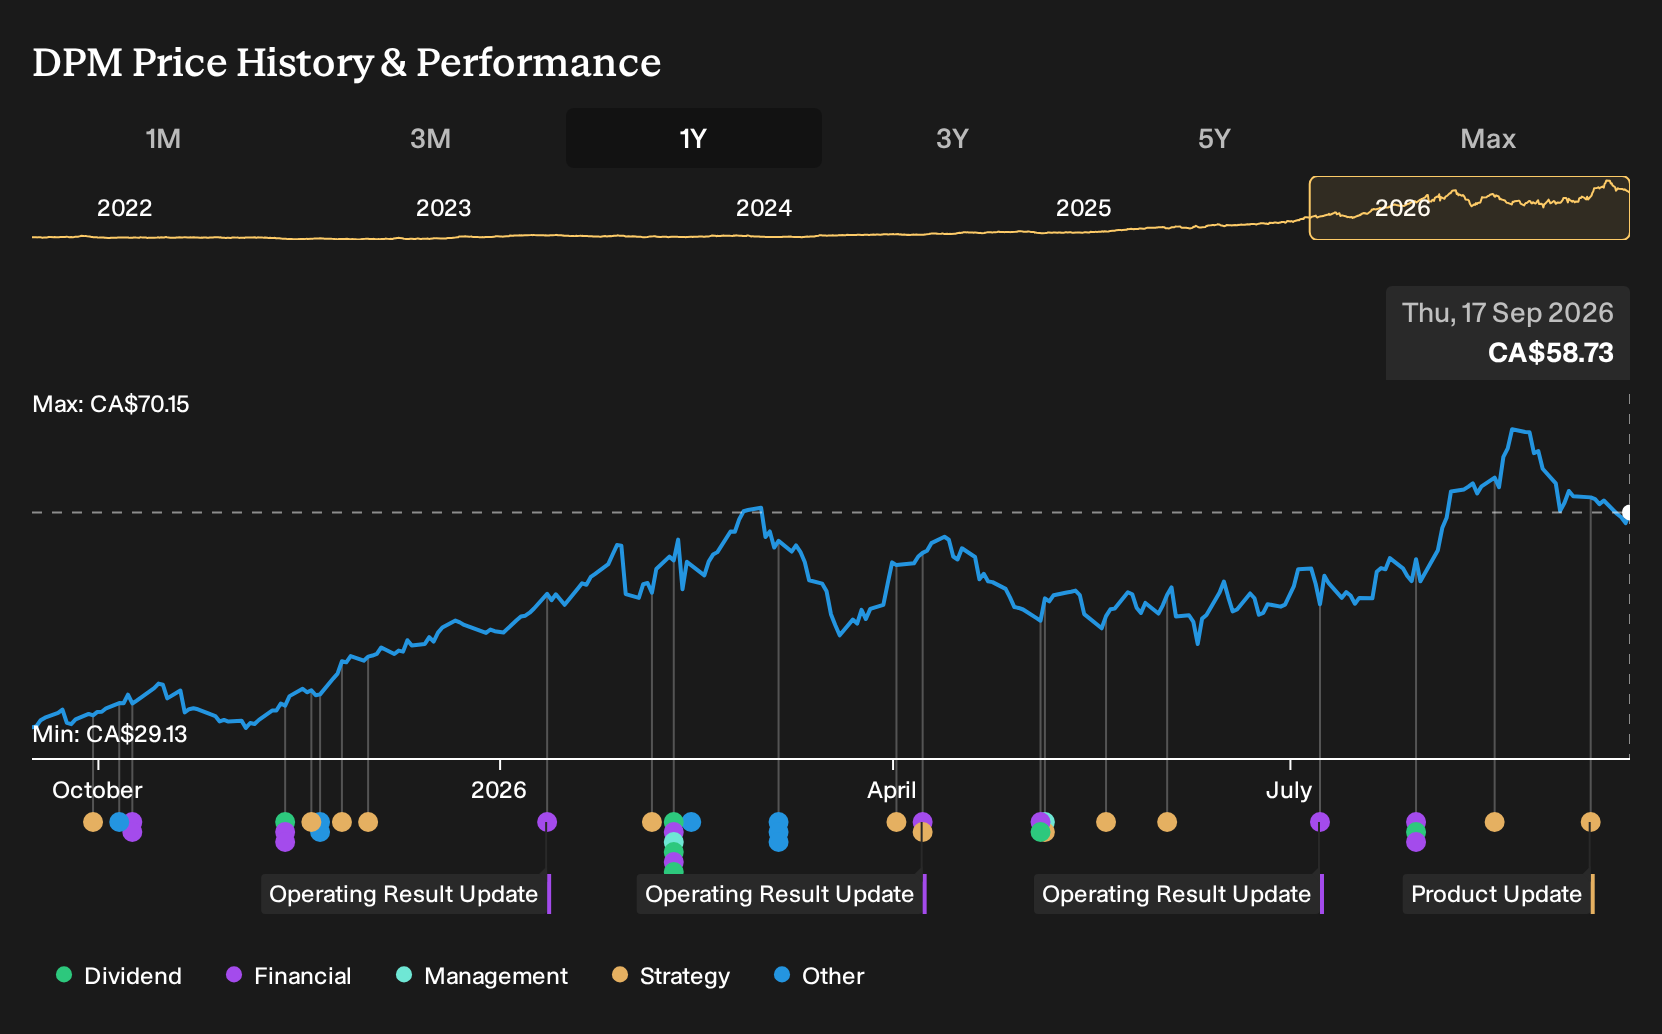
Exploring Other Perspectives
Some analysts already had a far more optimistic read on DPM Metals before this Coka Rakita drilling update. The most bullish group were modelling about $1.5b of revenue and roughly $960.7 million of earnings by 2029, compared with $1.3b and $766.2 million in the broader consensus. You should expect those pre news projections to be revisited as fresh drill data and conference commentary land. Treat this as a moment to compare different narratives rather than assume one is right.
Explore 3 other DPM Metals fair value estimates, including one that suggests as much as 548% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DPM Metals research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DPM Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DPM Metals' overall financial health at a glance.
Looking for more DPM Metals style investment ideas?
Once you have a handle on where DPM Metals might fit in your portfolio, it can help to widen the lens and scan for other companies with balance sheets, cash flows, and return profiles that match your own risk and income goals.
- If you want resilient businesses that aim to keep downside in check, start by filtering for 1 resilient stocks with low risk scores that can help anchor a more volatile portfolio.
- For investors who prioritize steady income, you can zero in on cash generators with strong payouts by checking out 1 dividend fortresses that may suit a yield focused approach.
- If you are hunting for opportunities that the market might not be pricing aggressively yet, scan through 9 high quality undiscovered gems and build a watchlist of under followed ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com