
Forgent Power Solutions (FPS) Stock Could Be Overvalued Following Record Backlog News
Forgent Power Solutions has seen its stock surge this year, and the sharp move is pushing investors to ask whether the current share price still lines up with what its earnings can reasonably support. With the story now closely tied to data center demand and big equipment orders, the question is how far the fundamentals actually go in backing that enthusiasm.
- The stock is up 31.2% year to date, which puts real pressure on the valuation case to show that earnings can carry that kind of move.
- Forgent Power Solutions is reporting record results and a large backlog tied to power equipment for AI driven data centers, which can shape how investors think about the durability and timing of future profit streams.
- The analysts covering Forgent Power Solutions have run their own numbers. See what analysts think Forgent Power Solutions's shares could be worth.
The issue now is whether Forgent Power Solutions' current share price is justified by its earnings profile when you stack it against the Fair Ratio benchmark.
If you are weighing Forgent Power Solutions against other plays on the data center build out, it can help to line it up beside 37 power grid technology and infrastructure stocks.
Has Forgent Power Solutions Run Too Far on Earnings?
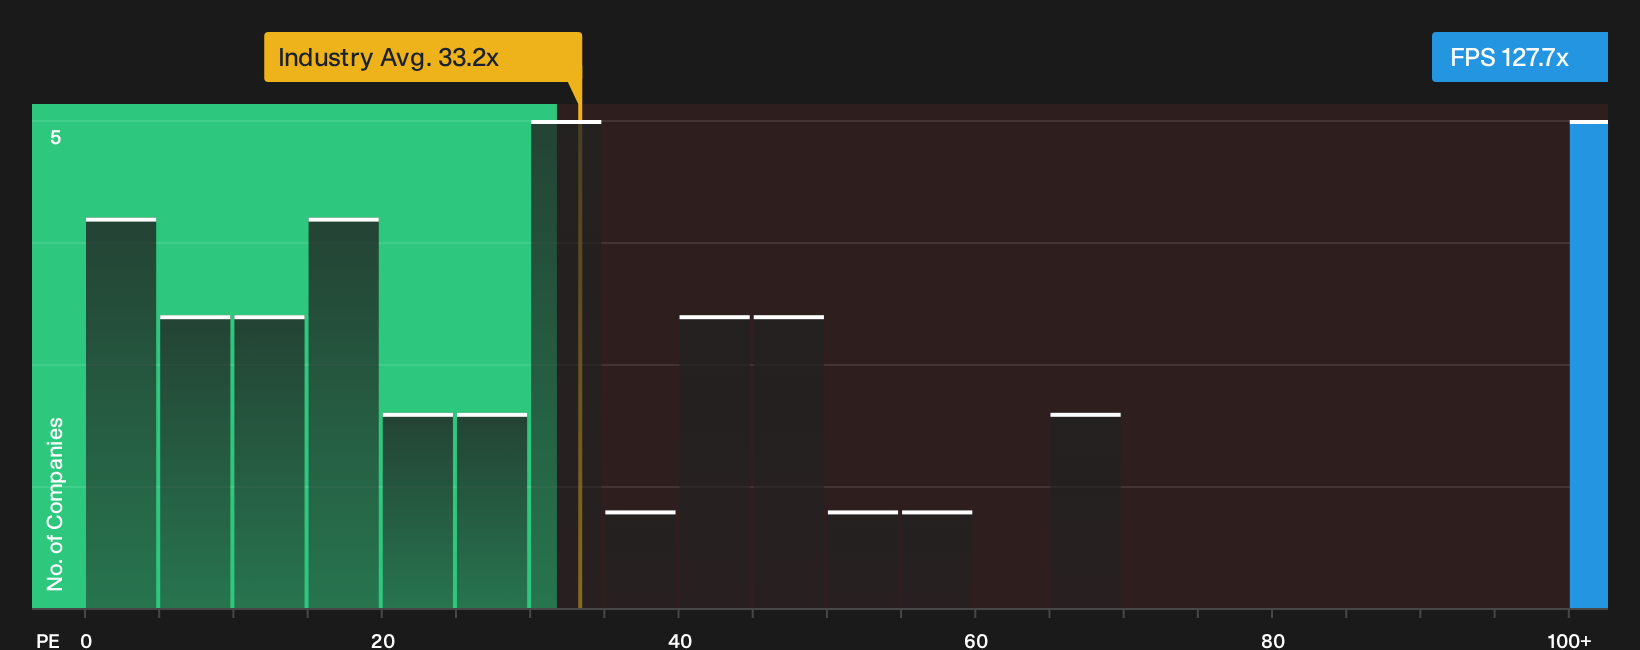
The P/E ratio is a useful yardstick for Forgent Power Solutions because earnings are now a key focus after the recent backlog and data center headlines. Forgent trades on about 127.7x earnings, compared with an Electrical industry average near 33.2x and a peer group around 27.7x. This points to a very rich earnings multiple relative to both broad sector peers and closer comparables.
On this framework, the Fair Ratio, which blends the company’s growth profile, margins, risk and size, sits below the current P/E, so the stock screens overvalued on earnings. Because management just posted record results and a US$3.0b backlog tied to AI related power equipment, investors appear to be paying up heavily for those profit expectations rather than for what is already on the income statement. That leaves the share price heavily exposed to any wobble in execution, order timing or data center demand relative to what this 127.7x tag implies. Explore the numbers behind Forgent Power Solutions's P/E valuation.
The Forgent Power Solutions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Forgent Power Solutions pick up where the high P/E question leaves off by explaining what kind of future growth, profitability and earnings profile would need to occur for the stock to be worth substantially more or less than today’s price. Each narrative moves beyond a single multiple or model output and clearly lays out the assumptions behind its fair value so you can compare them with Forgent Power Solutions' reported numbers over time on the Community page.
A written, number driven Narrative on Forgent Power Solutions helps pin down what would need to happen in earnings and cash generation for today’s P/E to make sense, instead of leaving those expectations as vague optimism around AI and data centers. With record reported results, a US$3.0b backlog and fresh investment in Powertrain Solutions capacity, a clear framework also gives you something concrete to track as new orders, execution and demand for AI data center equipment play through future reports.
Share your own Narrative for Forgent Power Solutions and set out the assumptions behind your valuation.
The price of Forgent Power Solutions is only one piece of the decision
Big expectations can look exciting, but before you lean too hard on the current P/E you may want to understand the specific concerns our checks have raised about Forgent Power Solutions. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com