
How Investors May Respond To Sensirion Holding (SWX:SENS) Biogas Analyzer Launch
- Sensirion Holding has launched the DynamiQ-X BG2300 micro-gas chromatograph for biogas upgrading plants and biomethane facilities, providing full gas composition and hydrogen sulfide analysis in about 45 seconds with an inert sample path and standardized configuration.
- The DynamiQ-X BG2300 targets online process control for biogas and biomethane with worldwide certifications and a single analyzer that delivers calorific value, gas mix and hydrogen sulfide data. This development aligns with Sensirion Holding’s push into higher-value environmental and energy monitoring solutions.
- We will now examine how Sensirion Holding’s investment narrative could be affected by the DynamiQ-X BG2300’s fast online biogas analysis capability.
Scan beyond Sensirion Holding and explore other potential winners in cleaner energy monitoring with a hand-picked set of 37 power grid technology and infrastructure stocks
Sensirion Holding Investment Narrative Recap
Sensirion Holding appeals to shareholders who buy into a long game in environmental and industrial sensing, with earnings growth expected at 15.57% per year and revenue growth forecast at 8.6% per year. The DynamiQ-X BG2300 fits that story by extending the product range in energy and emissions monitoring, but its financial impact is uncertain in the near term.
The near term swing factor still looks like operational execution across core segments such as HVAC, industrial and automotive, as well as how well Sensirion Holding offsets currency pressure after the earlier CHF 10 million finance loss from Swiss franc strength. Key risks remain customer demand shifts, trade policy changes and the reliance on finding new high impact sensor applications.
The DynamiQ-X BG2300 launch aligns with earlier efforts to move up the value chain in environmental sensing, such as the Kuva Systems acquisition that targets data driven solutions for industrial and energy customers. Both push Sensirion Holding further into higher complexity monitoring rather than just component supply.
For catalysts, that direction matters. The Kuva Systems deal points to a model with more recurring and service like revenue potential, while the new micro gas chromatograph showcases how that capability can be applied in cleaner energy and emissions control. Execution risk is present, yet these product and portfolio steps provide concrete milestones to track against the growth narrative.
Sensirion Holding's narrative projects CHF 437.5 million revenue and CHF 42.5 million earnings by 2029. This implies 9.1% yearly revenue growth and an earnings increase of CHF 13.9 million from the current CHF 28.6 million.
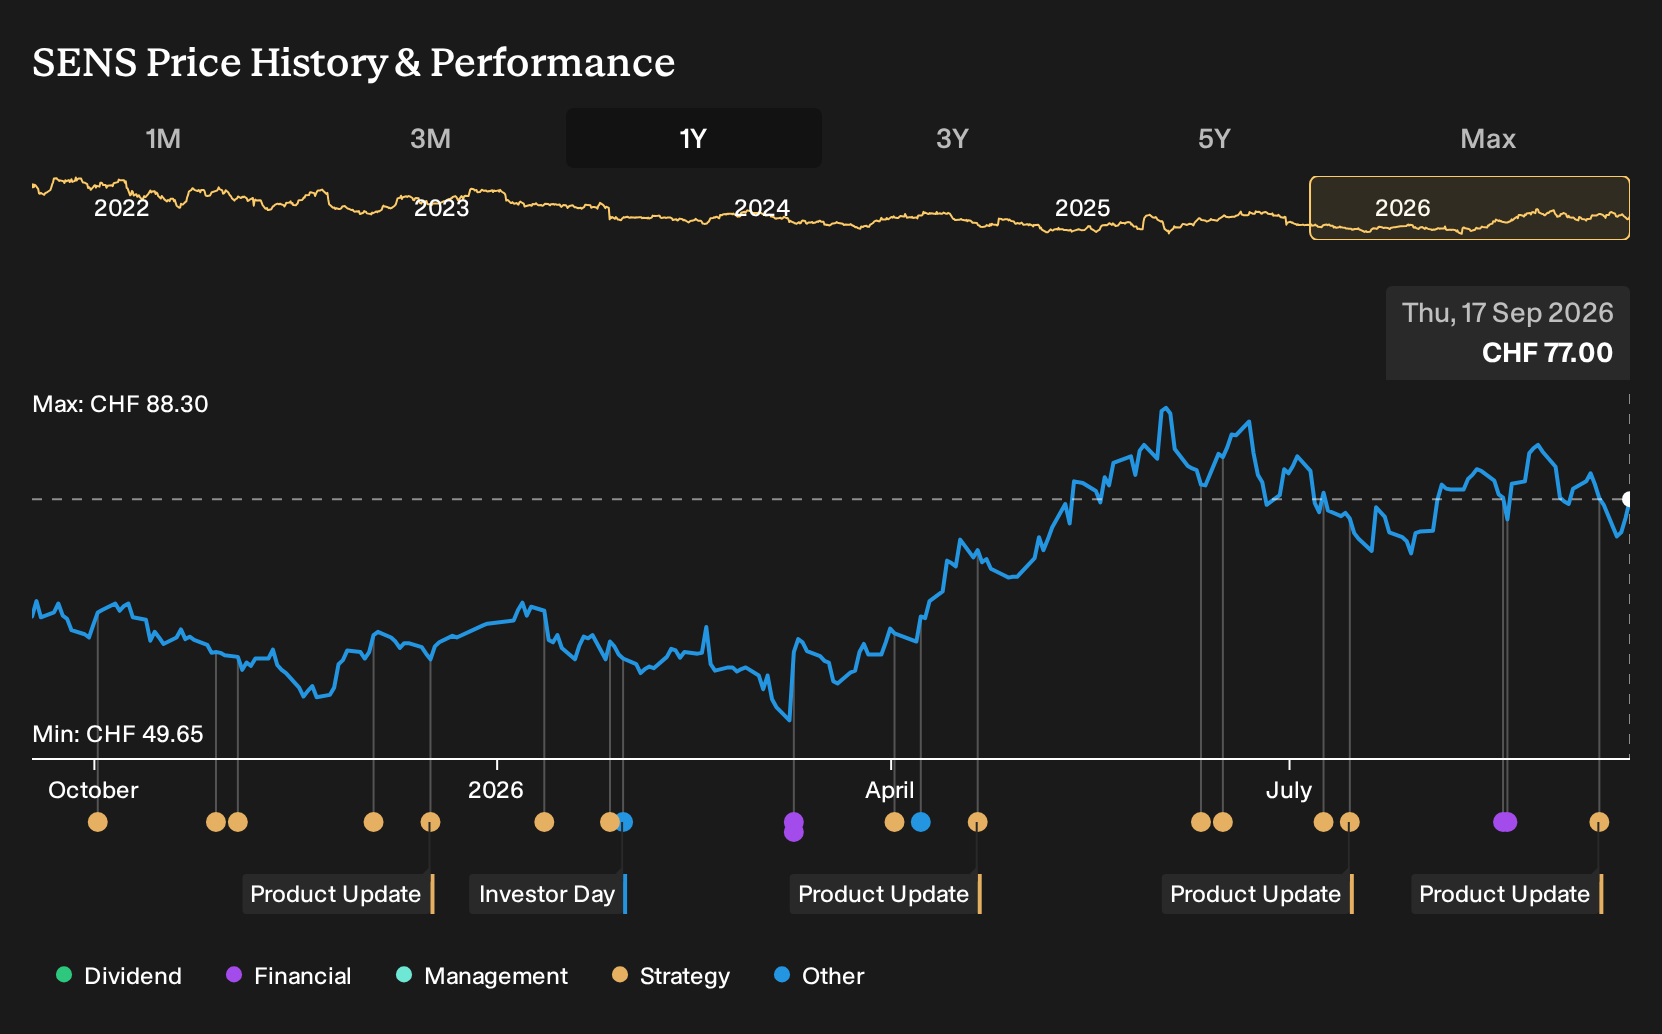
Uncover why Sensirion Holding's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, opinions on Sensirion Holding cluster between roughly CHF 78.08 and CHF 89 per share, with views spread across the full bucket range. That spread sits against real world pressures such as currency swings, trade policy shifts and biogas product execution, so explore multiple viewpoints before deciding where you stand.
Explore 2 other Sensirion Holding fair value estimates, including one that suggests potential upside of as much as 16% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Sensirion Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sensirion Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sensirion Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sensirion Holding?
If the Sensirion Holding story has sharpened your thinking about quality and risk, you can use that same lens across a wider watchlist with the Simply Wall St Screener.
- For investors who want potential mispricings with solid fundamentals, scan a curated set of 173 high quality undervalued stocks that may warrant a closer look.
- If stability and balance sheet strength matter most to you, start with a focused list of solid balance sheet and fundamentals (196 results) and see which businesses fit your risk profile.
- Those hunting for resilient performers with fewer red flags can review a hand picked group of 105 resilient stocks with low risk scores and decide which deserve a place on their radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com