
Earnings Miss Might Change The Case For Investing In LKQ (LKQ)
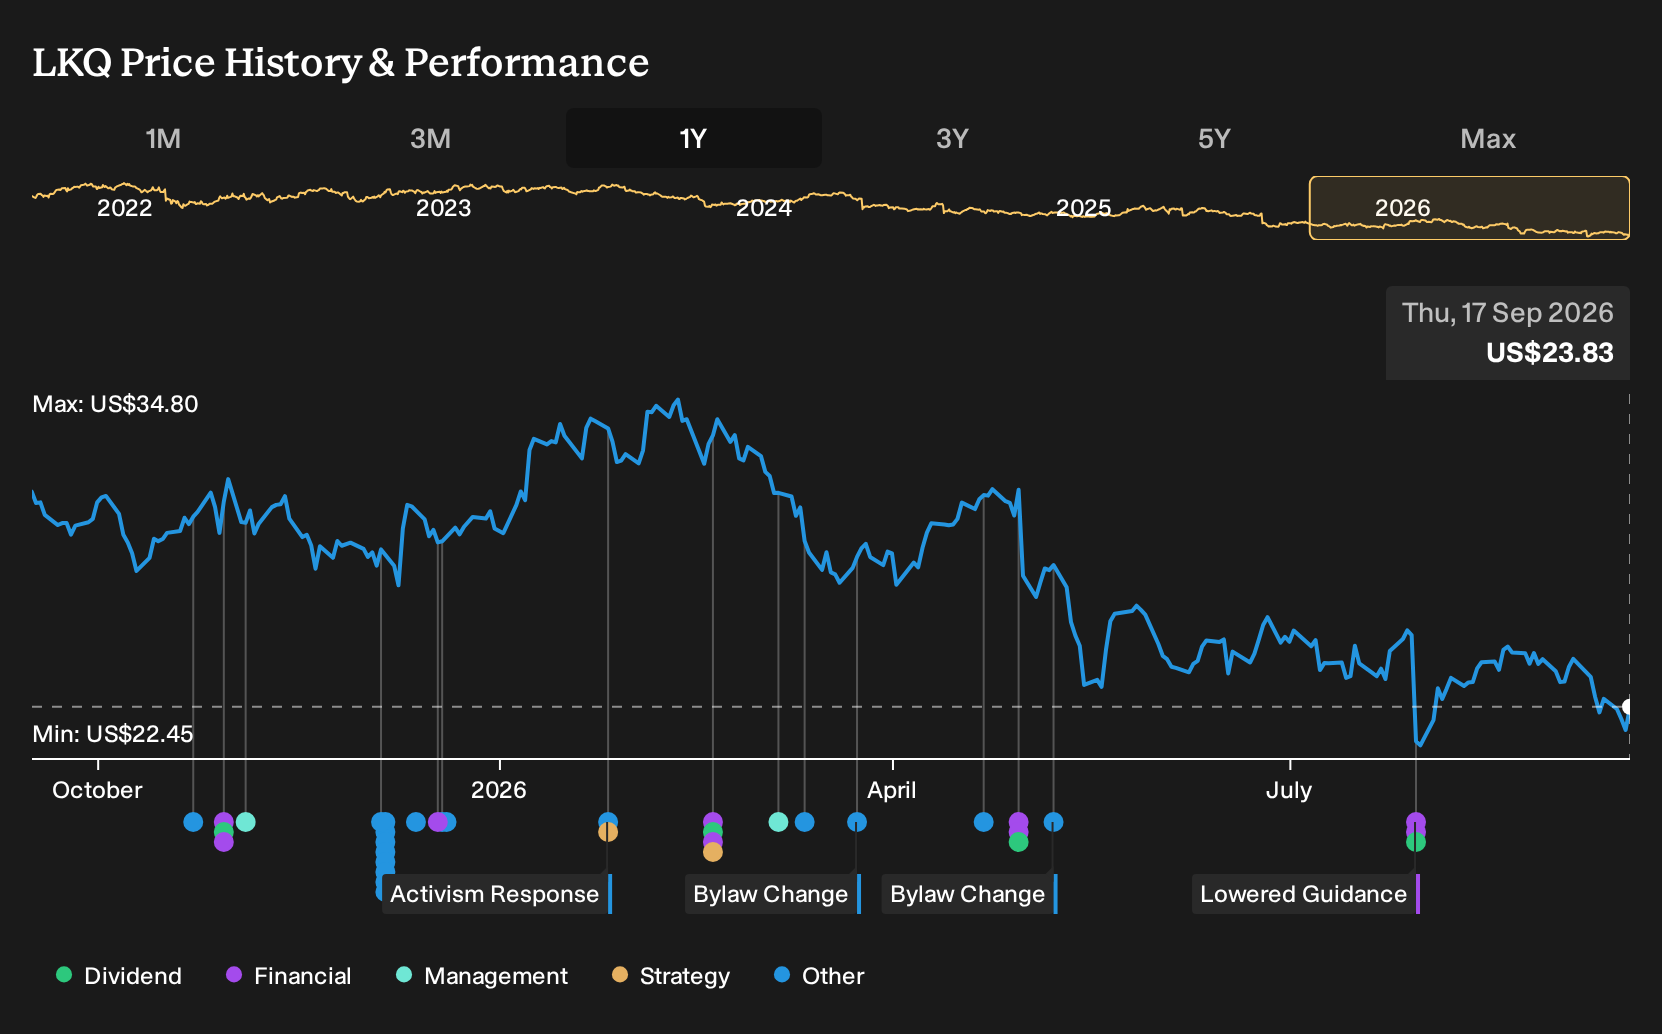
- LKQ recently reported a softer Q2, with revenue declining year on year, missing analyst expectations and prompting a cut to full-year EPS guidance.
- The update highlighted a split picture, with strong execution in North America and Specialty contrasting with operational and volume pressures in Europe linked to an ERP rollout.
- We will now assess how LKQ's weaker Q2 and reduced EPS guidance could reshape the broader investment narrative around the business.
LKQ Investment Narrative Recap
For an LKQ shareholder, the core belief is that a large, diversified vehicle parts distributor can convert scale, cost control and pricing power into steadier earnings over time. The softer Q2 and reduced EPS guidance mainly put a spotlight on execution rather than on the demand backdrop. The key short term catalyst now sits in visible stabilization of European operations and clearer traction from cost and efficiency programs.
The biggest risk remains that European challenges linger, which could keep margins compressed and delay benefits from SKU rationalization, ERP deployment and back office changes. North America and Specialty looked more resilient in the recent update, so the setback feels concentrated, not thesis breaking, unless operational issues in Europe become persistent rather than temporary.
Among recent communication, LKQ has consistently pointed to its multi year cost reduction and simplification effort, including US$125m already removed and a further US$75m targeted, heavily weighted to Europe. That initiative is directly relevant to the current ERP related disruption, because it is meant to support margin recovery once the system issues and volume softness ease.
For you as an investor, that program links straight into catalysts and risks. Evidence that these cuts are flowing through to net margin, without eroding service levels or market share, would support the idea that LKQ can absorb near term hits and still work toward higher profitability. If cost savings stall or are offset by price pressure and repair volume weakness, then the weaker Q2 could signal more than just a bump in the road.
LKQ's current earnings are US$464.0 million, with analysts expecting this to reach US$756.8 million by 2029. This implies an earnings increase of about US$293 million and assumes relatively flat revenue that reaches US$14.0b in 2029.
Uncover why LKQ's fair value indicates a 36% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You have a very different story if you focus on ERP risk in Europe. The lowest LKQ analysts already assumed revenue near US$13.8b and earnings around US$795.2 million by 2029 before this weaker Q2. That is a more pessimistic read on valuation, and it might shift again as views react to the latest update.
Explore 4 other LKQ fair value estimates, including one that suggests it could be worth just $32.50!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your LKQ research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for LKQ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LKQ's overall financial health at a glance.
Looking For More Investment Ideas Beyond LKQ?
If LKQ's recent update has you rethinking concentration risk, it can help to line it up against other opportunities that fit clear financial filters. The Simply Wall St Screener lets you quickly surface companies that match the kind of balance sheet strength, income profile, or valuation style you want to focus on next.
- Prefer to keep risk in check and focus on resilience first, then return second, by scanning a focused group of 11 resilient stocks with low risk scores.
- If income is your priority and you want businesses with higher yields that still aim to maintain stability, take a look at a curated set of 6 dividend fortresses.
- Or, if you are searching for potential future leaders that are not yet widely followed but already show solid fundamentals, start with a hand picked batch of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com