
Ascendis Pharma (ASND) Stock Looks Near Fair Value On Infant Trial Data
Ascendis Pharma has seen its share price lose ground over the past week, and that move now puts a sharper spotlight on whether the current valuation still lines up with the earnings the business generates. With the stock back under pressure, investors are asking how the recent news flow around its rare disease portfolio squares with what they are effectively paying for the company's profit potential.
- The share price declined about 8.5% over the past week, which puts fresh focus on whether the recent drop has brought the earnings based valuation closer to or further from what the business can justify.
- Positive data for TransCon CNP in infants and a planned US$400m share repurchase can influence how investors think about future profitability and the earnings base that underpins Ascendis Pharma's valuation.
- The analysts covering Ascendis Pharma have run their own numbers. See what analysts think Ascendis Pharma's shares could be worth.
The issue now is whether the current Ascendis Pharma share price is adequately supported by its earnings when compared with the industry average.
To see how the same earnings based question playing out at Ascendis Pharma compares with a wider set of opportunities, scan through 29 high quality undervalued stocks.
Where Does Ascendis Pharma Sit on Earnings?
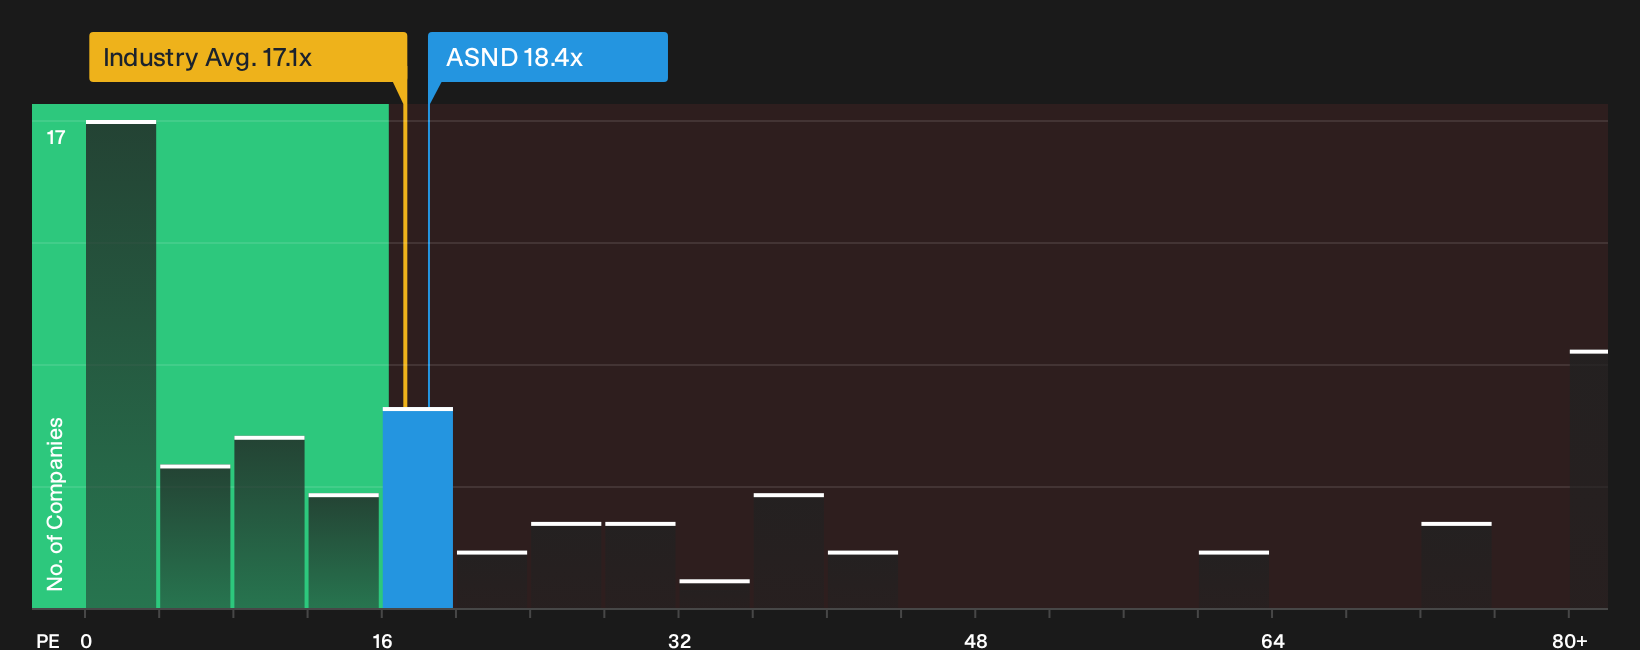
The P/E ratio suits Ascendis Pharma because investors often focus on earnings when weighing rare disease developers that are starting to build a commercial base. Right now the stock trades on about 18.4x earnings, compared with an average of roughly 17.1x for biotechs and a broader peer group closer to 27.9x. That leaves Ascendis a little above the sector benchmark but well below the wider peer set, which points to a valuation that sits somewhere between plain sector exposure and higher priced growth stories in the space.
Because the recent TransCon CNP infant data and the planned US$400m buyback have sharpened interest in the rare disease portfolio, this mid range P/E suggests the share price is not being marked as either a clear bargain or an obvious outlier on earnings alone. For anyone weighing the stock, the key question is whether the quality, duration and risk around Ascendis Pharma's profit stream justify paying this slight premium to the industry average. Explore the numbers behind Ascendis Pharma's P/E valuation.
The Ascendis Pharma Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Ascendis Pharma leaves off by explaining which assumptions on growth, margins and earnings would need to hold for the current share price to appear meaningfully higher or lower than today. Each one turns Ascendis Pharma's implied fair value into a thesis about the business that you can track over time, rather than a one off snapshot, and they are available on Simply Wall St's Community page.
One of the top community narratives on Ascendis Pharma: 11% undervalued
"This narrative explores a more pessimistic perspective on Ascendis Pharma compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts..."
Discover why this Narrative puts Ascendis Pharma at 11% undervalued.
The key question Ascendis Pharma’s valuation does not answer yet
Price and earnings only tell part of the story for Ascendis Pharma, because recent research checks have highlighted specific risk flags that deserve your attention before you lean on the current multiples. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com