
Will Bundled Internet And Care Change AT&T (T) Stock Narrative
- AT&T has rolled out Cricket 5G Home Internet for Cricket Wireless users and expanded its LifeMD partnership to give eligible wireless and fiber customers complimentary virtual care and pharmacy memberships, while also adjusting prices on some legacy wireless plans.
- The mix of bundled home broadband and healthcare services, together with higher rates on older plans, points to AT&T leaning harder into recurring subscription value rather than relying only on core wireless access.
- We will now explore how AT&T's push into bundled 5G home internet and virtual healthcare could reshape its longer term investment narrative.
AT&T Investment Narrative Recap
To own AT&T, you need to back a story where heavy 5G and fiber buildouts, plus bundled services like Cricket 5G Home Internet and LifeMD perks, can support a steady, subscription style cash engine. The key near term swing factor remains execution on subscriber quality, keeping churn and pricing pressure contained while still justifying recent plan changes.
The biggest risk is that intense wireless competition, legacy business wireline drag and high capital spending squeeze margins faster than cost cuts and convergence can help. The Fazal Merchant board appointment looks additive but does not materially shift these near term business drivers on its own.
The most relevant update alongside Merchant joining the board is AT&T’s push into Cricket 5G Home Internet and bundled virtual care through LifeMD. That move leans into higher value, stickier customer relationships, which directly links to the churn and average revenue per user story investors watch closely right now.
Those offers could support the catalyst many shareholders care about, which is steadier recurring cash flow to fund 5G, fiber expansion and balance sheet work while earnings expectations look muted. The risk is that aggressive pricing by rivals or slower take up of these bundles would leave AT&T carrying high investment levels without the hoped for operational payoff.
AT&T’s current analyst script points to revenues of US$136.1b and earnings of US$18.3b by 2029, built on forecast revenue growth of 2.5% a year. That profit figure sits below earnings today of US$21.3b, which implies an earnings decline of about US$3b by the forecast year.
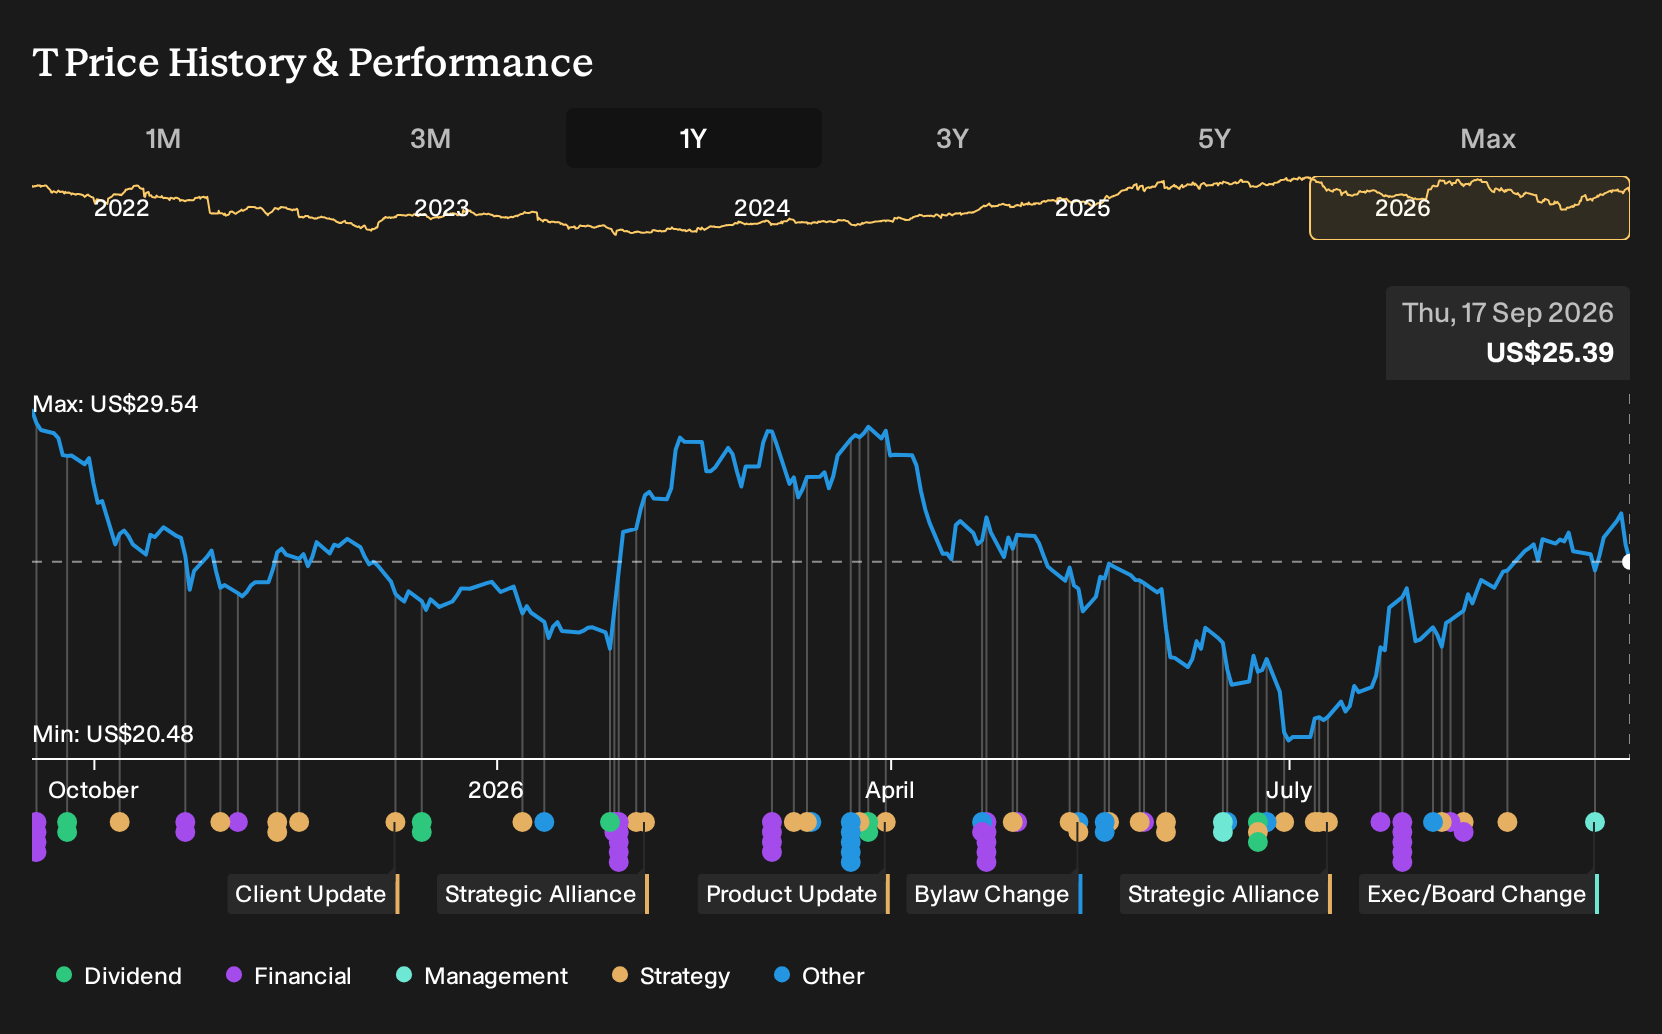
Discover how AT&T's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on execution risk around AT&T’s heavy 5G and fiber spend. The most pessimistic analysts were assuming only 1.7% annual revenue growth to about US$134.0b and earnings around US$17.2b by 2029, before this pricing and bundling news. This shows how sharply opinions can differ and why exploring multiple viewpoints matters.
Explore 7 other AT&T fair value estimates, including one that suggests as much as 16% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AT&T research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for AT&T. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT&T's overall financial health at a glance.
Looking for more AT&T sized investment ideas?
If AT&T has you thinking about consistency, cash generation and balance sheet strength, it can help to line it up against a wider set of businesses using the Simply Wall St Screener.
- For investors who care most about resilient businesses backed by strong finances, compare AT&T with a list of solid balance sheet and fundamentals (23 results) that might offer similar balance sheet discipline.
- If you are hunting for quality at a reasonable price, set AT&T alongside a 29 high quality undervalued stocks to see which companies the numbers suggest could be mispriced.
- Income focused readers who like AT&T for its payout profile can cross check it against a 6 dividend fortresses that may provide comparable yield support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com