
Did Earnings Beat Just Shift Casey's Investment Narrative?
- Casey's General Stores reported first quarter fiscal 2027 sales of US$5,678.34 million and net income of US$273.72 million, with earnings per share from continuing operations above US$7 on both a basic and diluted basis, compared with the prior year period.
- Stronger consumer spending trends and solid inside store performance sit alongside Casey's plan for at least 120 new locations in fiscal 2027. Together, these factors highlight how the chain is leaning into demand rather than slowing expansion.
- We will now look at how Casey's stronger quarterly earnings shape its existing investment narrative and longer term business case.
Scan how Casey's General Stores compares with other retailers that are responding to consumer demand by reviewing a curated set of 29 high quality undervalued stocks.
Casey's General Stores Investment Narrative Recap
To remain a shareholder in Casey's General Stores, you need to believe the chain can keep growing in rural and small-town markets while maintaining its food and fuel economics. The latest quarter, with US$5,678.34 million in sales and US$273.72 million in net income, supports that operating story but does not remove the heavy lifting still required in store integration and remodels.
In the short term, the key factor is execution on inside store sales and margins as cost pressures and regional demand change over time. A major risk is that store expansion and acquisitions may add complexity faster than Casey's can convert locations into its full prepared foods and digital model.
The most relevant update is Casey's decision to add at least 120 new locations in fiscal 2027 through a mix of acquisitions and new builds. That plan is closely tied to the current earnings strength and effectively reinforces the existing approach of rural-centric growth and higher-margin food offerings.
For investors, the key consideration is whether the operation can absorb that many stores without weakening core metrics such as inside same-store sales, margin, and fuel-driven traffic. Execution risk increases with each new site, particularly given labor costs, integration complexity, and the ongoing concern that fuel gallon trends could affect both traffic and ancillary purchases.
Casey's General Stores' current analyst narrative points to revenue reaching US$22.6b and earnings of US$953.9 million by 2029, based on an assumed 8.8% yearly revenue growth rate and an earnings increase of about US$239.5 million from US$714.4 million today.
Uncover why Casey's General Stores' fair value indicates a 56% potential upside to its current price, which could narrow quickly.
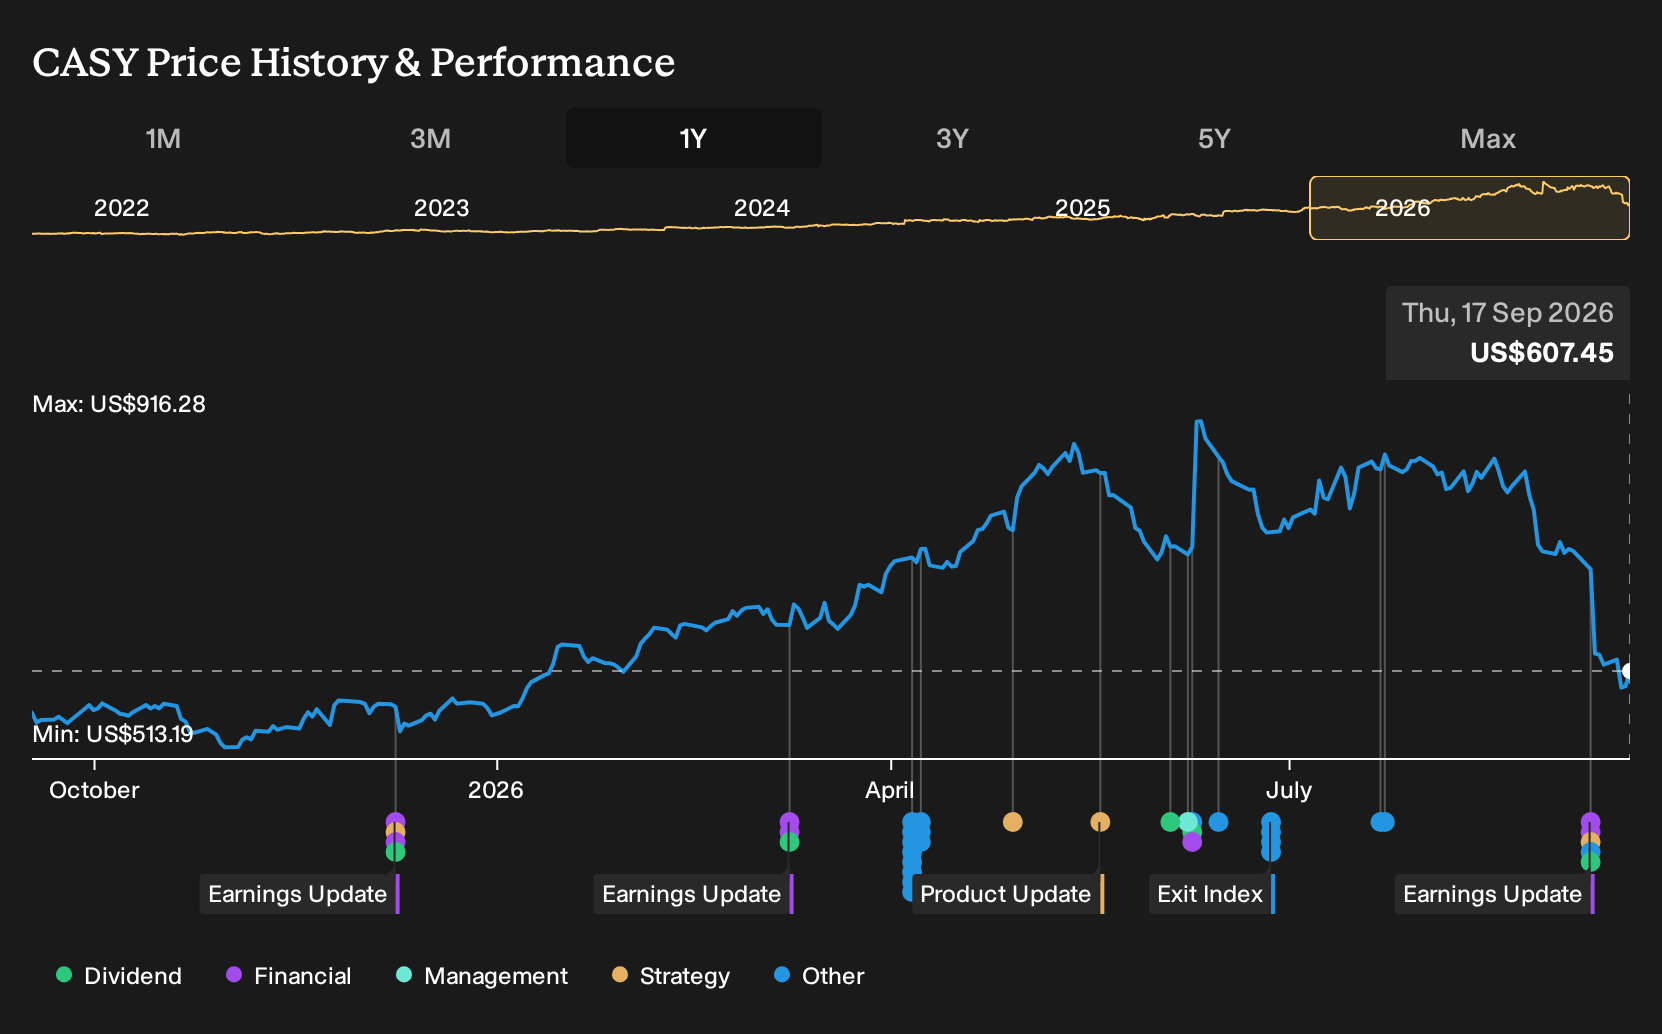
Exploring Other Perspectives
One alternate view on Casey's General Stores focuses heavily on acquisition risk. Those analysts worry that Fikes and CEFCO integration drag could linger, which is why their pre news models assumed only 2.0% yearly revenue growth to about US$19.8b and earnings of roughly US$949.0 million. That is a much more cautious storyline than consensus. These estimates did not factor in the latest quarter or the 120 store buildout, so you may see those projections shift. Use this as a reminder that opinions differ widely and explore both the upbeat and cautious cases before making your own call.
Explore 3 other Casey's General Stores fair value estimates, including one that suggests it could be worth just $722.31.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Casey's General Stores research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Casey's General Stores. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casey's General Stores' overall financial health at a glance.
Looking for more Casey's General Stores sized ideas?
Once the Casey's General Stores story is clear in your mind, it can help to widen the lens and compare it with other opportunities that share some of the qualities you value most, whether that is value, balance sheet strength, or lower risk profiles.
- If you want to focus on quality at a reasonable price, scan a curated 29 high quality undervalued stocks that share strong fundamentals with discounted valuations.
- If balance sheet strength matters most to you, filter for companies with robust finances using a list of solid balance sheet and fundamentals (23 results) to stress test against tougher conditions.
- If capital preservation is front of mind, narrow your search to a 11 resilient stocks with low risk scores that screens for businesses with more resilient risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com