
Nordnet (OM:SAVE) Could Be 8% Undervalued Following Its Private Banking Deal
Nordnet (OM:SAVE) just moved to reshape its high net worth offering, agreeing with ABG Sundal Collier to form a jointly owned private banking company that blends digital access with advisory and portfolio management.
The new private banking push comes after a mixed stretch for Nordnet’s shares. The 1-day share price return is 1.01%, the 30-day share price return is down 6.53%, and the year-to-date share price return remains up 26.34% from SEK340.6.
Scan how Nordnet’s private banking pivot compares with other higher quality financial platforms by checking our curated list of list of solid balance sheet and fundamentals (196 results).
Nordnet is focusing more on affluent clients just as the share price has cooled in recent weeks. The key question is whether this reset leaves enough potential upside to justify the risks investors face from here, as outlined in the valuation section next.
Most Popular Narrative: 8% Undervalued
Nordnet’s most followed narrative points to a fair value of about SEK368 per share, slightly above the recent close near SEK340. This frames the current private banking push against an already constructive long term story.
The firm's operating leverage and disciplined cost control (revenue growth of 25% per year since 2019 outpacing 7% cost growth) provide a basis for net margin and earnings improvement as its technology-driven business model scales across a pan-European customer base.
See why 9 investors see Nordnet as 8% undervalued.
Result: Fair Value of SEK368 (UNDERVALUED)
Still, the narrative could crack if rising operating costs keep outpacing revenue or if tougher Nordic fee competition pressures Nordnet's pricing power and profitability.
Find out about the key risks to this Nordnet narrative.
Another View On Nordnet’s Valuation
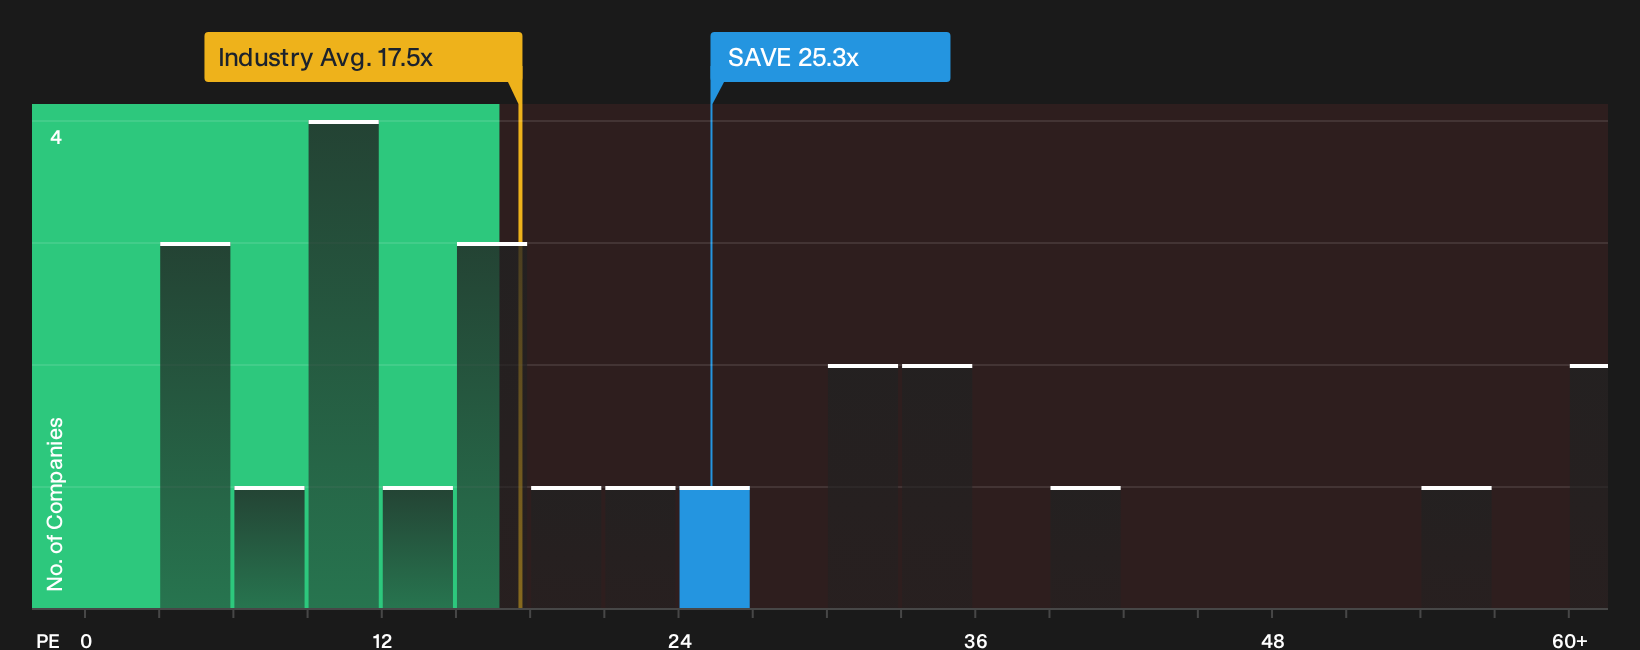
On price ratios, Nordnet looks far less generous. The shares trade on a P/E of 25.3x, which is higher than both the Swedish Capital Markets industry at 17.5x and the fair ratio estimate of 17.7x. That points to valuation risk if sentiment cools or growth expectations ease.
Investors weighing this richer multiple against the earlier fair value narrative need to ask a simple question: Is Nordnet’s profile strong enough to justify paying above both sector and fair ratio levels, or is this where discipline should start to matter more?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Nordnet attracting both enthusiasm and concern, it makes sense to move fast and review the underlying data yourself before opinions harden. To weigh up both the potential rewards and the flagged risks side by side, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Nordnet?
If Nordnet’s story has you thinking harder about where risk and reward line up, use this moment to scan other opportunities before the next wave of money moves.
- Target resilient balance sheets and healthier fundamentals by working through our focused list of solid balance sheet and fundamentals (196 results).
- Hunt for potential value opportunities that pair quality with more appealing pricing using the dedicated 173 high quality undervalued stocks.
- Zero in on companies that rarely hit the spotlight but still show strong fundamentals with the curated 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com