
Exploring European Undervalued Small Caps With Insider Action In September 2026
In September 2026, European markets have been navigating a challenging landscape as the pan-European STOXX Europe 600 Index ended the week down 1.66%, pressured by escalating U.S.-Iran tensions that drove oil and European natural gas prices higher, stoking inflation concerns and pushing government bond yields upward. Amid these conditions, small-cap stocks in Europe present unique opportunities for investors who are keen on exploring potential undervaluation coupled with insider action, which can be indicative of confidence in a company's future prospects despite broader market uncertainties.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 39.62% | ★★★★★★ |
| Nyab | 17.5x | 0.8x | 32.76% | ★★★★☆☆ |
| Franchise Brands | 27.7x | 2.0x | 46.71% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 17.29% | ★★★★☆☆ |
| Saniona | 7.5x | 3.3x | 30.01% | ★★★★☆☆ |
| Linc | 12.6x | 13.1x | 32.31% | ★★★★☆☆ |
| Vistry Group | 6.2x | 0.2x | -18.29% | ★★★☆☆☆ |
| Eurocell | 22.3x | 0.3x | 48.68% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 20.64% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -219.06% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Domino's Pizza Group (LSE:DOM)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Domino's Pizza Group is a leading pizza delivery company operating a franchise model with numerous stores primarily in the UK and Ireland, boasting a market capitalization of approximately £1.48 billion.
Operations: The company's revenue primarily stems from its sales, with a notable increase from £316.79 million in 2015 to £707.5 million by 2026. Cost of goods sold (COGS) has also risen over the same period, impacting gross profit margins, which fluctuated between 39.02% and 47.99%. Operating expenses have consistently grown alongside revenue, reflecting increased spending on general and administrative costs as well as sales and marketing efforts.
PE: 13.4x
Domino's Pizza Group, a notable player among Europe's smaller companies, showcases potential for value with its recent financial performance. For the half year ending June 2026, sales reached £353.6 million, up from £331.5 million the previous year. Insider confidence is evident with share purchases in recent months. Despite high debt levels and reliance on external borrowing, earnings are projected to grow annually by 9.29%. A dividend increase to 3.7 pence per share further signals positive momentum for investors seeking income and growth opportunities in this space.
- Delve into the full analysis valuation report here for a deeper understanding of Domino's Pizza Group.
Evaluate Domino's Pizza Group's historical performance by accessing our past performance report.
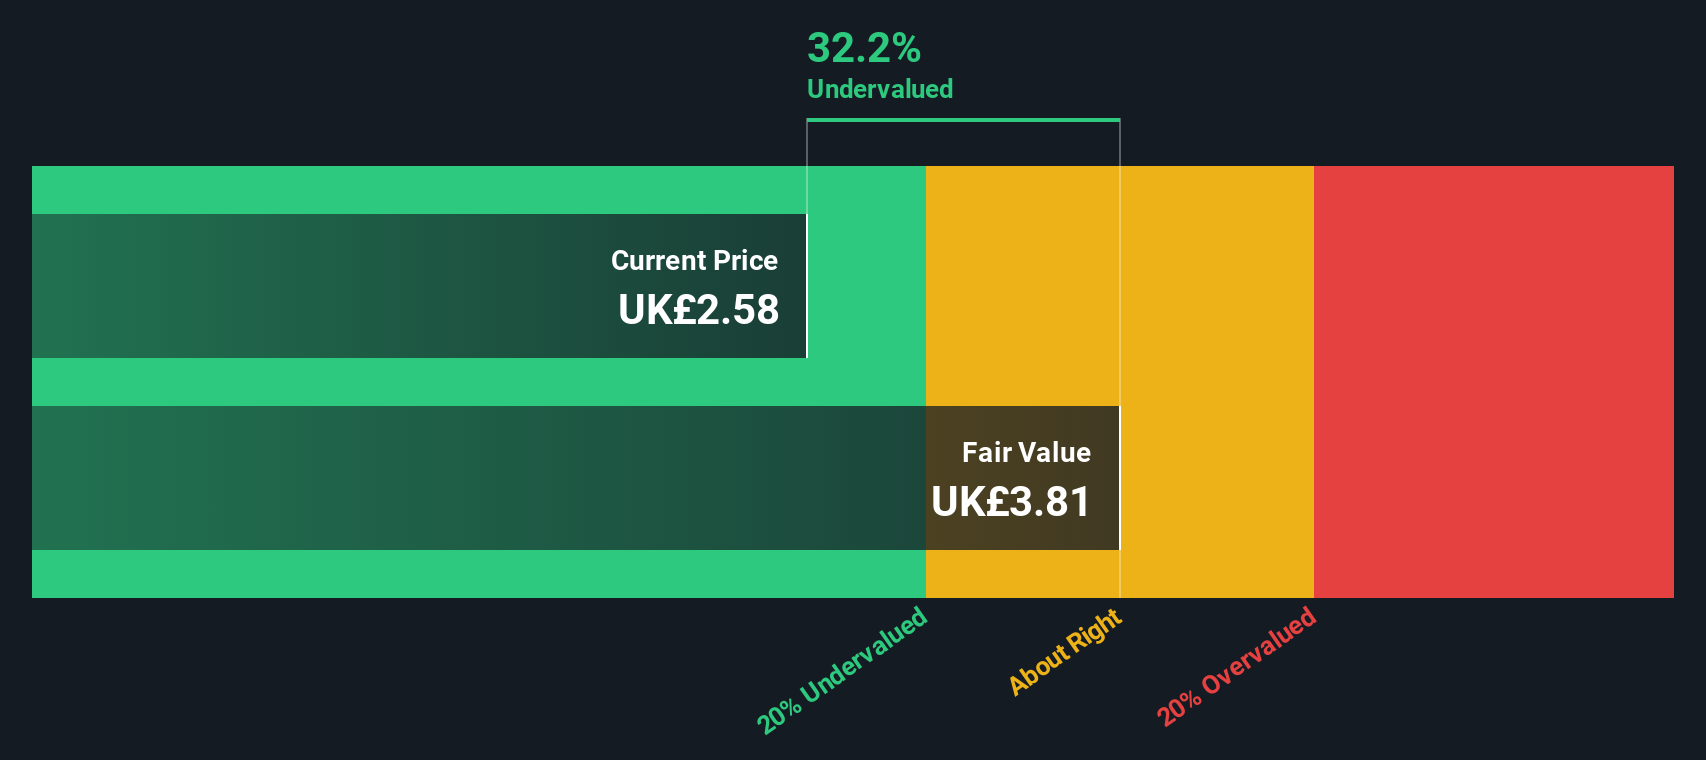
Vistry Group (LSE:VTY)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Vistry Group is a UK-based construction company primarily engaged in residential and commercial home building, with a market capitalization of approximately £1.72 billion.
Operations: The company's primary revenue stream is from its Home Builders segment, generating £3.61 billion. Over recent periods, the gross profit margin has shown a notable decline, reaching 10.78% by the end of 2025. Operating expenses have been a significant component of costs, with general and administrative expenses being consistently high across periods.
PE: 6.2x
Vistry Group, a small cap in Europe, has seen insider confidence recently with share purchases over the past three months. Despite a volatile share price in this period, the company is poised for future earnings growth at 4.62% annually. However, its reliance on external borrowing for funding presents higher risk compared to customer deposits. Recent executive changes include CFO Tim Lawlor's departure by October 2026, which may impact strategic continuity as they search for his successor.
- Get an in-depth perspective on Vistry Group's performance by reading our valuation report here.
Examine Vistry Group's past performance report to understand how it has performed in the past.

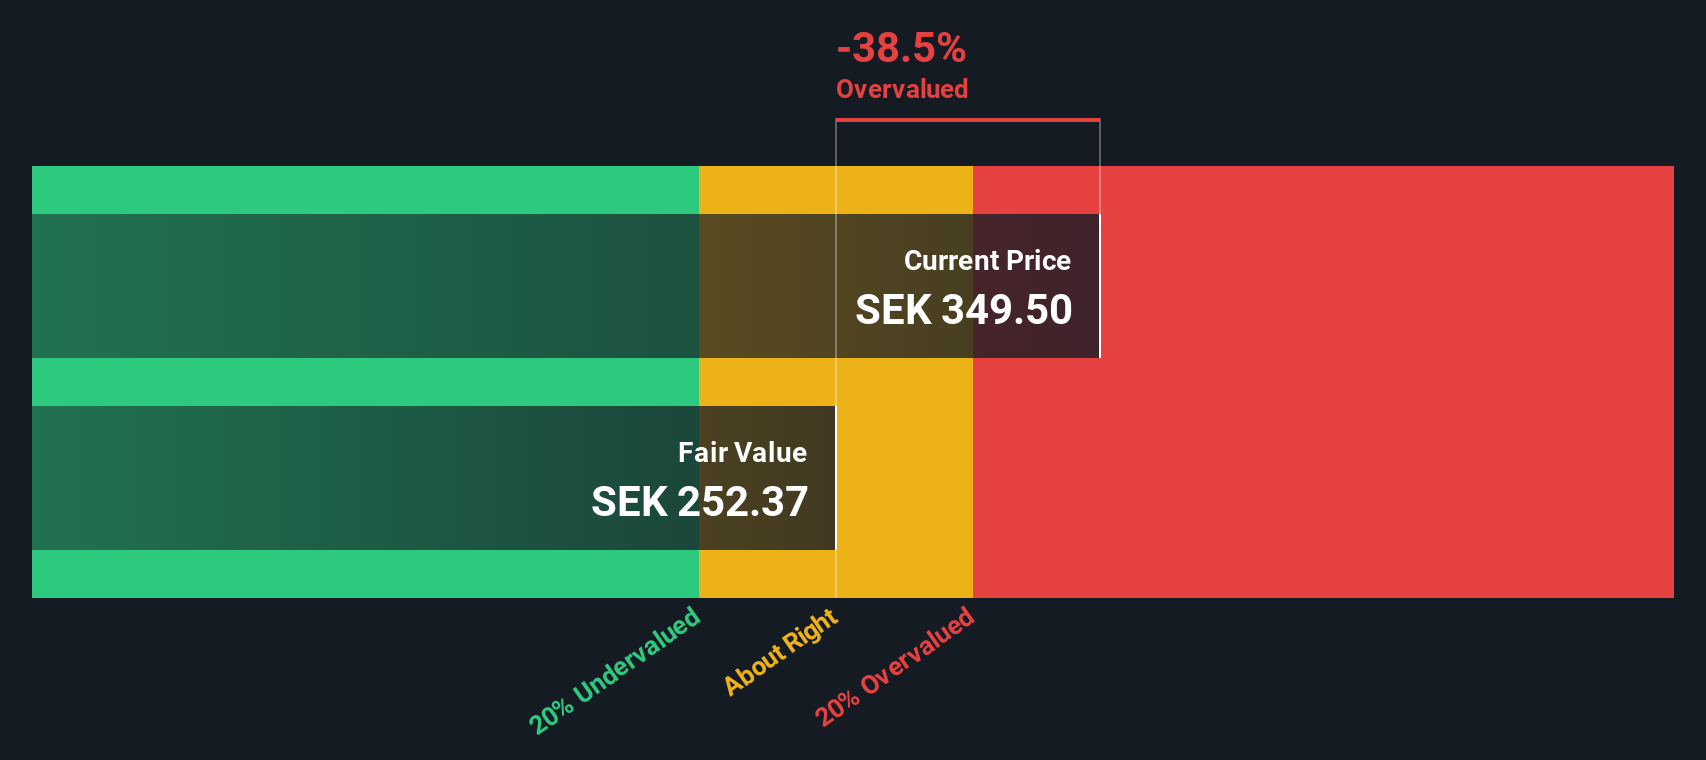
Bergman & Beving (OM:BERG B)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Bergman & Beving is a company that operates in the industrial sector, focusing on core solutions, personal protective equipment and utilities, safety technology, and machinery and equipment, with a market capitalization of approximately SEK 3.74 billion.
Operations: Bergman & Beving's revenue is primarily derived from Core Solutions, PPE & Utilities, Safety Technology, and Machinery & Equipment. The company has seen fluctuations in its gross profit margin over time, with a recent figure of 50.38%. Operating expenses have been significant, impacting net income margins which were last recorded at 4.56%.
PE: 30.6x
Bergman & Beving, a European industrial products company, displays potential as an undervalued stock due to its consistent earnings growth forecast of 12.78% annually. Despite high debt levels and reliance on external borrowing, the company's strategic focus on acquiring and developing industrial solutions firms could enhance its market position. Recent board changes include Natalia Borelius joining in August 2026, signaling fresh leadership perspectives. The company completed a share buyback of 200,000 shares for SEK 29 million earlier this year.
- Dive into the specifics of Bergman & Beving here with our thorough valuation report.
Gain insights into Bergman & Beving's past trends and performance with our Past report.
Make It Happen
- Delve into our full catalog of 36 Undervalued European Small Caps With Insider Buying here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com