
Kusuri No Aoki Holdings (TSE:3549) After August Sales, Is The Valuation Too Rich
Kusuri No Aoki Holdings (TSE:3549) just released preliminary August sales, with all stores at 110.7% and existing outlets at 100.7%. This gives investors a fresh read on consumer demand and store productivity.
The latest sales update lands as Kusuri No Aoki Holdings’ share price has climbed 14.05% over the past 90 days, even though the year-to-date share price return is down 9.49%. That short-term momentum sits alongside a 4.27% one-year total shareholder return and a 48.45% three-year total shareholder return, which indicates that investors are gradually rewarding the longer-run story more than the recent pullback.
Scan how Kusuri No Aoki Holdings compares with other retailers showing resilient demand by reviewing the hand picked list of solid balance sheet and fundamentals (20 results) in this space.
Sales look healthy and the longer term chart for Kusuri No Aoki Holdings is positive, yet the share price is still below its recent high. Is the current valuation generous, or does it offer a margin of safety?
Price-to-Earnings of 22.7x for Kusuri No Aoki Holdings: Is it justified?
Kusuri No Aoki Holdings trades on a P/E of 22.7x, which looks rich next to both its industry and an internally estimated fair P/E level.
The P/E multiple compares the share price with earnings per share and is a quick way to see how much investors are willing to pay for current profits. For a retailer like Kusuri No Aoki Holdings, this ratio often reflects expectations for steady cash generation, store rollouts, and the stability of everyday consumer spending.
Here, the stock is described as expensive relative to the JP Consumer Retailing industry average P/E of 12.9x. This implies investors are paying a much higher price for each unit of earnings than they pay for sector peers. It is also flagged as expensive versus an estimated fair P/E of 16x. This suggests the market is attaching a premium that could narrow if sentiment cools or if profitability does not keep pace with this pricing.
The contrast with the industry is stark, with Kusuri No Aoki Holdings trading on a materially higher P/E multiple than the sector benchmark. This signals that the market is pricing in stronger prospects or quality compared with many rivals.
Explore the SWS fair ratio for Kusuri No Aoki Holdings.
Result: Price-to-Earnings of 22.7x (OVERVALUED)
Still, the valuation story for Kusuri No Aoki Holdings could be tested if consumer demand softens or if earnings growth falls short of what a 22.7x P/E implies.
Find out about the key risks to this Kusuri No Aoki Holdings narrative.
Another View on Kusuri No Aoki Holdings’ Valuation
The P/E looks demanding, yet the SWS DCF model points in the opposite direction. With Kusuri No Aoki Holdings trading at ¥4,100 against an estimated future cash flow value of ¥4,508.93, the shares are described as about 9.1% below fair value. Which signal should you weigh more heavily?
Look into how the SWS DCF model arrives at its fair value.
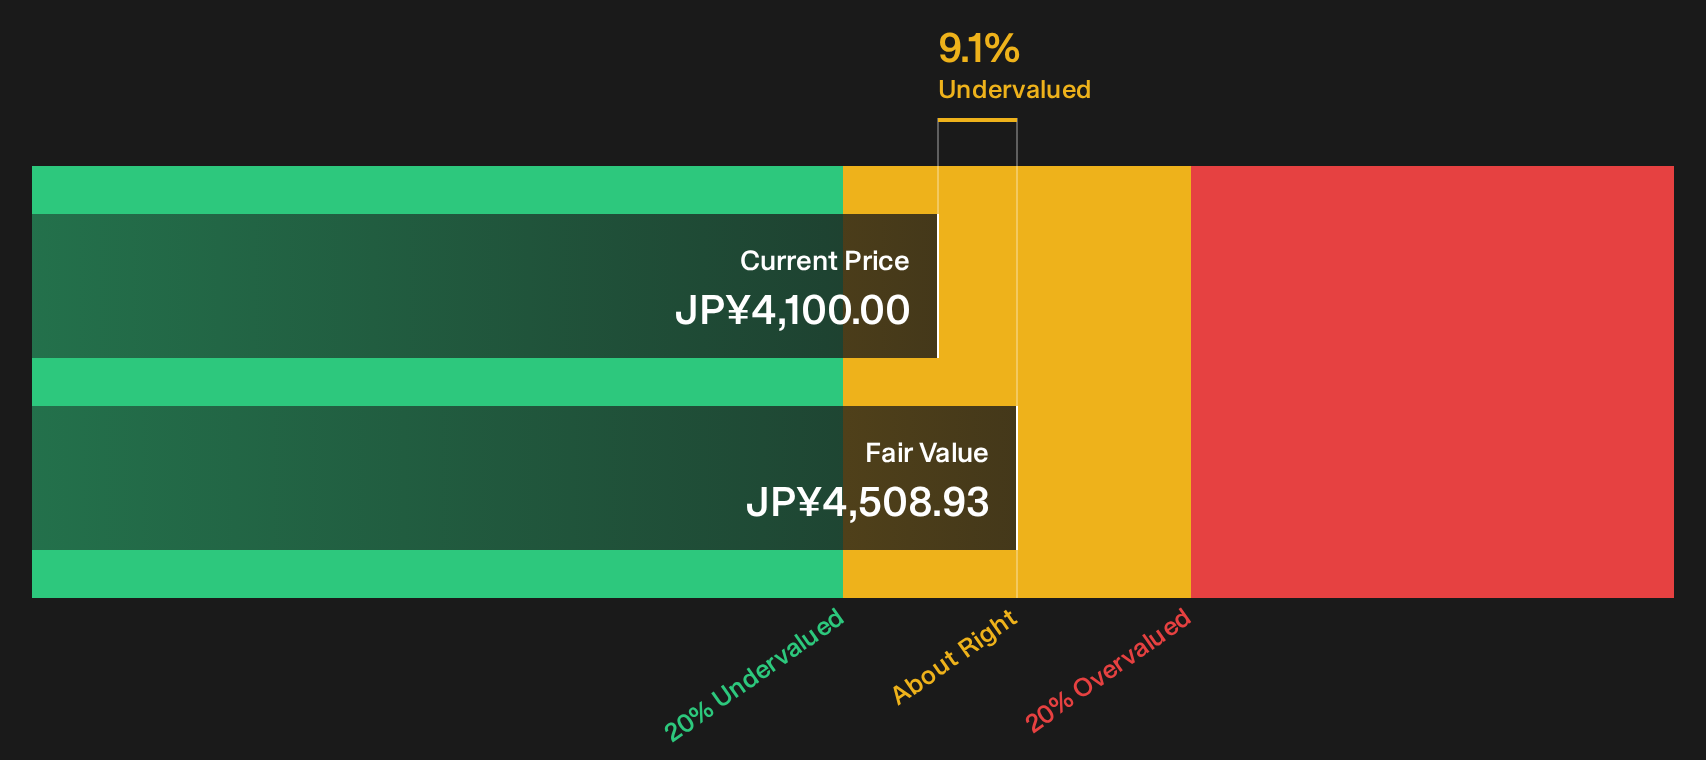
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kusuri No Aoki Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
So does this mix of solid sales and a punchy P/E make Kusuri No Aoki Holdings look stretched or still interesting? If you want to move quickly and build your own take from the underlying data and context, start by weighing the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Kusuri No Aoki Holdings?
If Kusuri No Aoki Holdings has your attention, broaden your watchlist with a few focused stock ideas that match different risk, income, and value preferences.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive entry points using the 17 high quality undervalued stocks.
- Stack income potential on top of capital returns by reviewing a curated set of resilient high yield payers through the 14 dividend fortresses.
- Dial down portfolio risk by hunting for businesses with stronger balance sheets and steadier profiles using the 20 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com