
Analyst Upgrades Might Change The Case For Investing In Onto Innovation (ONTO)
- Onto Innovation recently attracted strong support from brokerage firms, with an average recommendation near the top of their rating scales based on 13 firms. This reflects renewed attention to its role in process control for advanced semiconductor manufacturing.
- The real hook for investors is what sits behind those views: rising analyst confidence in Onto Innovation’s earnings potential as chipmakers rely more heavily on process control tools for complex packaging and new device architectures.
- The next area of focus will be how this stronger analyst conviction around Onto Innovation’s earnings prospects could influence the broader investment narrative.
Scan how other process control and semiconductor beneficiaries are lining up by reviewing the hand picked 89 AI infrastructure stocks.
Onto Innovation Investment Narrative Recap
For Onto Innovation, the core belief is that demand for advanced process control in AI packaging and leading edge nodes will remain an important driver for orders. The near term swing factor is how quickly customers translate planned spending into actual tool shipments, especially as the firm leans on a recovery in AI focused projects expected in Q4 and 2026.
The biggest operational risk is that this expected rebound in AI packaging and advanced nodes arrives later or softer than customers have outlined. The recent analyst optimism around earnings power does not change that dependency. It mostly reinforces what is already priced into the current earnings narrative.
The Semilab acquisition sits closest to this earnings focused news, because it directly affects how Onto Innovation builds out its tool portfolio for advanced materials and heterogeneous integration. Management is adding electrical surface metrology and materials analysis systems that plug into the same AI and advanced packaging themes driving attention today.
Execution around Semilab now ties into both opportunity and risk. Successful integration and cross selling could support the expected ramp in revenue and margins that analysts are modeling. Slower synergy capture or customer hesitation would make the current optimism more fragile, especially with margins already below last year and one off items clouding recent results.
Onto Innovation's narrative projects US$2.4b revenue and US$827.0m earnings by 2029. This setup implies analysts are modeling 29.3% yearly revenue growth and an earnings increase of about US$694.4m from US$132.6m today.
Uncover why Onto Innovation's fair value indicates a 55% potential upside to its current price before other investors close that gap.
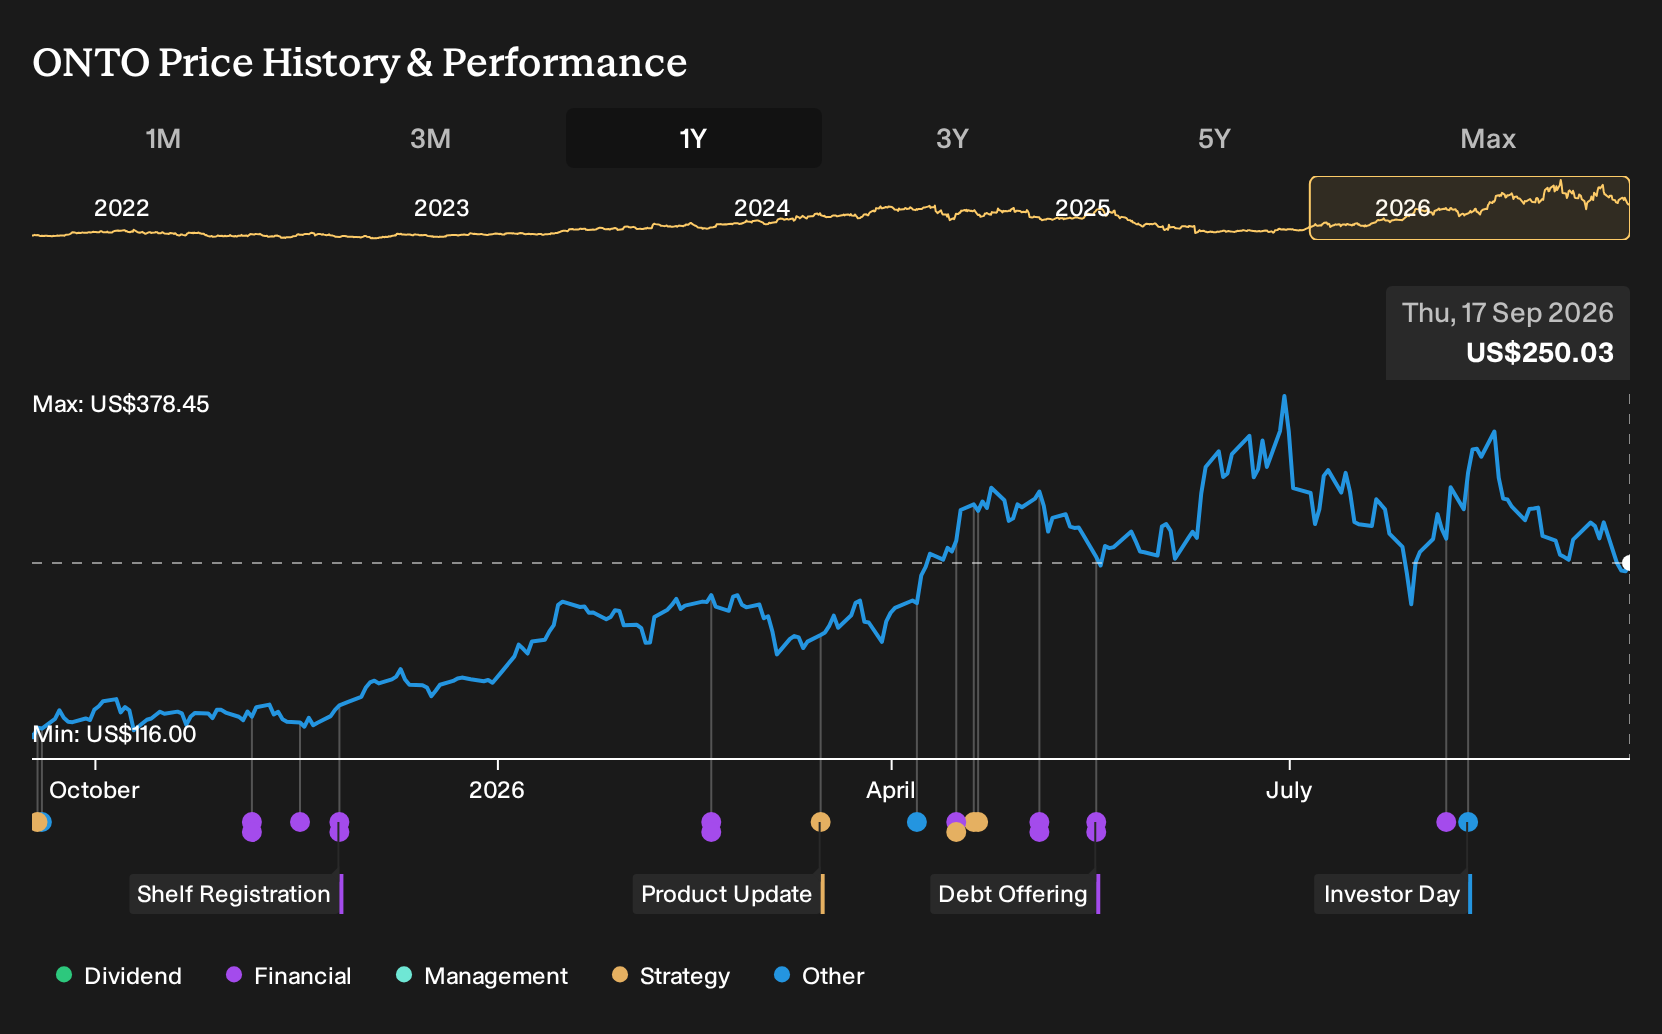
Exploring Other Perspectives
One alternate view on Onto Innovation puts far more weight on AI packaging as a long runway rather than a short rebound risk. The most optimistic analysts were penciling in about US$2.8b revenue and US$824.8m earnings by 2029 before this news. Use that gap in expectations to compare several possible futures for the story.
Explore 4 other Onto Innovation fair value estimates, including one that suggests as much as 55% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Onto Innovation research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Onto Innovation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Onto Innovation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Onto Innovation?
Once you have a handle on Onto Innovation, it can help to widen the lens and compare it with other opportunities using filters that match your risk tolerance, income needs, and quality focus.
- For investors who want income strength as a starting point, review a shortlist of 6 dividend fortresses that concentrate yield in companies with sizeable payouts.
- If capital preservation and steadier profiles matter more to you, sort through a curated 30 resilient stocks with low risk scores to see which businesses score well on resilience metrics.
- When you are hunting for under followed quality, sift through a focused 16 high quality undiscovered gems that highlights financially sound companies which many investors may have overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com