
G Mining Ventures (TSX:GMIN) Could Be 18% Undervalued After New Brazil Gold Drilling
G Mining Ventures (TSX:GMIN) just reported fresh exploration results from its Gurupi Project and Tocantinzinho mine in Brazil, highlighting a new near-surface gold find and extended mineralization beneath existing pit designs.
G Mining Ventures’ share price has climbed to CA$49.75, with a 30-day share price return of 8.13% and a 90-day move of 20.81%. The 1-year total shareholder return of 107.38% points to strong momentum building over a longer stretch as investors weigh the new drilling results against the broader growth and risk profile.
Scan G Mining Ventures’ drilling-driven momentum against a curated field of peers by reviewing the 36 elite gold producer stocks that is shaping the next phase of the gold sector.
Bulls see G Mining Ventures’ drilling success and rising returns as the early stages of a rerating. Bears see a hot story priced in. Which case do the current valuation markers support next?
Most Popular Narrative: 18% Undervalued
Against a last close of CA$49.75, the most followed valuation storyline for G Mining Ventures points to a higher fair value anchored on aggressive build out plans and heavy cash flow recycling from TZ into new projects.
The company is pursuing its largest exploration program to date across TZ, Oko West and Gurupi, including around 110 kilometers of drilling and work on new targets such as the Northwest expansion at Oko West and district scale trends at Gurupi. This activity could extend mine lives or support new mines and affect long term revenue and free cash flow profiles.
See why 9 investors see G Mining Ventures as 18% undervalued.
Result: Fair Value of CA$60.69 (UNDERVALUED)
Still, the G Mining Ventures story can change quickly if weaker gold prices squeeze TZ margins or if Oko West spending overruns start to strain cash generation.
Find out about the key risks to this G Mining Ventures narrative.
Another View: G Mining Ventures Through The P/E Lens
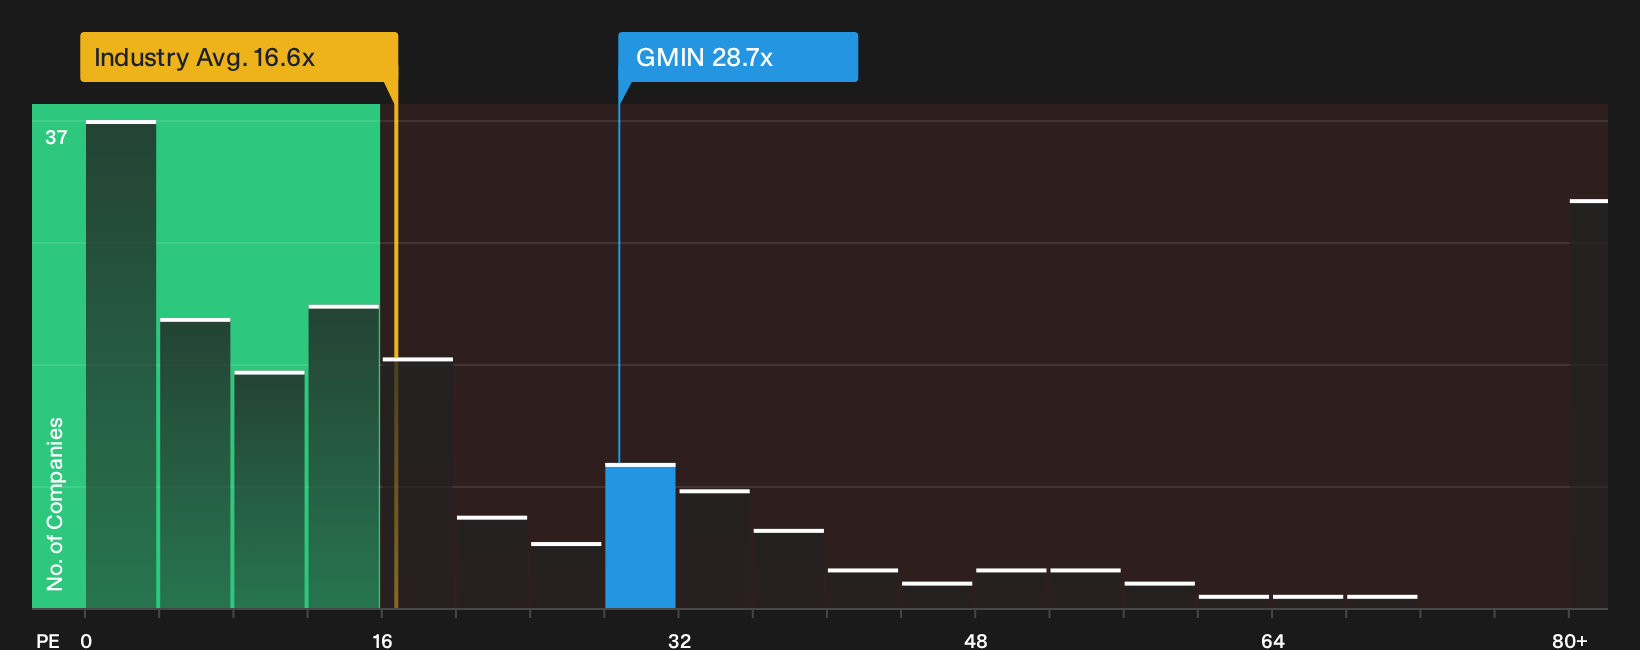
There is a very different read on G Mining Ventures if you step away from fair value models and look at the plain P/E number. The shares trade on about 28.7x earnings, while the Canadian Metals and Mining group sits near 16.5x and close peers average 14.5x.
That means investors are already paying a hefty premium over both the sector and peer pack, even though the fair ratio implies a P/E of roughly 28.3x instead. The gap is small on that fair ratio check, yet large against the wider group. This raises a simple question for you: is this multiple paying you enough for execution and gold price risk, or are you effectively prepaying for years of strong delivery?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data so far? Act while the information is fresh and pressure test G Mining Ventures for yourself by weighing its 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond G Mining Ventures?
Do not stop your research with G Mining Ventures. Broaden your watchlist now and give yourself a better chance of finding the mix of risk and reward that fits you.
- Target stronger balance sheets by scanning companies in the list of solid balance sheet and fundamentals (7 results) that can better withstand pressure when conditions change.
- Hunt for mispriced opportunities by reviewing the 3 high quality undervalued stocks that pair quality fundamentals with compressed valuations.
- Spot potential early-stage candidates by checking the 9 high quality undiscovered gems that the wider market may not be focusing on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com