
3 Aluminum Exposed Stocks Facing New US Tariff Pressure
Tariffs on Canadian aluminum have abruptly reshuffled who pays more, who gets squeezed, and who might quietly gain ground. Supply chains that once looked routine now carry pricing twists and contract risks that can feed straight into earnings. This article walks through three stocks exposed to the latest US tariff moves, showing where the pressure points sit and where investors might find potential opportunity or decide to stay on the sidelines.
The stocks highlighted below are just a first pass at aluminum exposed opportunities. The full screen surfaced 49 more North American aluminum consumers with equally detailed stories that are not covered here. To identify your own high conviction ideas, head straight into the North American Aluminum Consumers and Downstream Users screener to filter and analyze this wider group of aluminum linked businesses.
Allison Transmission Holdings (ALSN)
Allison Transmission Holdings plugs directly into the aluminum story through the metal rich housings and components inside its truck and defense gear, while its position as a large US industrial player is what makes the growth path here worth a closer look.
Allison Transmission Holdings designs and sells automatic transmissions and electrified propulsion systems for trucks, buses, off highway equipment, and defense vehicles, with aluminum heavy components tying it to North American metal supply, and the business now carries a market value of about US$9.8b.
"The recently announced acquisition of Dana's Off-Highway business materially expands Allison's global footprint, diversifies its end markets to include agriculture and construction, and is expected to drive significant operational and cost synergies ($120 million annual run rate), supporting both revenue growth and margin enhancement over the next 4 years."
What really matters for Allison Transmission now is how one quiet shift in its cost base feeds through to the next leg of margin performance.
If that margin story is what you care about, read the full narrative for Allison Transmission Holdings to see where aluminum costs, synergies and pricing power could be decoupling next.

Lear (LEA)
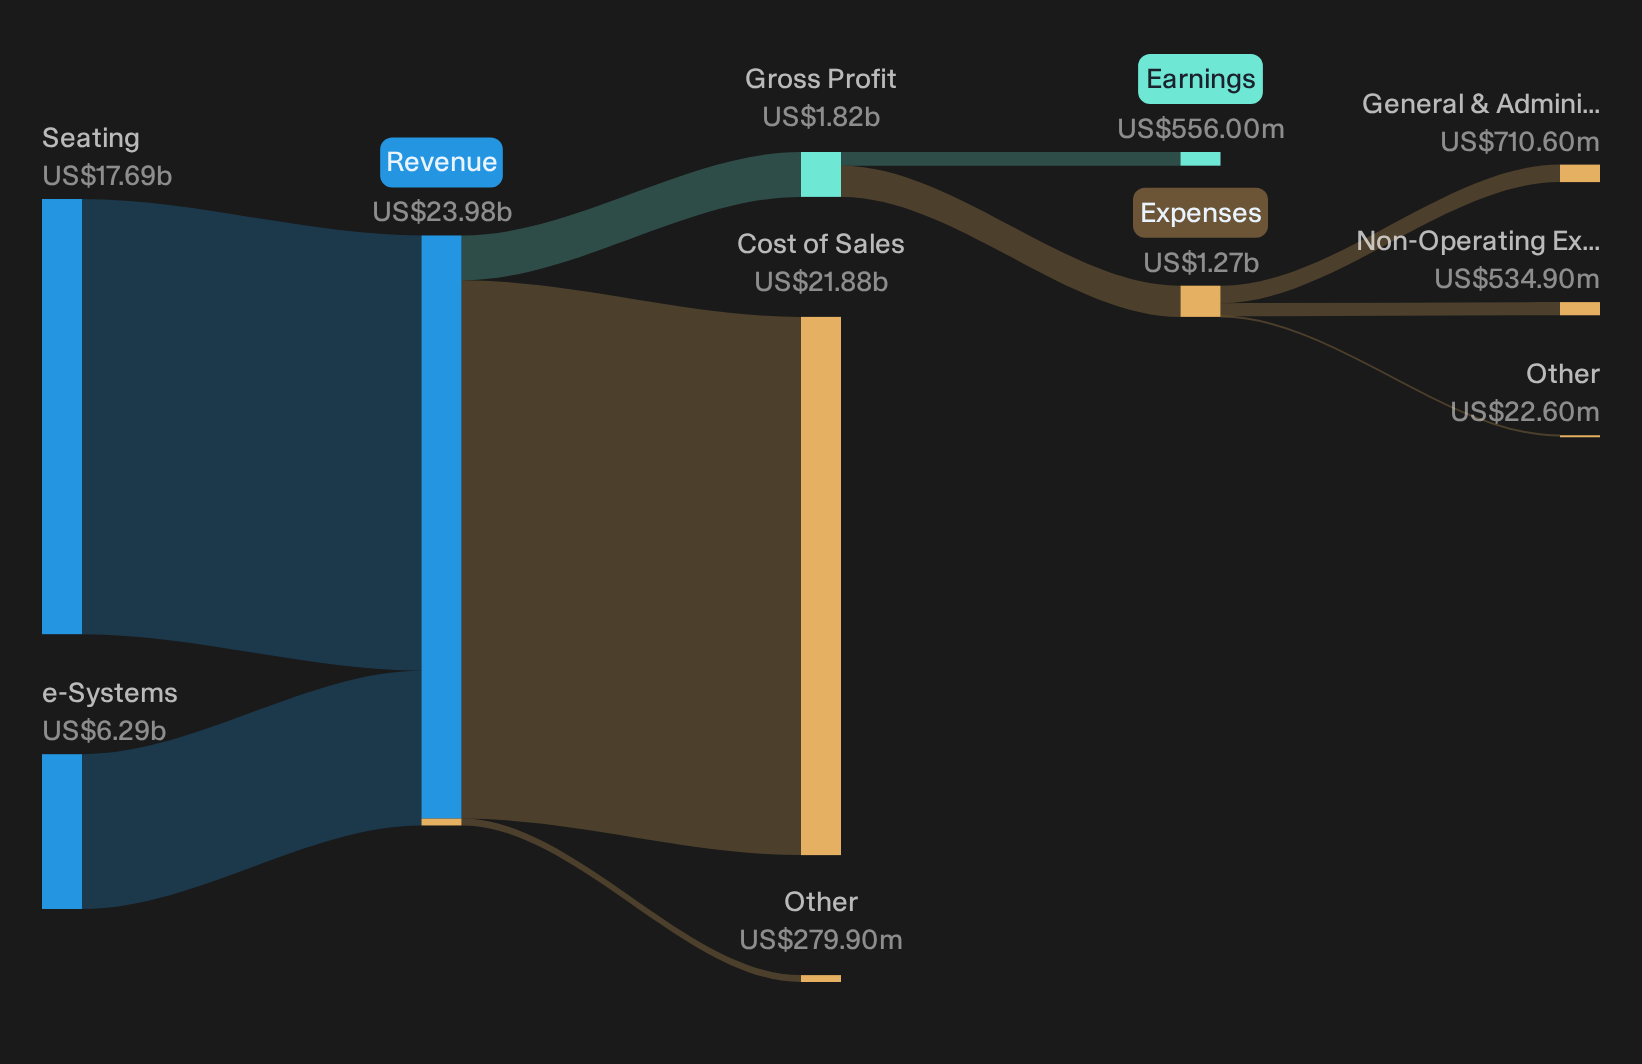
Lear is a key aluminum linked auto supplier, feeding seat frames and wiring hardware into North American factories while building a global seating and E-Systems business that generated about US$17.7b from Seating and US$6.3b from E-Systems, with a roughly US$6.1b market value.
For Lear, the aluminum story is really about how input costs and content per vehicle intersect with electrification, where the company has quietly built real leverage with global carmakers.
"Lear's recent wins of modular, electronics-rich seating and wire programs with major global EV automakers (including nearly $1 billion in E-Systems awards YTD and high interest in ComfortFlex/ComfortMax seats) position the company to benefit from growing demand for advanced vehicle electrification and connectivity, setting up higher revenue per vehicle and supporting long-term top-line growth and margin improvement."
What investors will watch most closely now is how one less visible pressure in Lear's supply chain shapes the next leg of margin progress.
That quiet pressure could be masking Lear's real earnings power, so read the full narrative for Lear to see how aluminum costs and EV content may be decoupling.
Adient (ADNT)
Adient ties into the aluminum story through the metal heavy seat frames and mechanisms it supplies to global automakers, with a roughly US$1.4b market value and about US$7.2b of revenue from the Americas, US$4.8b from EMEA, and US$3.1b from Asia.
Adient matters for this aluminum focused screen because seat structures are metal intensive, so shifts in North American aluminum pricing can directly shape what drops through from its global seating programs to profit and cash generation.
"Surging global demand for electric and smart vehicles is expected to substantially increase the need for innovative, lightweight, and tech-integrated seating. Adient's early leadership in seat content innovation, such as zero-gravity and massage solutions, creates premium content opportunities that will structurally raise revenue per vehicle and lift gross margins as the product mix shifts toward higher-value interiors."
The real swing factor is how one less visible change in its cost base interacts with that higher value content story to either widen or cap future margin gains.
That cost shift is the quiet hinge. Read the full narrative for Adient to see whether aluminum exposure is masking an accelerating earnings story or capping Adient's upside.

Seeking Alternatives Before Momentum Escapes
Fresh ideas move first. By the time they hit the headlines, early entry is gone and momentum is already flying. Scan new pockets of opportunity while it matters and look for ways to participate earlier.
- Spot under-the-radar quality and move ahead of slower capital by reviewing the 29 high quality undervalued stocks that blend strong cash flows with sturdier balance sheets.
- Consider structural demand shifts in critical materials and track miners before interest changes by scanning the curated 37 best rare earth metal stocks set.
- Identify income-oriented candidates while yields remain elevated and prices have not fully adjusted by working through the curated 6 dividend fortresses list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com