
World Gold Council: Investors see a significant increase in long positions, and gold prices rose strongly by 13% in August
The Zhitong Finance App learned that the World Gold Council published an article stating that in August, the price of gold rose strongly by 13% and closed at 4,536 US dollars/ounce at the end of the month, achieving the third-best monthly performance in the past 25 years, which is only slightly lower than 14% in December 2025. The Association's gold price attribution model shows that the rise in gold prices is mainly driven by a significant increase in investors' long positions, including strong net inflows of global gold ETFs and improvements in long positions in derivatives. The weakening dollar during the month also provided support. Since September, although the momentum of gold prices has weakened due to expectations of the Federal Reserve's interest rate hike, gold performance has gradually stabilized after the downturn was realized.
The US Treasury recently announced a treasury bond repurchase plan. The official statement is to improve liquidity. However, many people interpret it as a method of financial suppression aimed at curbing rising yields. Physical assets such as gold may continue to benefit until a credible response plan is put in place, reflecting investors' concerns that deficits and debts will continue to expand.
Dispute review: Why did the intervention cause market unease?
In August, the World Gold Council expressed opinions on the unexpected announcement of a repurchase plan by the US Treasury and the possibility that the policy may gradually move towards controlling the yield curve. On September 9, the repurchase scale will begin to increase further.
At the beginning of August, the US Treasury provided Japan with quite unusual assistance during its intervention in the foreign exchange market, which has already sparked related disputes. 4 Perhaps because this action seemed too hasty, or maybe because it followed the hawkish minutes of the US Federal Reserve meeting; or because it just happened that the size of US Treasury bonds broke through the $40 trillion mark.
In any case, the topic has been dominating the headlines ever since. Investor Stanley Druckenmiller (Stanley Druckenmiller)'s strong public rebuttal of the Treasury's intervention may also reflect broader disappointment: the market believes that in the face of more serious problems, the US government is only willing to “fix the symptoms.”
What form the intervention takes, and even who carries it out, is probably less important than how the market views this behavior. Although the US Treasury has considerable “firepower,” the Federal Reserve's “firepower” is limitless — only if it decides to step in.
Nominal yields will almost certainly be suppressed, but where will the pressure turn? If the market remains calm, the pressure may not clearly spill over; but if the market interprets the intervention as a hopeless act, then the pressure relief valve is likely to turn to a decline in real yields, widening term premiums, and a weakening dollar, or the private sector's demand for these assets is squeezed out. Real success is inseparable from a credible plan to reduce the deficit.
Historical scenario analysis method
The association selected weekly data since 2000 to examine nominal returns, real returns, term premiums, the US dollar index, and changes in the price of gold.
The association screened data according to two types of scenarios: one type is an intervention with credibility, and the other type is an intervention that weakens market confidence; the excess gold yield for the week after the intervention, and 24 weeks after the intervention occurred is counted separately (after deducting the average value of the entire sample).
Under the above two types of scenarios, the association assumes that the intervention achieves the pre-set goals, so the nominal yield screening is limited to a specific range and remains “anchored”.
The differences are reflected in the internal driving composition: changes in yield are due to changes in term premiums; changes in real interest rates are accompanied by rising inflation compensation; and dollar fluctuations caused by capital outflows.
Scenario 1: Interventions with credibility
Under this scenario, market financing concerns were mitigated: real yields remained flat or declined slightly, and term premiums narrowed. Although the fiscal deficit is still at wartime levels, concerns about inflation have not dissipated, so real returns have weakened slightly compared to nominal returns. Fluctuations in all remaining variables are limited to the standard deviation range, which may occur when the market calmly accepts intervention policies.
Scenario 2: Interventions that weaken market confidence
This scenario is not a strict mirror reversal. The nominal rate of return is controlled as described above, but for the remaining three indicators, the screening conditions are set to fluctuate up to three standard deviations. As concerns about inflation heats up and real yields decline, term premiums are no longer narrowing; capital is seeking outward allocation, leading to the weakening of the dollar. The key to determining that this scenario is a financial depression rather than an ordinary safe-haven week market is that the above factors work together and are not driven by a single variable.
As mentioned earlier, term premiums, actual returns, and even the US dollar index calculated by the model may be distorted. In this context, investors' willingness (or lack of will) to hold assets is not reflected in prices, but rather in capital flows.
Variable trend deduction under two thematic hypotheses intervention scenarios
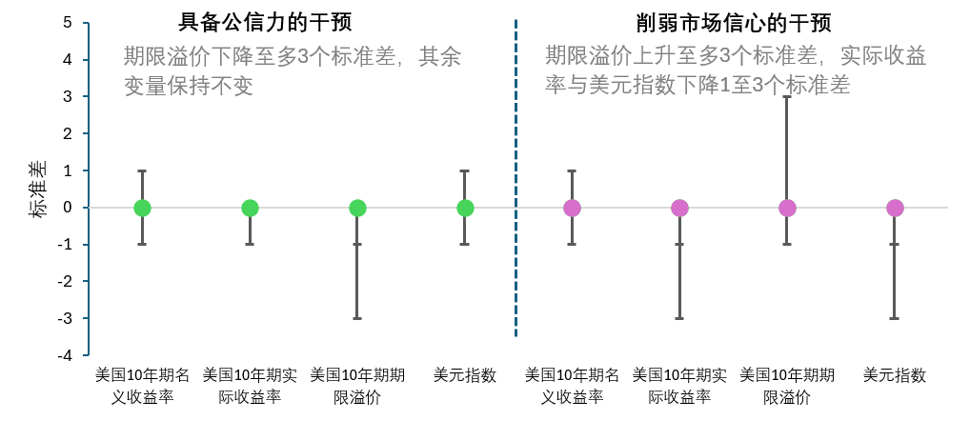
Analysis results
It is rare for nominal returns to remain anchored while other drivers change. Out of a total of 1,443 weekly samples since 2000, only 30 weeks were in line with credible intervention scenarios, and 20 weeks were in line with intervention scenarios that weakened market confidence.
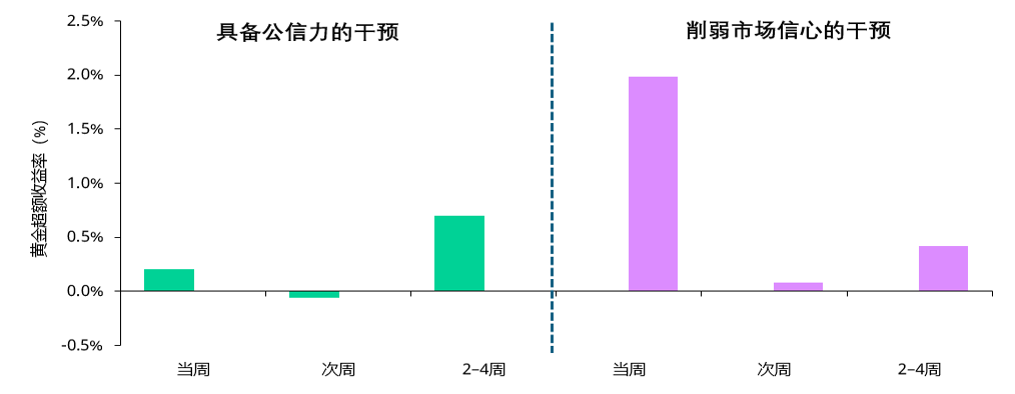
Unsurprisingly, gold performed far better in an intervention scenario that weakened market confidence than a credible intervention scenario. The decline in real yields and the weakening dollar are usually the core drivers of gold's short-term returns. And this just highlights the value of gold as a hedge against these risks.
Formal success in intervention is not necessarily bad for gold. This policy, which is only superficial, will not resolve the deep-seated root causes, and may further worsen the problem through moral risk. The narrowing of the term premium alone is not enough to erode the excess yield of gold.
However, there is an alarming sign: in a sample of credible intervention scenarios, the two time points where gold returns showed the weakest performance — May 2014 and July 2015 — coincided with the US fiscal deficit falling from 4% to about 2.5% of GDP within 18 months. The reference significance of the two sets of observation samples is very limited, but even if the probability of occurrence is low, imposing substantial financial constraints while implementing maximum yield control still poses a short-term risk for gold.
Based on historical data, the simulation hypothetical analysis results of the week the intervention occurred in the week
Summarize
At the end of the day, the core is whether the market approves the policy. If not recognized by the market, gold may benefit; if recognized by the market, one of the factors supporting the strong gold market for many years will temporarily disappear. The World Gold Council believes that due to established government spending and tax commitments, it is very difficult to develop such market confidence.
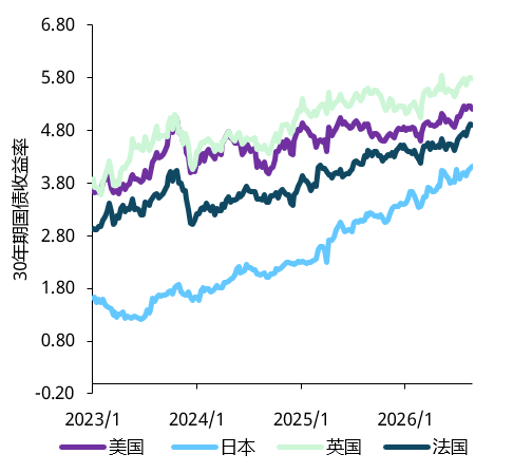
Although the previous analysis focused on the US, rising yields (especially in the context of high debt burdens) are already a global issue. It's like a whack-a-mole game: solving a problem, but causing new problems elsewhere, because investors will find alternative ways to allocate their funds.
30-year Treasury Bond Yield
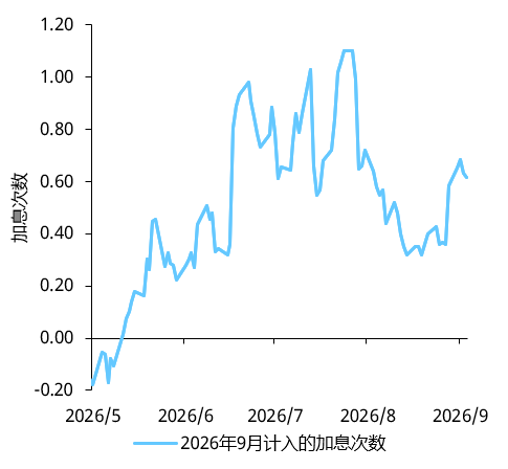
Next, the focus of the market's attention is the rising possibility that the Federal Reserve will raise interest rates in September.
Expected number of interest rate hikes based on federal funds futures
Looking to the future
It is unclear what effect interest rate hikes can achieve; from a theoretical point of view, interest rate hikes should be bad for gold.
The Association has previously analyzed some of the potential transmission logic: what really matters is not the change in yield itself, but the signals transmitted behind the change.
If interest rate hikes can restore policy credibility and flatten the yield curve, it will overturn the simple rule of thumb that “interest rate hikes will inevitably hurt gold.”