
Earnings Beat Could Be A Game Changer For Ralph Lauren Stock (RL)
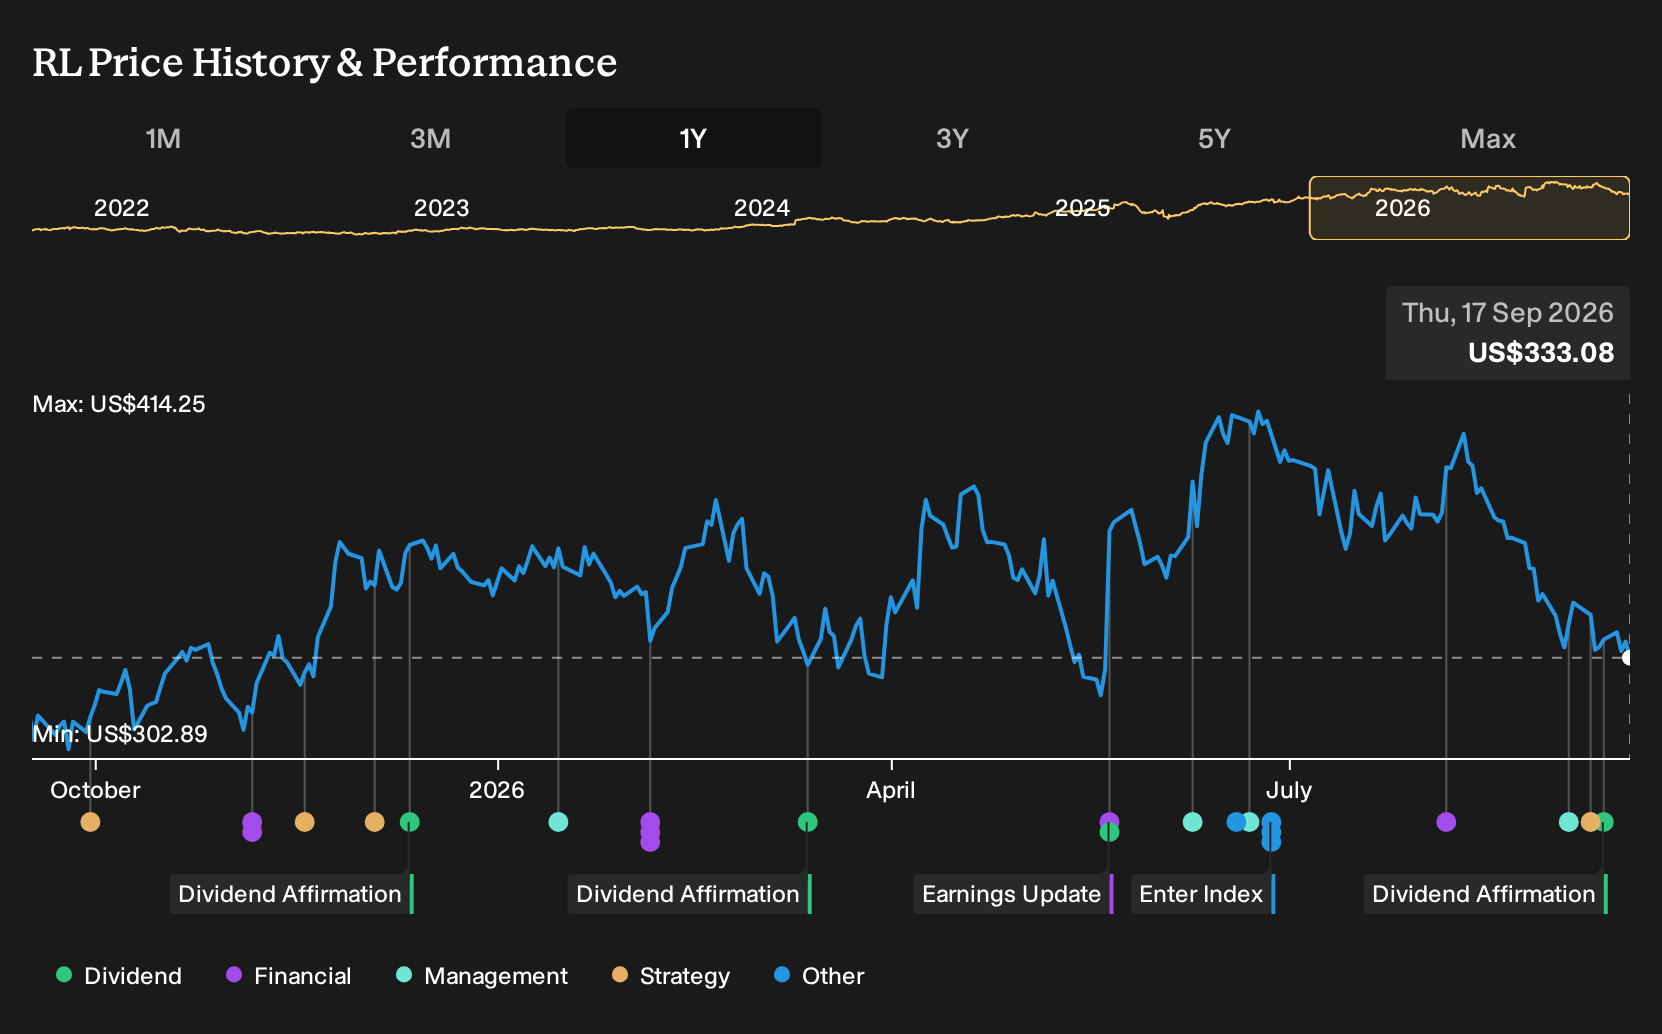
- Ralph Lauren announced a quarterly dividend of US$1.00 per share, payable on October 9, 2026, to shareholders of record on September 25, 2026, and recently reported quarterly revenue that surpassed analyst expectations alongside higher revenue guidance.
- The combination of stronger than expected sales, a raised outlook, and an ongoing capital return via dividends highlights management’s focus on both expansion and disciplined shareholder returns.
- This article examines how Ralph Lauren's investment narrative is shaped by stronger quarterly results and raised revenue guidance from management.
Compare Ralph Lauren’s mix of income, guidance, and brand strength with a curated 29 high quality undervalued stocks that are pairing solid fundamentals with potentially mispriced market expectations.
Ralph Lauren Investment Narrative Recap
For a shareholder in Ralph Lauren, the core belief is that a global premium lifestyle brand can keep expanding while holding pricing power and improving efficiency. The recent quarter with higher revenue guidance supports that operating story. The near term swing factor is whether direct to consumer and Asia can offset planned wholesale exits and a softer backdrop in Europe.
The biggest immediate risk is that cost inflation, tariffs, and more cautious consumers push the brand back toward heavier discounting, which would pressure margins and inventory quality. The new US$1.00 quarterly dividend appears consistent with the existing capital return approach rather than a change in the operating outlook.
The dividend affirmation is the most directly investable update in this context. A US$1.00 quarterly payout indicates that Ralph Lauren’s board is comfortable maintaining cash distributions while funding international expansion, digital investment, and category builds in areas such as handbags and women’s apparel. That mix matters if long term value creation depends on both steady reinvestment and cash returns.
For potential catalysts, this dividend sits alongside raised revenue guidance and improving net margins, which together keep attention on execution in Asia and digital channels. The risk side of that equation remains clear. Management is contending with inventory that previously grew faster than sales, planned exits from up to 100 wholesale doors, and a macro backdrop that could test pricing power.
Ralph Lauren Forecasts and Market Expectations
Ralph Lauren's narrative projects US$9.7b revenue and US$1.2b earnings by 2029. This aligns with analysts assuming 5.0% yearly revenue growth and an earnings increase of about US$217m from US$982.9m today.
Uncover how Ralph Lauren's fair value indicates a 34% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate narrative leans hard on competition risk. It assumes that digital native labels and heavier promotions cap Ralph Lauren’s pricing power, which is why the lowest analysts were only penciling in about US$9.6b of revenue and US$1.2b of earnings by 2029. Those estimates came before the dividend affirmation and Korea partnership, so some views may shift. Use that gap between stories as a prompt to compare several angles before you decide what this stock’s future might look like for you.
Explore 3 other Ralph Lauren fair value estimates, including one that suggests it could be worth just $339.40.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ralph Lauren research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ralph Lauren. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ralph Lauren's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ralph Lauren?
Ralph Lauren might be your starting point, but building a resilient portfolio usually means lining up a few different sources of return and risk. Use the Simply Wall St screener to hunt for other businesses that match your income goals, quality bar, or appetite for volatility.
- If you want income to do more of the heavy lifting, filter for companies offering robust cash returns with a 6 dividend fortresses that could complement a position in Ralph Lauren.
- For those who care most about balance sheet strength and resilient fundamentals, sort for companies on our list of solid balance sheet and fundamentals (23 results) and see which ones fit your risk tolerance.
- If you are hunting for less crowded opportunities, scan through a 16 high quality undiscovered gems that might deserve a place on your watchlist next to Ralph Lauren.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com