
Leadership Shake Up Might Change The Case For Investing In Celestica Stock
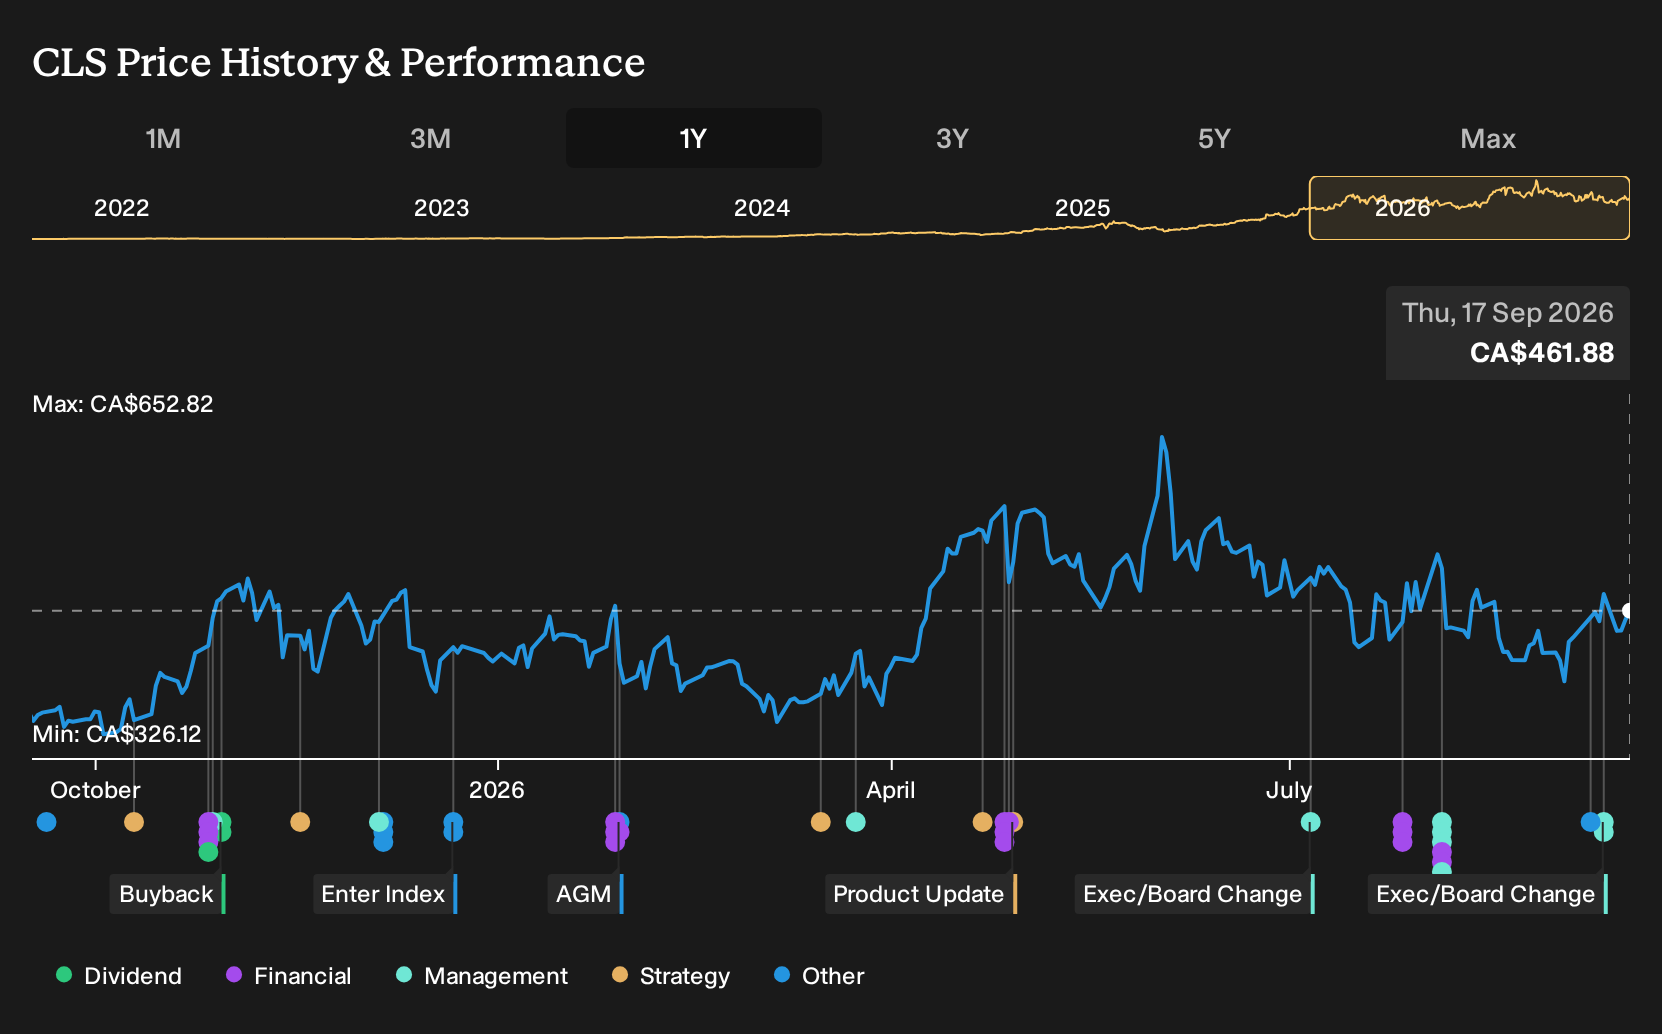
- Celestica has restructured its leadership, moving long-time CFO Mandeep Chawla into a new Group President, Global Markets role and appointing Todd Ankenmann as CFO. Both roles are effective from October 1, 2026 and are paired with revised salaries, incentives and equity awards.
- The creation of a Group President, Global Markets position signals a push to tighten commercial execution and global expansion. This matters for how Celestica manages rising demand, customer concentration and the operational load tied to advanced networking and AI programs.
- We will now look at how Celestica's investment narrative could be influenced by Chawla's move into the new global markets role.
Scan how Celestica’s leadership shake-up compares with other potential breakouts by reviewing our curated list of 9 high quality undiscovered gems across similar high-complexity manufacturing and technology supply chain players.
Celestica Investment Narrative Recap
To own Celestica, you need to be comfortable with a business that is tightly wired into hyperscaler AI and networking build outs, with CCS accounting for most of the revenue and earnings power. The short term story still rests on timely 800G and future 1.6T program ramps, as well as efficient use of its global manufacturing footprint in Mexico, Thailand and the U.S.
This leadership reshuffle looks more like plumbing than a new thesis. The biggest near term swing factor stays the same: execution on complex customer programs and capacity expansion. The key risk also does not change: heavy dependence on a few large cloud clients that could reset orders or slow capex.
The appointment of Mandeep Chawla as Group President, Global Markets is the announcement that matters most here. His remit over commercial execution and market expansion ties directly into the AI and cloud demand that underpins Celestica’s current program pipeline and the expected ramp in higher value design and rack level work.
For you as a shareholder, this structure concentrates responsibility for two key levers: winning and scaling hyperscaler and digital native business, and broadening exposure in higher margin ATS verticals such as aerospace, industrial and healthtech. The upside case rests on clean execution. The risk is that complexity increases just as large customers reassess spending.
Celestica’s forecast narrative points to revenues of $41.7b and earnings of $2.7b by 2029, based on analyst models. That path assumes 38.8% yearly revenue growth and an earnings increase of about $1.6b from $1.1b today.
Uncover why Celestica's fair value indicates a 47% potential upside to its current price before that gap closes.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between roughly 676 and 765, which indicates tight but not uniform conviction on Celestica. Those views sit alongside real execution risk related to hyperscaler concentration and program ramps. Use that contrast to test your own thesis and explore alternative viewpoints.
Explore 2 other Celestica fair value estimates, including one that suggests it could be worth just CA$676.25!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely result from following the herd, so rely on your own analysis.
- A great starting point for your Celestica research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Celestica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Celestica's overall financial health at a glance.
Looking For More Investment Ideas Beyond Celestica?
If this Celestica update sharpened your thinking, use that momentum to widen your opportunity set with a few focused stock screens that line up with different risk and income preferences.
- For investors who want potential mispricings with solid fundamentals behind them, start with a curated pool of 3 high quality undervalued stocks that already clear quality and financial strength checks.
- If capital preservation ranks high on your checklist, narrow your watchlist to a 8 resilient stocks with low risk scores that screen well on balance sheet resilience and volatility.
- Income focused readers who care about consistency as much as yield can zero in on a shortlist of 1 dividend fortresses that pair higher payouts with underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com