
Ondas (ONDS) Lifts Outlook As Revenue Growth Puts Undervalued Narrative Back In Focus
Ondas (ONDS) moved into focus after reporting a significant revenue increase and lifting its full-year 2026 outlook, pointing to the impact of acquiring GATE Technologies and Bron Technologies on its electronic fuzing capabilities.
Recent trading shows a mixed picture for Ondas. The 1-day share price return of 2.64% and 7-day gain of 1.93% follow a period where the 30-day move is down 18.43% and the year-to-date share price return is lower by 32.94%. At the same time, the 1-year total shareholder return sits at 11.97%, and the 3-year total shareholder return is very large, suggesting long-term holders have seen substantial upside while short-term momentum has faded.
Scan how Ondas compares with other defense and robotics players by reviewing the hand picked 95 robotics and automation stocks that are also tied to unmanned systems and automated security technology.
Ondas has a long term return profile that looks very different from its recent slide, which raises a simple question. Are you seeing business fundamentals being repriced, or a swing in sentiment that valuation can clarify next?
Most Popular Narrative: 63% Undervalued
Ondas is framed by the most followed narrative as materially undervalued, with a fair value of $20.13 versus the last close at $7.39. This puts the focus squarely on how forecast growth and margins could support that gap.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $1.0 billion, earnings will come to $114.4 million, and it would be trading on a PE ratio of 136.9x, assuming you use a discount rate of 8.6%.
Given the current share price of $11.97, the analyst price target of $20.12 is 40.5% higher. Despite analysts expecting the underlying business to decline, they seem to believe it's more valuable than what the market thinks.
See why 131 investors see Ondas as 63% undervalued.
Result: Fair Value of $20.13 (UNDERVALUED)
Still, Ondas faces meaningful pressure if operating expenses stay high and revenue growth assumptions fall short, or if future funding needs dilute existing shareholders.
Find out about the key risks to this Ondas narrative.
Another View On Ondas Valuation
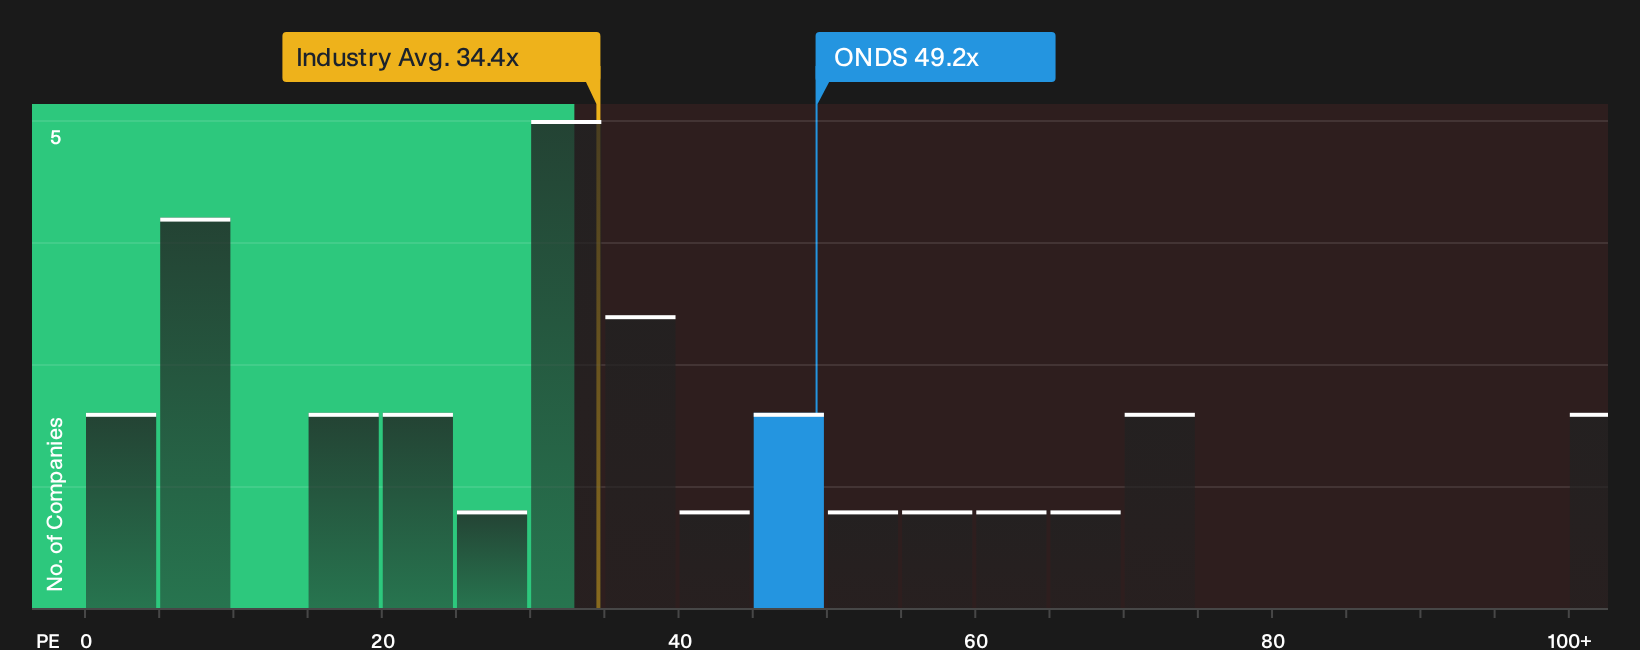
While the narrative and DCF style fair value work point to Ondas looking undervalued, the simple P/E check tells a different story. At 49.2x earnings versus 34.4x for the US Communications group and a fair ratio of 31.6x, the stock trades at a clear premium. How comfortable are you paying above both peers and that fair ratio if growth or margins fall short?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Ondas is clearly split, so consider acting promptly and review the full picture for yourself by weighing both the upside drivers and the concerns flagged in the 3 key rewards and 4 important warning signs.
Looking for more Ondas investment ideas?
If Ondas has your attention, do not stop here. Broaden your watchlist with a few focused stock shortlists and give yourself more options on the table.
- Target resilient opportunities by scanning a 30 resilient stocks with low risk scores that could help steady your portfolio when single stocks move sharply.
- Hunt for high quality potential bargains using a 16 high quality undiscovered gems that flags companies with strong fundamentals that many investors may still be overlooking.
- Build a sturdier core by reviewing a list of solid balance sheet and fundamentals (23 results) that highlights businesses with healthier finances supporting their long term plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com