
SiTime (SITM) Stock Looks Fully Priced Despite Its 462% Run
SiTime has seen its share price climb sharply in recent years, and the latest pullback puts fresh attention on whether today's valuation still lines up with the sales it generates. With that kind of move in the rear-view mirror, the question for investors is how much of the story is already reflected in the current US$598.60 price tag.
- Over the past 3 years the stock has delivered a very large gain of about 4.6x, which raises the stakes on whether the revenue base is strong enough to support that kind of re-rating.
- The acquisition of Renesas Electronics' timing business, with an expected US$300m in added revenue over the coming year, can reshape how investors think about SiTime's future sales scale and the price they are paying for each dollar of that top line.
- Your read on SiTime is one view; the desks covering it have another. See what analysts think SiTime's shares could be worth.
The stock's next move may depend on whether SiTime's current market value is well aligned with its sales today and the sales investors expect it to deliver over time.
If you are weighing SiTime against other ways to play precision chips and AI infrastructure, it helps to line it up next to 89 AI infrastructure stocks.
Does SiTime Look Pricey on Sales?
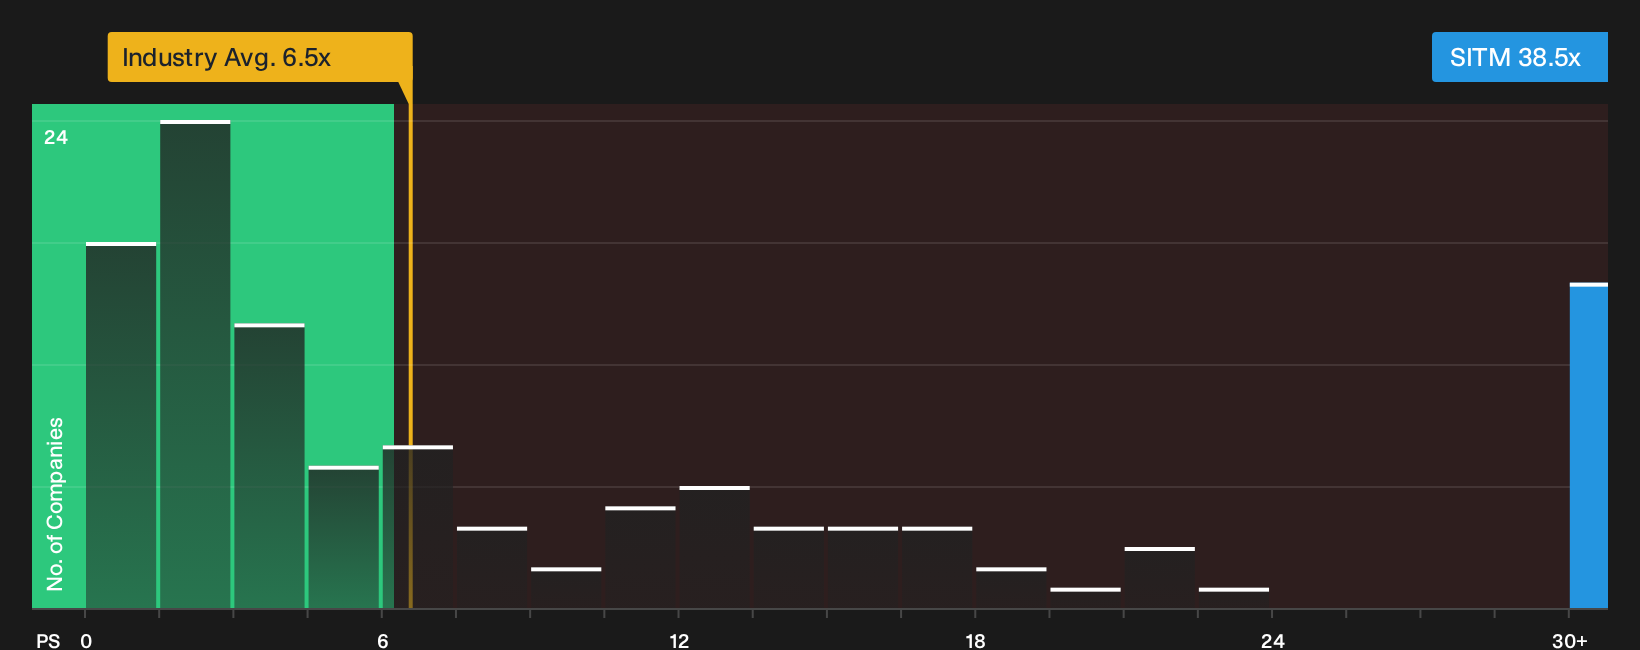
P/S is a useful lens for SiTime because the story investors are paying for is still much more about revenue scale than bottom line earnings. On that yardstick, the stock trades on a P/S of about 38.5x, which is far above the broader semiconductor industry average of roughly 6.5x and still well ahead of the peer group near 12.5x. That kind of gap means each dollar of SiTime sales is being valued far more richly than sales at many other chip designers.
The valuation model that blends SiTime's growth profile, margins, size and risk points to a lower multiple as a reasonable anchor, so the current P/S points to the shares screening as overvalued on this framework. Because the Renesas timing acquisition brings in an expected US$300m of extra revenue over the next year, the market is clearly already placing a high price on that larger sales base rather than waiting for it to show up in reported figures. If you are weighing up whether that premium still makes sense for your own portfolio, it helps to look at how the current P/S compares directly with the suggested fair range. Explore the numbers behind SiTime's P/S valuation.
The SiTime Narrative: What Would Justify Today's Price?
Narratives for SiTime pick up where the valuation puzzle leaves off by spelling out what kind of future growth, margin profile and earnings power would need to materialise for the current share price to look either stretched or conservative. Each scenario anchors a fair value to a particular mix of potential catalysts and key risks for SiTime, so you can track over time which version of events appears to be unfolding on Simply Wall St's Community page.
One of the top community narratives on SiTime: 33% undervalued
"SiTime's premium, differentiated solutions are increasingly preferred for next-generation IoT, automotive autonomy, and electrification applications, paving the way for significant…"
Discover why this Narrative puts SiTime at 33% undervalued.
One more SiTime factor to check before making a move
The last piece to weigh is how professional analysts currently map out SiTime a few years from now, because those expectations offer a different lens to compare with today's pricing. Explore where analysts expect SiTime to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com