
Freshpet (FRPT) Stock May Be Fully Priced After A 59% Five Year Fall
Freshpet has given investors a mixed ride, with the share price at US$61.57 after a run that includes both double digit gains and double digit declines over different time frames. That uneven record puts the spotlight on a simple question for you as a shareholder or would be buyer: whether the current price can be explained by the earnings the business is producing.
- Over the past 5 years the stock has fallen 59.2%, which makes the current valuation argument much more about what the earnings power of Freshpet can support rather than where the share price has been.
- The business model relies heavily on scaling its refrigerated pet food footprint, which can influence margins and the path of future profits that ultimately need to justify the earnings multiple investors are paying today.
- The analysts covering Freshpet have run their own numbers. See what analysts think Freshpet's shares could be worth.
For investors, the debate is whether Freshpet's current share price lines up with what its earnings suggest the business is worth.
If you want more context around whether Freshpet's earnings justify its current price, it can help to compare it with a wider set of companies screened for 29 high quality undervalued stocks
Is Freshpet Getting Expensive on Earnings?
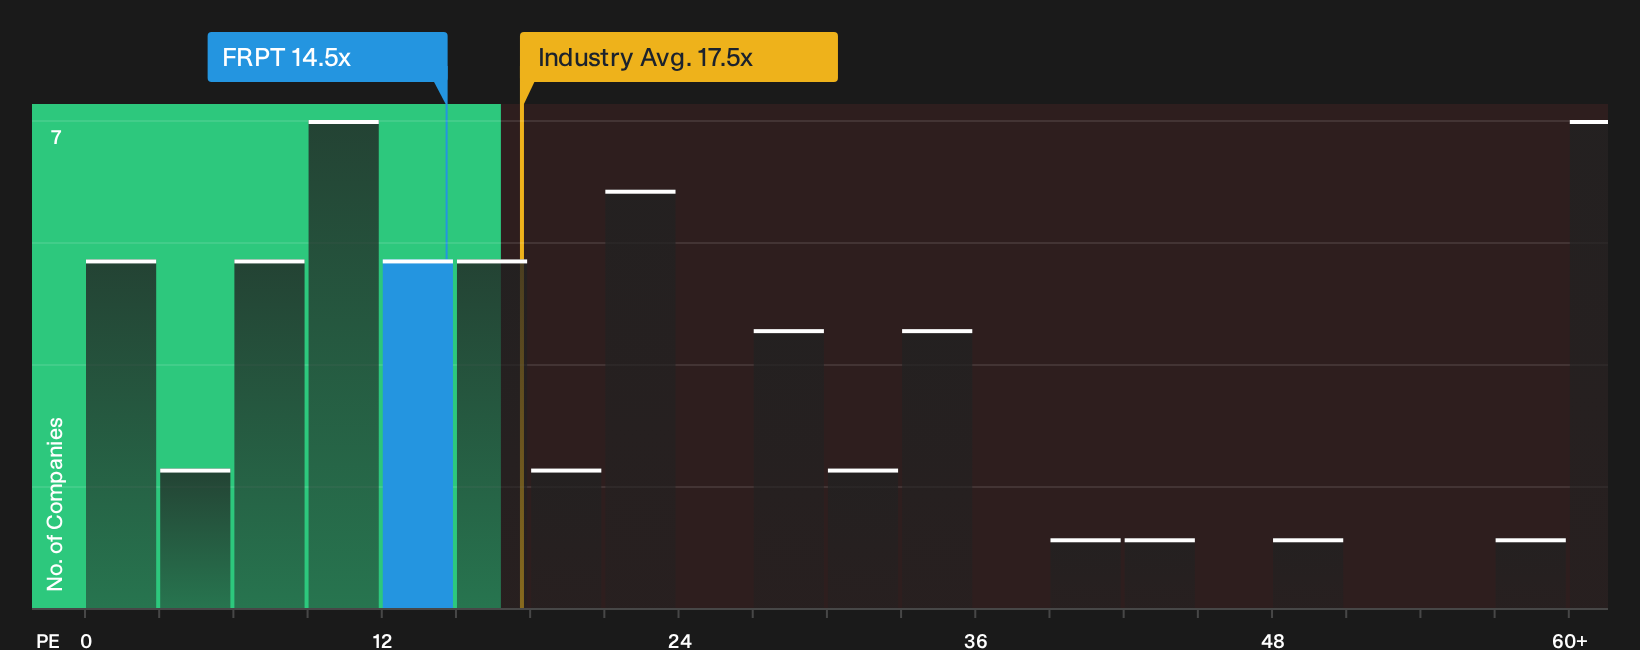
The P/E ratio suits Freshpet because earnings are the anchor most investors look to when judging how much they are paying for each dollar of profit. At the current price, the stock trades on a P/E of 14.5x, which is below both the peer group on 16.7x and the wider food sector at 17.5x. That gap indicates the market is applying a lower earnings multiple to Freshpet than to many comparable food producers.
A fair multiple implied by Freshpet’s own profile of growth expectations, profitability, size and risk sits above the current 14.5x. As a result, the share price screens as overvalued against that tailored benchmark even though it trades below the broad industry average. The key question for you is whether Freshpet’s earnings quality and future profit potential are strong enough to support paying more than this model suggests is justified on fundamentals. Explore the numbers behind Freshpet's P/E valuation.
The Freshpet Narrative: What Would Justify Today's Price?
Freshpet Narratives on Simply Wall St pick up where the P/E puzzle leaves off by mapping out what kind of future growth, margins and earnings paths would need to play out for the stock to be worth materially more or less than it is today, and they sit on the platform's Community page. Each one treats Freshpet's fair value as a thesis about the business that you can revisit later and see how it holds up against new information.
One of the top community narratives on Freshpet: 12% undervalued
"Weakening pet adoption trends and consumer trade-down are suppressing Freshpet's growth prospects and limiting its path to higher revenues..."
Discover why this Narrative puts Freshpet at 12% undervalued.
Freshpet's valuation is only part of the story
Before relying too heavily on where Freshpet trades on earnings, it helps to know that independent checks have flagged specific issues with the business that deserve your attention. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com