
China Steel Association: Steel prices in the domestic market stopped falling and stabilized in August
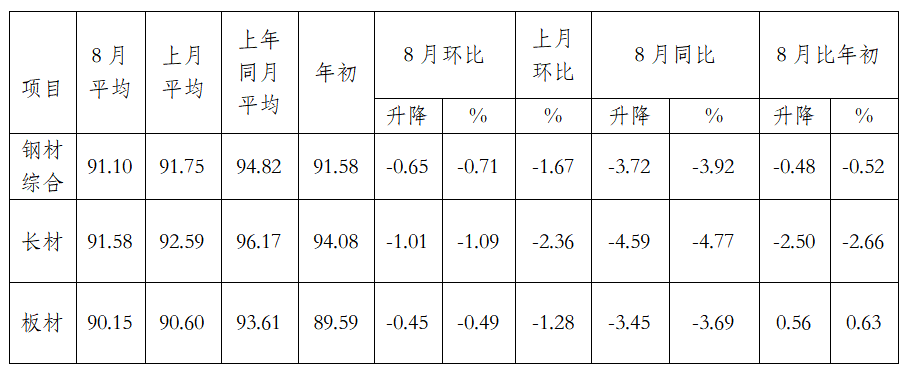
The Zhitong Finance App learned that the China Steel Association published an article stating that in August, the domestic steel market stopped falling and stabilized against the backdrop of seasonal demand recovery expectations gradually heating up, cost support weakened, and inventory pressure eased. Entering September, the traditional “Golden Nine” did not arrive as scheduled, and domestic steel market prices fluctuated in a narrow range. According to monitoring by the Steel Association, in August, the CSPI average was 91.10 points, down 0.65 points from month to month, or 0.71%; down 3.72 points year on year, or 3.92%. Among them, the average value of the CSPI Long Lumber Index was 91.58 points, down 1.01 points month-on-month, or 1.09%; down 4.59 points year-on-year, or 4.77%. The average value of the plate index was 90.15 points, down 0.45 points from month to month, or 0.49%; down 3.45 points year on year, or 3.69%.
As of the end of August 2026, the China Steel Price Index (CSPI) was 92.10 points, up 1.03 points from month to month, up 1.13%; up 0.23 points from the end of the previous year, or 0.25%; down 1.92 points year on year, or 2.04%.
In January-August, the CSPI average was 92.26 points, down 1.47 points year on year, or 1.57%.
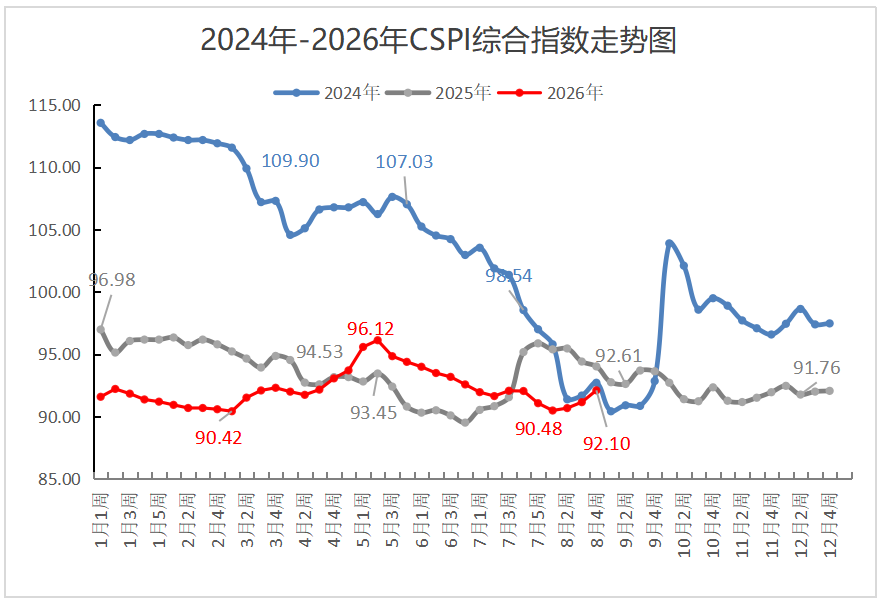
(1) At the end of the month, the prices of long and plate materials both increased month-on-month, and the month-on-month increase was significant for long materials
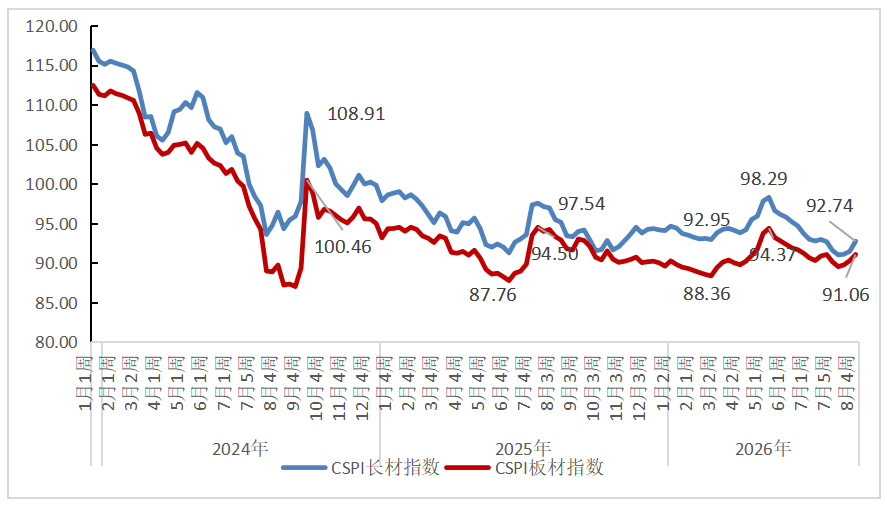
By the end of August, the CSPI long wood index was 92.74 points, up 1.17 points from month to month, up 1.28%; the CSPI plate index was 91.06 points, up 0.93 points from month to month, up 1.03%; compared with the same period last year, the CSPI long wood and plate index decreased 2.39 points and 1.83 points respectively, down 2.51% and 1.97%, respectively.
In January-August, the average value of the CSPI long wood index was 94.00 points, down 1.65 points year on year, or 1.72%; the average value of the plate index was 90.60 points, down 1.50 points year on year, or 1.63%.
Table of changes in China Steel Price Index (CSPI)
CSPI long timber and plate price index chart
(2) Mainly a decrease in the average monthly prices of the eight major steel varieties
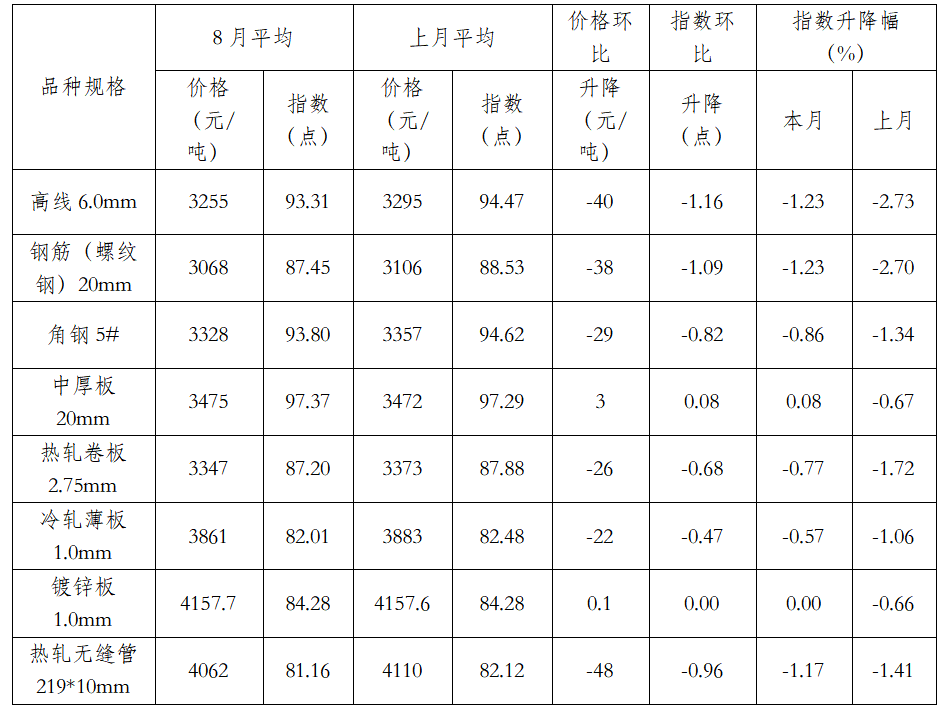
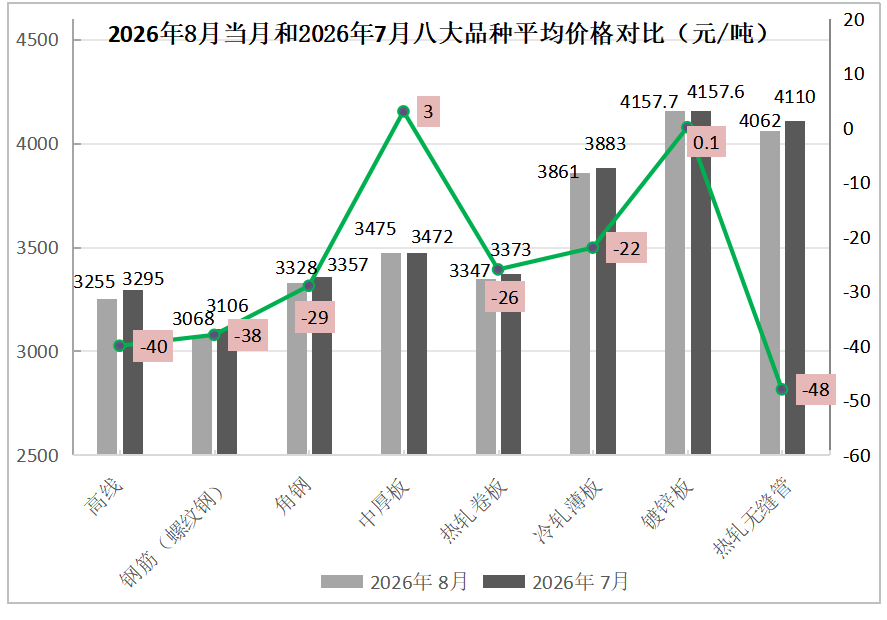
In August, the average price of the eight major steel varieties monitored declined steadily except galvanized sheet and medium to thick plate. The price of the middle and high line of the long wood variety dropped significantly, by 40 yuan/ton, and the index drop was 1.23%. Among the plate varieties, the price of hot-rolled coils dropped significantly, by 26 yuan/ton. The index drop was 0.77%. Among the eight major varieties, the price of seamless pipes dropped the most, by 48 yuan/ton, and the index fell by 1.17%.
Table of changes in prices and indices of major steel varieties
(3) Recently, China's steel price index fluctuated in a narrow range
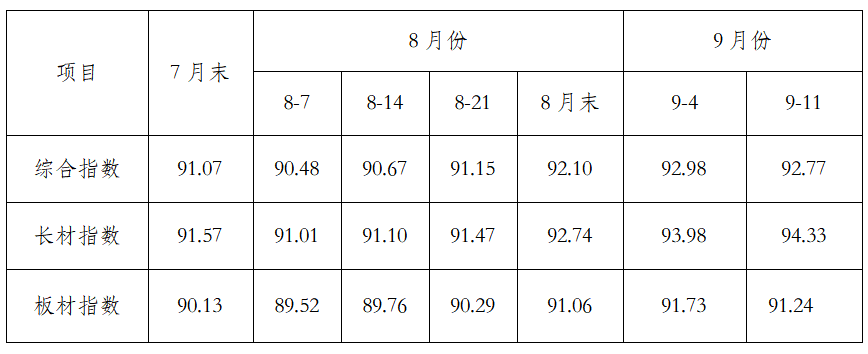
In January-February, domestic steel market prices showed a “steady, moderate, weak, and narrow fluctuation” trend. It fluctuated upward in March-April. By the end of April, China's steel price index surpassed the same period last year for the first time. In May, the domestic steel market emerged from a sharp upward and downward trend. In June, demand contracted seasonally, inventories began to accumulate, the off-season characteristics of the industry became more apparent, and overall domestic steel market prices fell under pressure. In July, the whole country fully entered the main flood season. The domestic steel market continued to weaken, and prices fluctuated downward. In August, the domestic steel market stopped falling and stabilized against the backdrop of seasonal demand recovery expectations gradually heating up, cost support strengthened, and inventory pressure eased marginally, and emerged from a “hold back first, then recover from a low level” trend. Entering September, there were many rounds of increases in coke, and the domestic steel market switched from a “cost-driven rise” in August to a standstill where “cost support and demand fall short of expectations”, and prices fluctuated in a narrow range.
CSPI Price Index Change Chart for Recent Months and Weeks
(4) The average steel price index in all regions continued to decline month-on-month
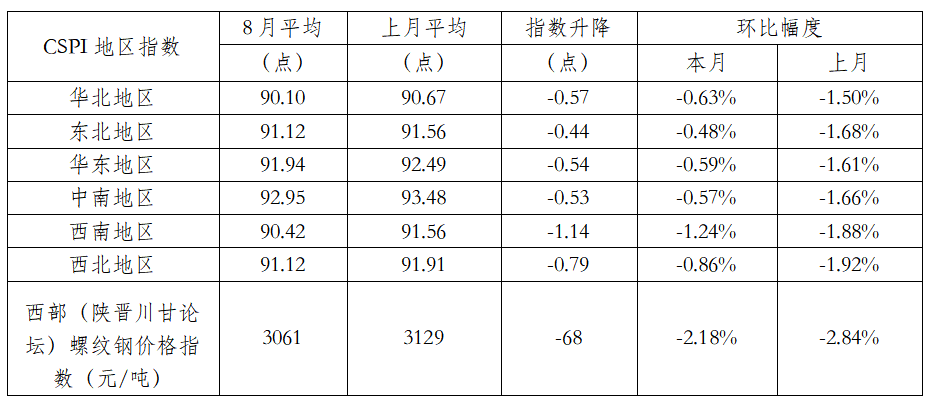
By region, the average value of the CSPI steel price index for the six major regions of the country fell month-on-month in August, and the decline was narrower than last month. Among them, the biggest decline was in the southwest region, where the decline was 1.24%, and the Northeast region saw the smallest decline of 0.48%.
In August, the average price index for rebar in western China (Shaanxi Jinchuan Gan Forum) was 3061 yuan/ton, down 2.18% from the previous month.
CSPI steel price index change table by region
Analysis of factors changing steel prices in the domestic market
(1) The main steel industry continues to weaken
In January-August, the country's fixed asset investment (excluding rural households) was 29309.2 billion yuan, down 7.2% year on year. The decline continued to expand, and downward pressure on the investment side continued to increase. Among them, infrastructure investment fell 4.0% year on year, an increase of 0.4 percentage points over January-July. Infrastructure investment continued its negative growth trend, and the traditional “steady growth” engine continued to weaken the supporting role of the traditional “steady growth” engine on steel demand. Investment in manufacturing fell 2.3% year on year in January-August. The decline was 0.6 percentage points higher than in January-July, continuing the downward trend.
In August, the manufacturing purchasing managers' index was 49.8%, up 0.6 percentage points from the previous month. The sentiment level rebounded, but it was still in a contraction range. The manufacturing production index and the new orders index were 50.4% and 50.6% respectively, up 0.5 and 2.1 percentage points from the previous month. Production and market demand of manufacturing enterprises both expanded compared to the previous month, and both the production index and the new orders index were on the 50 boom and dry line. In terms of industrial value added, in January-August, the value added of industries above the national scale increased by 5.3% year-on-year, the same growth rate as in January-July.
According to an analysis by the China Association of Automobile Manufacturers, automobile consumption subsidies continued to be upgraded in many places in August, car companies' promotional activities were active, and automobile production and sales increased month-on-month and declined slightly year-on-year. In January-August, automobile production and sales reached 20.315 million units respectively, down 3.8% year on year. As an important downstream of sheets, automobiles have weakened production and sales directly suppressing demand for sheets.
Looking at the real estate industry, the decline in the three core indicators of real estate widened simultaneously, and the downward trend continued. In January-August, the country's real estate development investment fell 19.9% year on year, and the decline further widened; in January-August, the area of new housing construction fell 24.8% year on year, an increase of 0.8 percentage points over January-July; in January-August, the sales area of newly built commercial housing fell 12.1% year on year, and the decline was 0.3 percentage points higher than in January-July. Overall, the decline in the three core indicators of investment, new construction, and sales increased simultaneously, and the depth of new housing starts grew negatively, indicating that the real estate market is still bottoming out, and the deep contraction of new construction directly suppresses demand for long materials such as rebar.
In summary, from January to August of this year, China's national economy was generally running smoothly, but the “demand-side weakening” trend in the steel industry has not changed. Infrastructure investment continued to grow negatively, and the decline continued to expand, indicating that the transmission efficiency of financial resources from disbursement to the formation of physical workload still needs to be improved. Investment in manufacturing changed from positive growth at the beginning of the year to continued negative growth, and the driving effect of equipment renewal policies is weakening marginally. The deep contraction in real estate investment is still the biggest drag on steel demand. Although leading indicators such as manufacturing PMI and new orders index showed a marginal recovery in August, this recovery is more reflected in high-tech manufacturing and other fields, and has yet to effectively drive steel demand. Against the backdrop of continued weakening demand for real estate and infrastructure, the basic contradiction between “strong supply and weak demand” in the industry is still prominent.
(2) The apparent decline in crude steel consumption in January-August was greater than the decline in production
According to the latest data released by the National Bureau of Statistics, in January-August, China's crude steel production was 651.85 million tons, a year-on-year decrease of 3.1%; in August, the average daily crude steel output was 2.407 million tons, down 3.0% from the previous month. In January-August, China's pig iron production was 563.4 million tons, a year-on-year decrease of 3.1%. In August, the average daily production of pig iron was 2.182 million tons, down 1.0%; in January-August, China's steel production was 95.75 million tons, down 1.7% year on year; in August, the average daily steel output was 3.702 million tons, down 1.5% from the previous month. Judging from monthly data, the average daily production of crude steel, pig iron, and steel declined across the board in August, reflecting an increase in the willingness of steel mills to actively reduce production against the backdrop of pressure on profits and weak demand.
Looking at imports and exports, China's steel imports and exports increased in average year-on-year in January-August. From January to August, a total of 75,149 million tons of steel were exported, a year-on-year decrease of 2.344 million tons, a decrease of 3.0%. The average price was 705.9 US dollars/ton, up 6.9 US dollars/ton year on year, an increase of 1.0%. In January-August, a total of 3.574 million tons of steel were imported, a year-on-year decrease of 421,000 tons, a decrease of 10.5%. The average price was 1841.2 US dollars/ton, an increase of 7.5% over the previous year.
Based on this calculation, in January-August, the country's apparent consumption of crude steel equivalent was 561.69 million tons (excluding steel billets), a year-on-year decrease of 4.1%. The apparent decline in crude steel consumption was 1 percentage point higher than the decline in production. Steel mills cut production less rapidly than demand declined, and the conflict between supply and demand deepened further.
(3) Differentiation in average price trends for raw fuel types
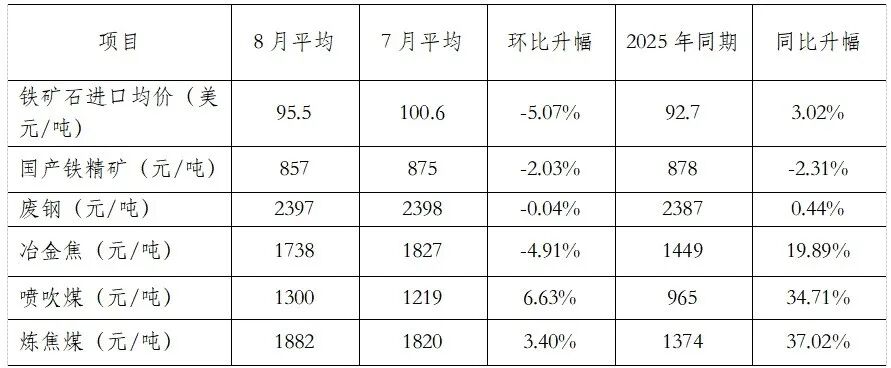
In terms of raw fuel, compared with July, the average price trend of each type of raw fuel diverged. The average monthly price of scrap has been stable. The average price of metallurgical coke, domestic iron concentrate, and imported iron ore has dropped markedly, and the average price of injected coal and coking coal have all risen sharply from month to month. Among them, the average monthly price increase of metallurgical coke, injection coal, and coking coal all increased by more than 19%. Overall, the supporting effect of raw fuel on steel prices has loosened marginally but is still strong. (see table below)
Table of changes in the prices of major raw fuels
Steel prices in the international market rose slightly month-on-month
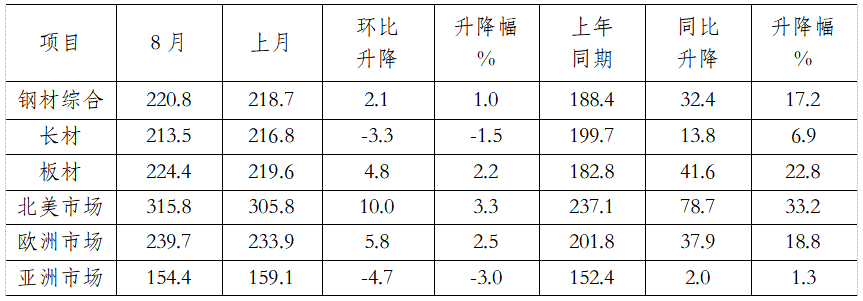
In August 2026, the CRU international steel price index was 220.8 points, up 2.1 points from month to month, up 1.0%; up 32.4 points year on year, or 17.2%. (See figure below).
From January to August 2026, the average value of CRU's international steel price index was 211.1 points, up 21.3 points year on year, or 11.2%. Among them, the average CRU long wood index was 211.7 points, up 15.8 points year on year, up 8.0%; CRU plate index average was 210.9 points, up 24.1 points year on year, up 12.9% year on year.
International Steel Price Index (CRU) Chart
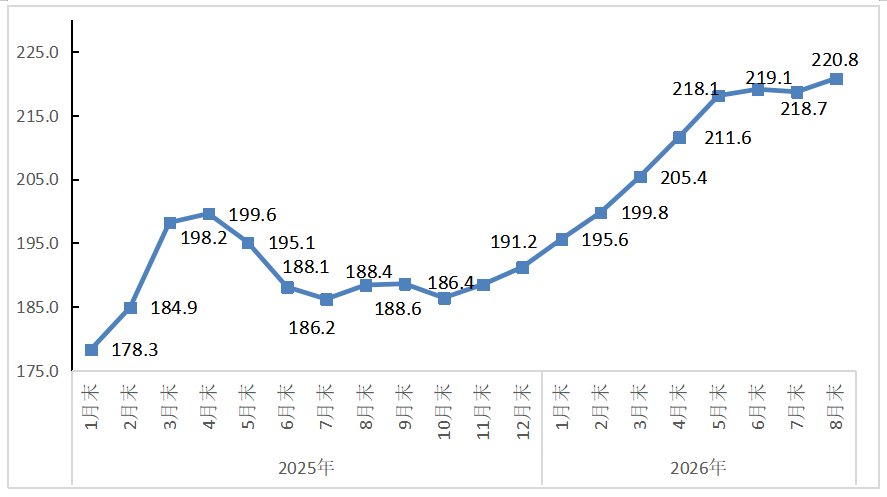
Table of changes in the International Steel Price Index (CRU) Unit: points
(1) The trend of long lumber and plate price indices diverged, with long lumber falling month-on-month and plate rising
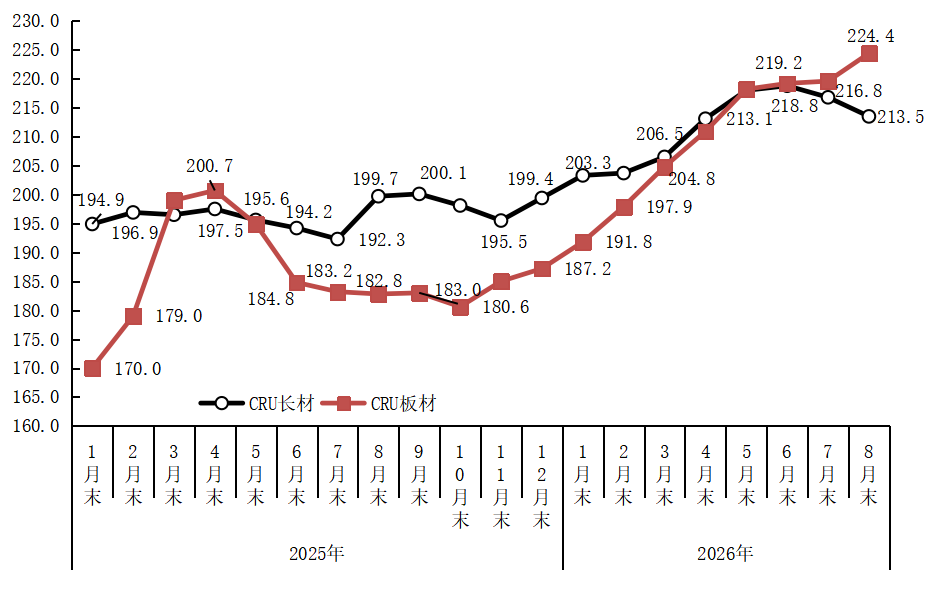
In August, the CRU long wood index was 213.5 points, down 3.3 points from month to month, or 1.5%; CRU plate index was 224.4 points, up 4.8 points from month to month, up 2.2%; compared with the same period last year, CRU long wood index rose 13.8 points, or 6.9%; CRU plate index rose 41.6 points, or 22.8%. (see figure below)
CRU long timber and plate price index chart
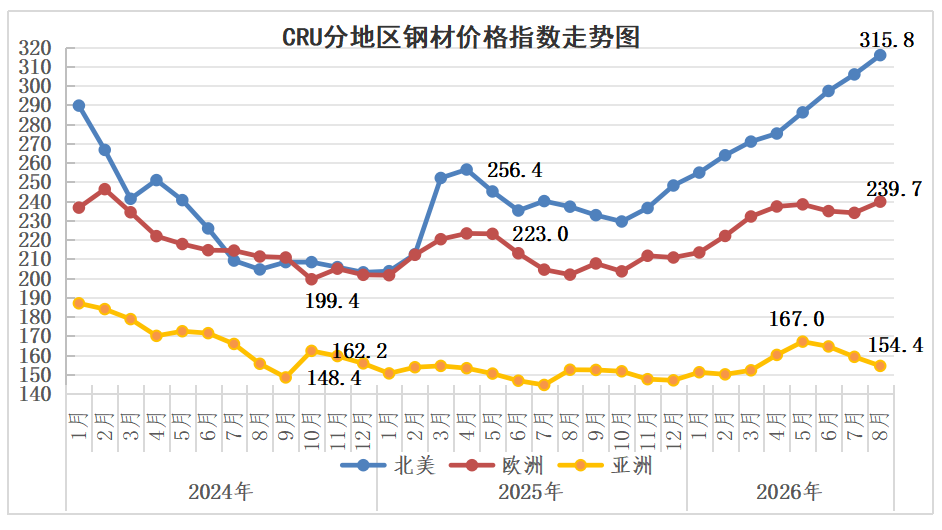
(2) The steel price index in North America and Europe rose, and the price index in the Asian region continued to decline
1. North American market
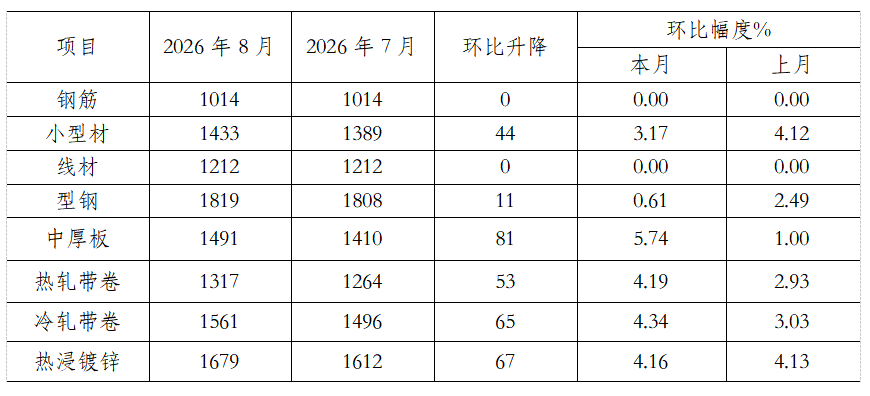
In August, CRU's North American steel price index was 315.8 points, up 10.0 points from month to month, an increase of 3.3%; the overall price performance of steel varieties in midwestern US steel mills was strong this month. With the exception of steel bars and wires, which remained flat, everything else grew. Among them, the price of medium and heavy plate increased significantly, to 81 US dollars/ton, an increase of 5.74%, and a smaller increase of 0.61% for section steel. Supported by limited supply and strong demand in various terminal fields, US medium and heavy plate prices continued to rise in August. Market supply continues to be tight, and the lead time between orders and delivery in the US is lengthening. In addition, various terminal industries such as construction, energy, heavy manufacturing, and mining are in strong demand, supporting steel mill production schedules. At the same time, the incremental demand brought about by engineering projects such as pipelines and bridges has further amplified seasonal demand for medium and heavy boards.
Table of changes in the ex-factory price of steel in midwestern steel mills in the United States Unit: USD/ton
2. European market
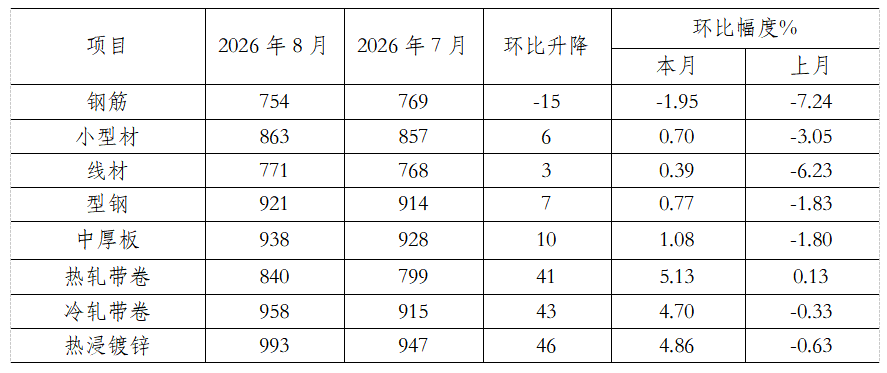
In August, CRU's European steel price index was 239.7 points, up 5.8 points month-on-month, or 2.5%; the final value of the Eurozone manufacturing PMI for August was 52.7, which continued to rise month-on-month and continued to expand. The Eurozone manufacturing boom continued to strengthen, favoring European steel demand. With the exception of a slight drop in steel bars, the prices of major steel varieties in the German market rose this month. Among them, hot-dip galvanizing, hot-rolled strip coils, and cold-rolled strip coils all increased by no less than 4.7%, while wire, small steel, and medium and thick plates increased steadily. The core driver of this round of European plate coil price increases is a change in the supply structure: import prices continue to rise and delivery has been tightened. In contrast, the cost performance advantage of local steel mills continues to stand out, supporting the steady rise in regional plate coil prices.
Changes in steel prices in the German market Unit: USD/ton
3. Asian market
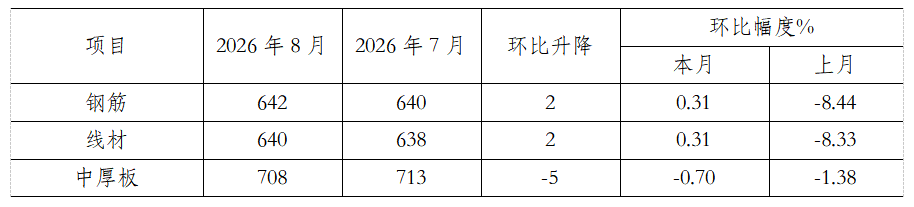
In August, CRU Asia's steel price index was 154.4 points, down 4.7 points from the previous month, or 3.0%; the prices of the three major steel varieties in the Indian market all ran smoothly this month, with medium and heavy plates falling steadily. Recently, monsoon rainfall has intensified in India, suppressing construction, and the will of purchasers has weakened, so trade inventories have risen accordingly. (see table below)
CRU India Market Steel Price Change Chart Unit: USD/ton
IV. Analysis of steel price trends in the later stages
Judging from the global economic situation, the global economy is showing resilience. IMF Managing Director Georgieva recently stated that the global economy has shown resilience beyond expectations in the energy shock caused by the Iran war, but there are still concerns under resilience. The global economy is in a tug-of-war between “negative supply shocks from the blockage of energy supply in the Middle East” and “positive demand shocks brought about by artificial intelligence.” Although AI investment provides growth hedging, it is not enough to fully absorb supply-side pressure. Furthermore, energy security, the El Niño phenomenon, and the potential impact of AI on financial stability were listed as three major risk points threatening global economic stability. The risks facing the global economic outlook are more balanced than in April, but due to increasing fiscal pressure and central banks may have to maintain tight monetary policies to control inflation, the risks are still biased downward. For the steel industry, this means that the overall external demand environment is under pressure.
From a domestic perspective, the steady domestic growth policy has recently been strengthened, and the incremental policy can be expected. On August 17, the 12th plenary session of the State Council emphasized “planning and introducing pragmatic and effective incremental policies in a timely manner,” “speeding up the implementation plan for the construction of the six networks,” and “speeding up the use of various policy funds, and forming a physical workload as soon as possible.” The policy signal clearly shifts from “stock implementation” to “incremental increase”, providing medium-term support for steel demand. On September 3, a major project construction promotion conference was held in the “Outline” of the “15th Five-Year Plan”. The conference called for speeding up the implementation of projects under construction and promoting the early commencement of construction of a number of new projects, which means that infrastructure projects will accelerate from “planning” to the “construction” stage, and demand for construction steel is expected to be substantially supported. If policy funding accelerates the formation of physical workload from the end of the third quarter to the fourth quarter, steel demand is expected to improve.
From a supply-side perspective, carbon constraints and capacity policies have increased in synergy, and supply-side contraction expectations for the steel industry have been significantly strengthened. At the beginning of September, the Ministry of Ecology and Environment officially issued the “National Carbon Emissions Trading Market 2025 and 2026 Power Generation and 2026 Steel, Cement and Aluminum Smelting Industry Quota and Distribution Plan”, which makes uniform and systematic arrangements for the allocation of quotas for the four major industrial industries of power generation, steel, cement and aluminum smelting. The plan clearly states that quota allocations will “gradually link and collaborate with production capacity replacement and production regulation policies” and “strengthen carbon emission control requirements for illegally backward production capacity and self-owned power plants,” and that hard restrictions on capacity replacement and soft restrictions on carbon quotas will form a policy synergy: backward production capacity faces both a replacement threshold and pressure from rising carbon emission costs. The exit channel has been further narrowed, and supply-side contraction expectations have been significantly strengthened.
In terms of production, in early September 2026, according to key statistics, steel companies produced a total of 19.24 million tons of crude steel, with an average daily output of 1.924 million tons. Nissan increased 2.0% month-on-month, and crude steel production rebounded slightly in early September.
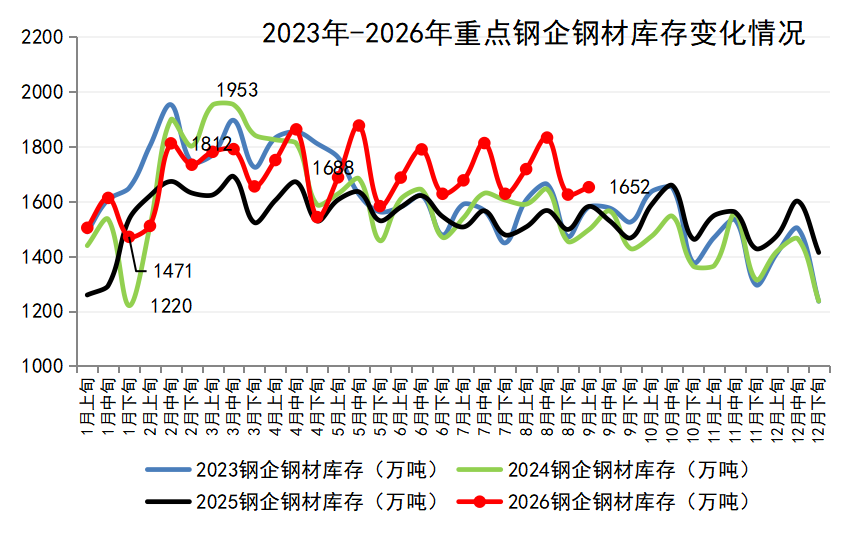
In terms of inventory, in early September 2026, steel inventories of steel companies were 16.52 million tons, an increase of 270,000 tons over the previous quarter; an increase of 2.38 million tons from the beginning of the year, an increase of 16.8%; a decrease of 660,000 tons from the same period last month, a decrease of 3.8%; and an increase of 700,000 tons, an increase of 4.4% over the same period last year. Currently, steel inventories are still at their highest level in the same period in the past four years.
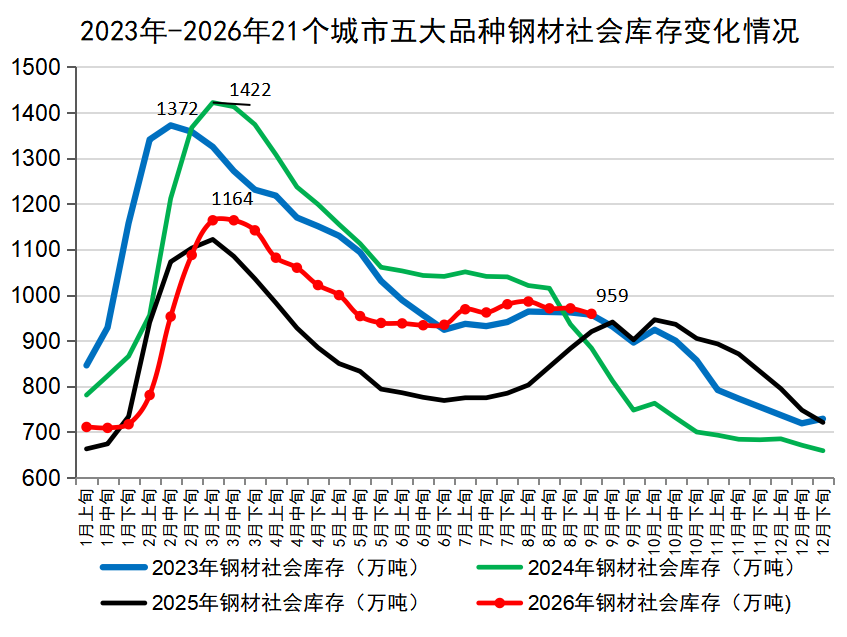
Judging from social inventories, the pressure on social inventories of steel decreased in early September. At the beginning of September, social stocks of the five major types of steel in 21 cities were 9.59 million tons, a decrease of 120,000 tons from the previous month, a decrease of 1.2%, and inventories fell slightly; an increase of 2.38 million tons over the beginning of the year, an increase of 33.0%; an increase of 390,000 tons over the same period last year, an increase of 4.2%. Since mid-August, overall social inventories have been characterized by slow removal, but they are still at a high level compared to last year.
Key issues to focus on later:
First, there is a risk that demand during the peak season falls short of expectations. On the one hand, the decline in real estate development investment is still expanding, and the new construction area continues to grow negatively. Guided by the policy of “controlling growth and removing inventory”, it is expected that new construction starts and real estate development investment will continue to operate at a low level. On the other hand, although policies such as “six networks” and “urban renewal” are being implemented intensively, there is a time lag between policy deployment and the formation of physical workload. Infrastructure investment continues to grow negatively, and there is uncertainty about the pace at which infrastructure drives demand for steel. In addition, the operating rate and average monthly working hours of major construction machinery products declined year-on-year in August, and demand for steel for construction lacked substantial support. If terminal demand is not effectively released in September-October, the current “cost increase” market lacks a foundation of demand, and steel prices face the risk of a pullback.
The second is to strengthen industry self-discipline and maintain market order. Currently, the steel industry is facing a double squeeze of “high costs and weak demand”. Since the “5.22” Qinyuan mine disaster, coking coal and coke have continued to rise, putting a lot of cost pressure on steel companies. Demand during the “Golden Nine” peak season has been slow to be met, the rise in steel prices is weak, and the scissor gap between costs and steel prices continues to widen. Looking at the current situation, quite a few steel companies have already fallen into losses, but their efforts to cut production are clearly insufficient. The negative feedback risk of “more production, more loss” is accumulating. In this context, enterprises should view market fluctuations more rationally, avoid disorderly competition at low prices, and jointly maintain a fair and orderly market environment. Recently, the National Development and Reform Commission and the General Administration of Market Regulation jointly issued a cost accounting notice, focusing on important industrial product production areas with prominent low price and disorderly competition. The aim is to clarify cost accounting rules and provide operational standards for managing “below-cost dumping”. Enterprises should actively target the average cost of the industry, standardize pricing behavior, and promote the smooth operation of the industry.