
ManpowerGroup (MAN) Stock May Still Be A Bargain As Hiring Outlook Improves
ManpowerGroup has delivered a striking year to date share price gain of 91.8%, which naturally puts a spotlight on whether that move is backed up by the earnings power of the business. With the stock last closing at US$57.67, the real question for you is how much of the recent enthusiasm is already embedded in the profit profile investors are paying for today.
- A 91.8% rise year to date puts recent share buyers in a very different position to where they started in January, so any earnings based valuation work now carries much more weight for portfolio decisions.
- Fresh survey data pointing to a slightly stronger global hiring outlook and a focus on new skills may support expectations for ManpowerGroup's future fee income and profitability if employers follow through on those staffing plans.
- There is a second opinion on ManpowerGroup worth weighing. See what analysts think ManpowerGroup's shares could be worth.
The issue now is whether the stock's current price is justified by the level and quality of ManpowerGroup's earnings.
If you want to cross check ManpowerGroup's earnings story against a wider pool of opportunities, you can use a focused stock screen built around 29 high quality undervalued stocks.
Is ManpowerGroup a Bargain on Earnings?
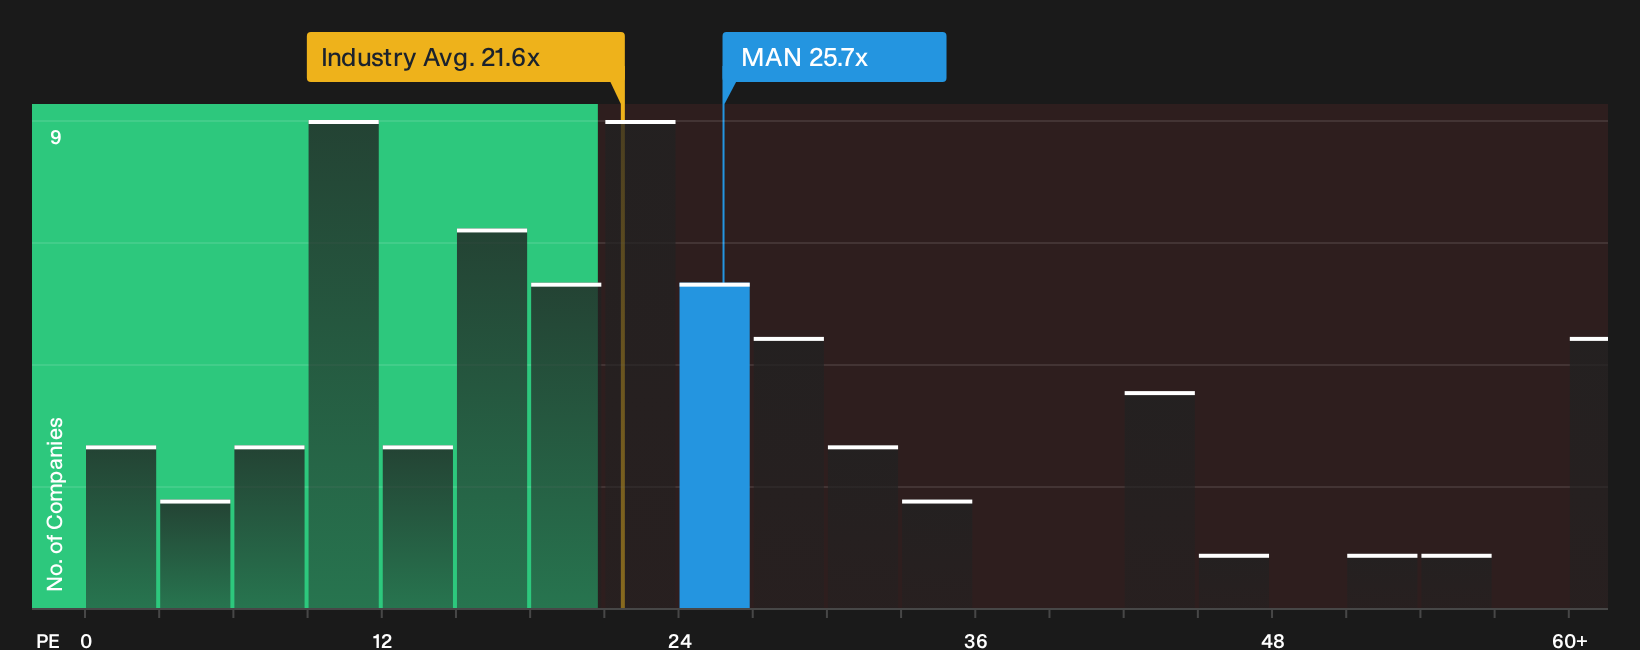
P/E works well for ManpowerGroup because earnings remain a key yardstick for a mature, service focused recruiter. On this basis, the stock trades on a P/E of 25.7x, which is above both the Professional Services industry average of 21.6x and the peer group on 19.0x. That places the current valuation at a premium to many similar businesses even after the strong share price move this year.
Because the latest Employment Outlook Survey points to a slightly stronger hiring backdrop and demand for new skills, the market seems willing to pay this higher multiple. The in house model that adjusts for ManpowerGroup's growth profile, margins, size and risk points to a higher P/E than today. This suggests the shares screen as undervalued on this framework despite trading richer than sector and peer benchmarks. Explore the numbers behind ManpowerGroup's P/E valuation.
The ManpowerGroup Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the ManpowerGroup valuation puzzle leaves off. They spell out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than the current price. Each Narrative frames its view of fair value as a thesis about the business that you can track over time, rather than a single frozen snapshot. Narratives for ManpowerGroup sit on Simply Wall St's Community page.
ManpowerGroup brings out sharply different readings from the community, with one side arguing the recent move still leaves upside and the other flagging a rich setup.
Bull case: 19% undervalued
"Ongoing strategic investments in proprietary digital platforms, including global rollouts of PowerSuite and AI-driven analytics, are set to boost recruiter productivity…"
Discover why this Narrative puts ManpowerGroup at 19% undervalued.
Bear case: 28% overvalued
"MAN is not cheap because the business is broken, it is cheap because the global staffing cycle has been in an eleven-quarter contraction…"
Explore why this Narrative puts ManpowerGroup at 28% overvalued.
One more angle on ManpowerGroup that deserves a closer look
All the focus on ManpowerGroup's earnings and valuation only tells part of the story. The internal risk checks have flagged specific concerns that could matter to your thesis. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com