
Learn Why The Bull Case For TD Stock Could Change Following U.S. Branch Expansion
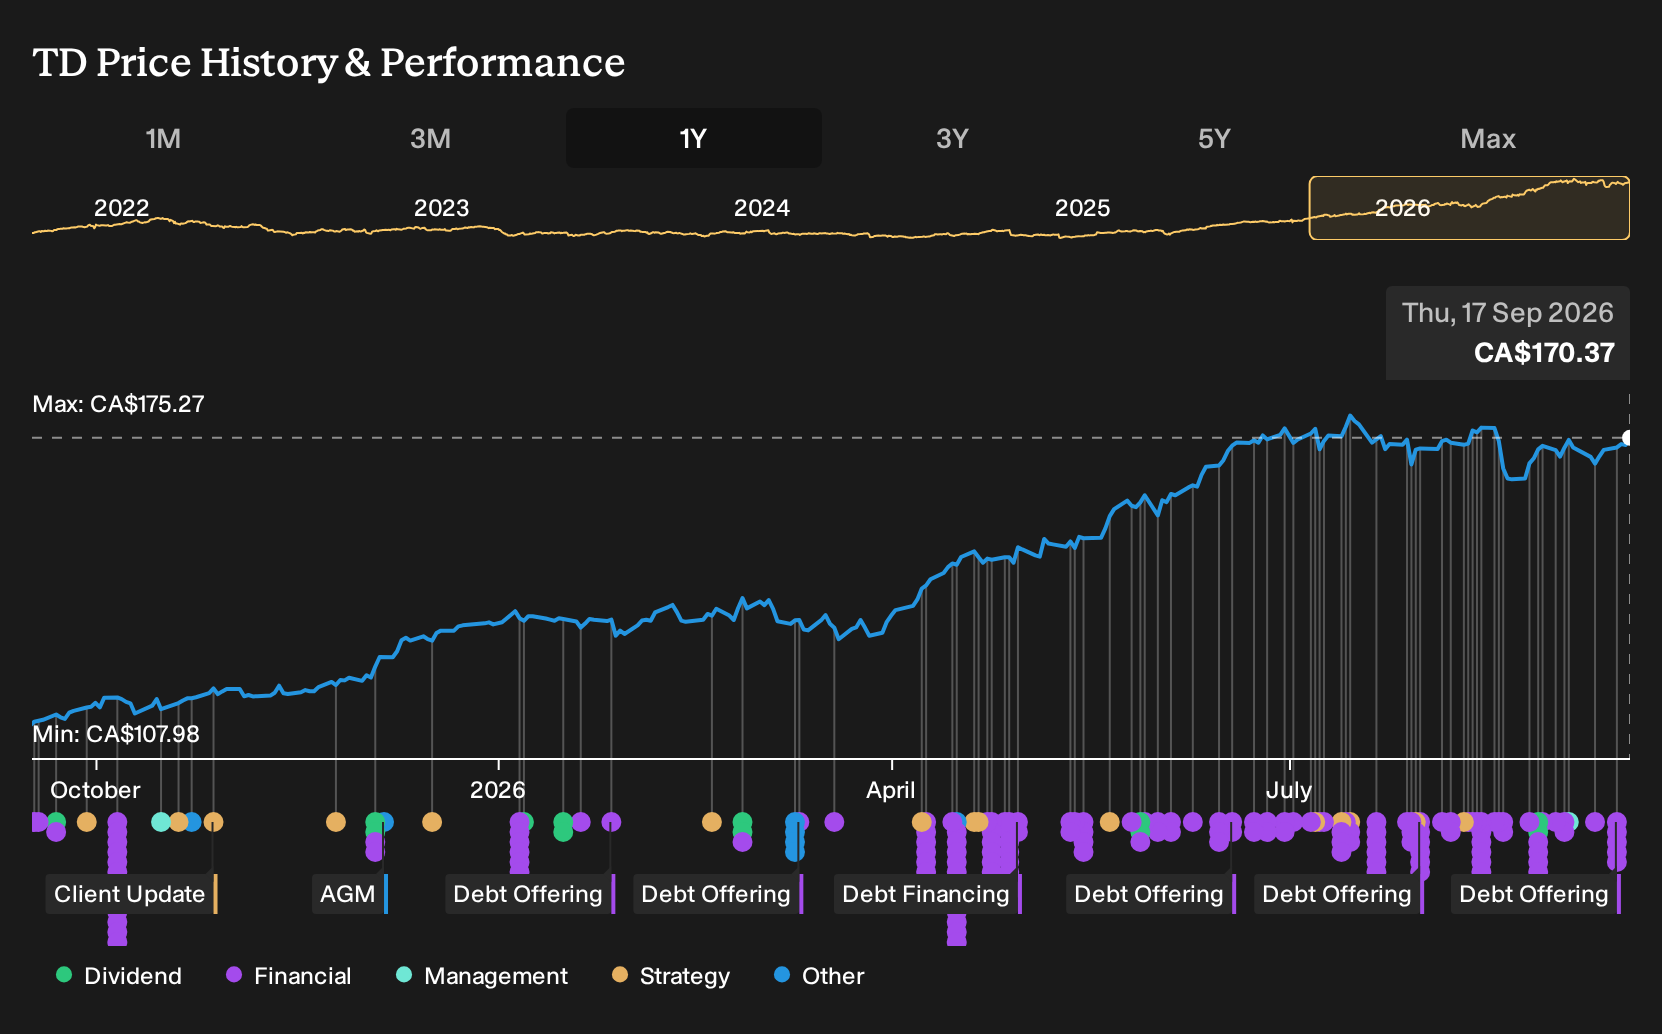
- Toronto-Dominion Bank recently issued multiple fixed-rate senior unsecured notes in US dollars and euros, with coupon rates ranging from 4.398% to 5.75% and maturities between 2028 and 2038. Several of the securities are callable and structured as Eurobonds or global MTNs.
- The cluster of new fixed-income offerings and recently completed tranches highlights TD’s ongoing use of wholesale funding to support its broader U.S. expansion and digital investment plans, while also managing term structure and currency mix on its balance sheet.
- We will look at how TD’s resumed U.S. branch expansion and cost targets may reshape the bank’s broader investment narrative for readers.
Scan how Toronto-Dominion Bank’s funding moves compare with peers by reviewing a curated list of solid balance sheet and fundamentals (7 results) highlighting other institutions that are also leaning on bond markets and strong capital positions.
Toronto-Dominion Bank Investment Narrative Recap
To own Toronto-Dominion Bank, you need to believe the mix of Canadian retail, U.S. banking, wealth, insurance and wholesale operations can keep generating steady earnings even as fintech pressure, compliance costs and real estate exposure remain front and center. In the near term, the key swing factor is management’s ability to hold net interest income and fee trends while absorbing higher regulatory and technology spending.
The recent run of fixed income offerings appears more like balance sheet housekeeping than a major catalyst. It extends TD’s term funding and supports its U.S. branch build-out and digital projects, but it does not materially change the main risk today, which is sustained expense pressure from compliance and remediation work.
The launch of TD Diversified Bond Pool and the TD Q International Dividend ETF is the announcement that aligns most clearly with this new wholesale funding. It keeps TD Asset Management adding products in fixed income and global dividends at the same time the bank is raising term debt in multiple currencies.
For you as a shareholder, these products are worth watching because they test TD’s ability to grow fee-based wealth revenue while lending growth faces regulatory constraints and capital remains tied up in compliance. Strong uptake would support the multi-segment earnings story and help offset any drag from higher structural costs in the core banking franchises.
Toronto-Dominion Bank is currently modeled on analyst assumptions that its revenues reach about CA$71.1 billion and its earnings come in near CA$16.2 billion by 2029, which implies annual top line growth of 5.3% and an earnings increase of roughly CA$0.6 billion from about CA$15.6 billion today.
Uncover how Toronto-Dominion Bank's fair value indicates a 5% potential upside to its current price before the market closes that valuation gap.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$179 and US$211 per share, which shows a fairly tight but still meaningful spread. Those estimates do not yet reflect Toronto-Dominion Bank’s new bond issuance, rising compliance spend, or U.S. branch plans; you can weigh multiple viewpoints before deciding how this setup fits your own thesis.
Explore 2 other Toronto-Dominion Bank fair value estimates, including one that suggests up to 24% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Toronto-Dominion Bank research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Toronto-Dominion Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toronto-Dominion Bank's overall financial health at a glance.
Looking For More Ideas Beyond Toronto-Dominion Bank?
If you want to cross-check Toronto-Dominion Bank against a wider opportunity set, the Simply Wall St Screener can surface other businesses that fit different risk and income profiles in just a few minutes.
- For investors who want potential mispricing with solid fundamentals, scan a curated pool of 3 high quality undervalued stocks that may warrant a closer look beside TD.
- If resilience and balance sheet strength matter most to you, compare Toronto-Dominion Bank with a list of solid balance sheet and fundamentals (7 results) that could help frame where TD sits on the quality spectrum.
- Those hunting for ideas outside the usual watchlists can use a 9 high quality undiscovered gems that many investors may not yet be focusing on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com