
Analyst Backing Could Reshape The Case For Ameriprise Stock (AMP)
- Recent analyst reports on Ameriprise Financial highlight robust earnings per share trends, strong returns on equity, and tangible book value per share growth, alongside valuation ratios that compare favorably to peers.
- The combination of high adviser productivity, technology investment, and analyst views of attractive P/E and P/CF levels presents Ameriprise Financial as a case study in how business efficiency can align with perceived value.
- We will now examine how Ameriprise Financial's valuation metrics might influence the existing investment narrative around adviser productivity and growth.
Scan value-focused peers to Ameriprise Financial by reviewing our curated list of 29 high quality undervalued stocks that share strong fundamentals and potentially attractive valuation markers.
Ameriprise Financial Investment Narrative Recap
To own Ameriprise Financial, you need to be comfortable with a wealth and asset manager whose fortunes are closely linked to markets, adviser productivity, and asset flows. The short term story still revolves around keeping advisers productive on platforms like Signature Wealth UMA and PracticeTech, and holding client assets through volatility. The recent focus on valuation metrics does not materially change that operational backdrop.
The biggest near term swing factor is how well Ameriprise Financial manages asset management outflows and pricing pressure while still funding technology and banking product build out. The key risk remains prolonged market volatility combined with rate cuts and weaker cash sweep yields, which could squeeze net interest income and pressure already competitive adviser recruiting costs.
Among recent developments, the build out of Ameriprise Financial banking offerings, including CDs and planned HELOCs and checking products, ties directly into the catalyst story. These products give advisers more tools in a single ecosystem. That can support deeper client relationships and potentially steadier fee and interest income when markets are choppy.
This expansion also comes with execution questions. Management needs to scale lending and deposits prudently while the firm still relies on higher risk wholesale funding rather than customer deposits. How that funding mix evolves, and how quickly new banking revenue offsets any pressure from asset outflows or lower sweep yields, sits at the center of the current risk reward balance.
Ameriprise Financial's current consensus story points to revenue of US$22.9b and earnings of US$4.8b by 2029, based on analysts' assumption of 4.9% yearly revenue growth and an earnings increase of about US$0.9b from US$3.9b today.
Discover why Ameriprise Financial's fair value points to a 5% potential upside to its current price, which could narrow quickly.
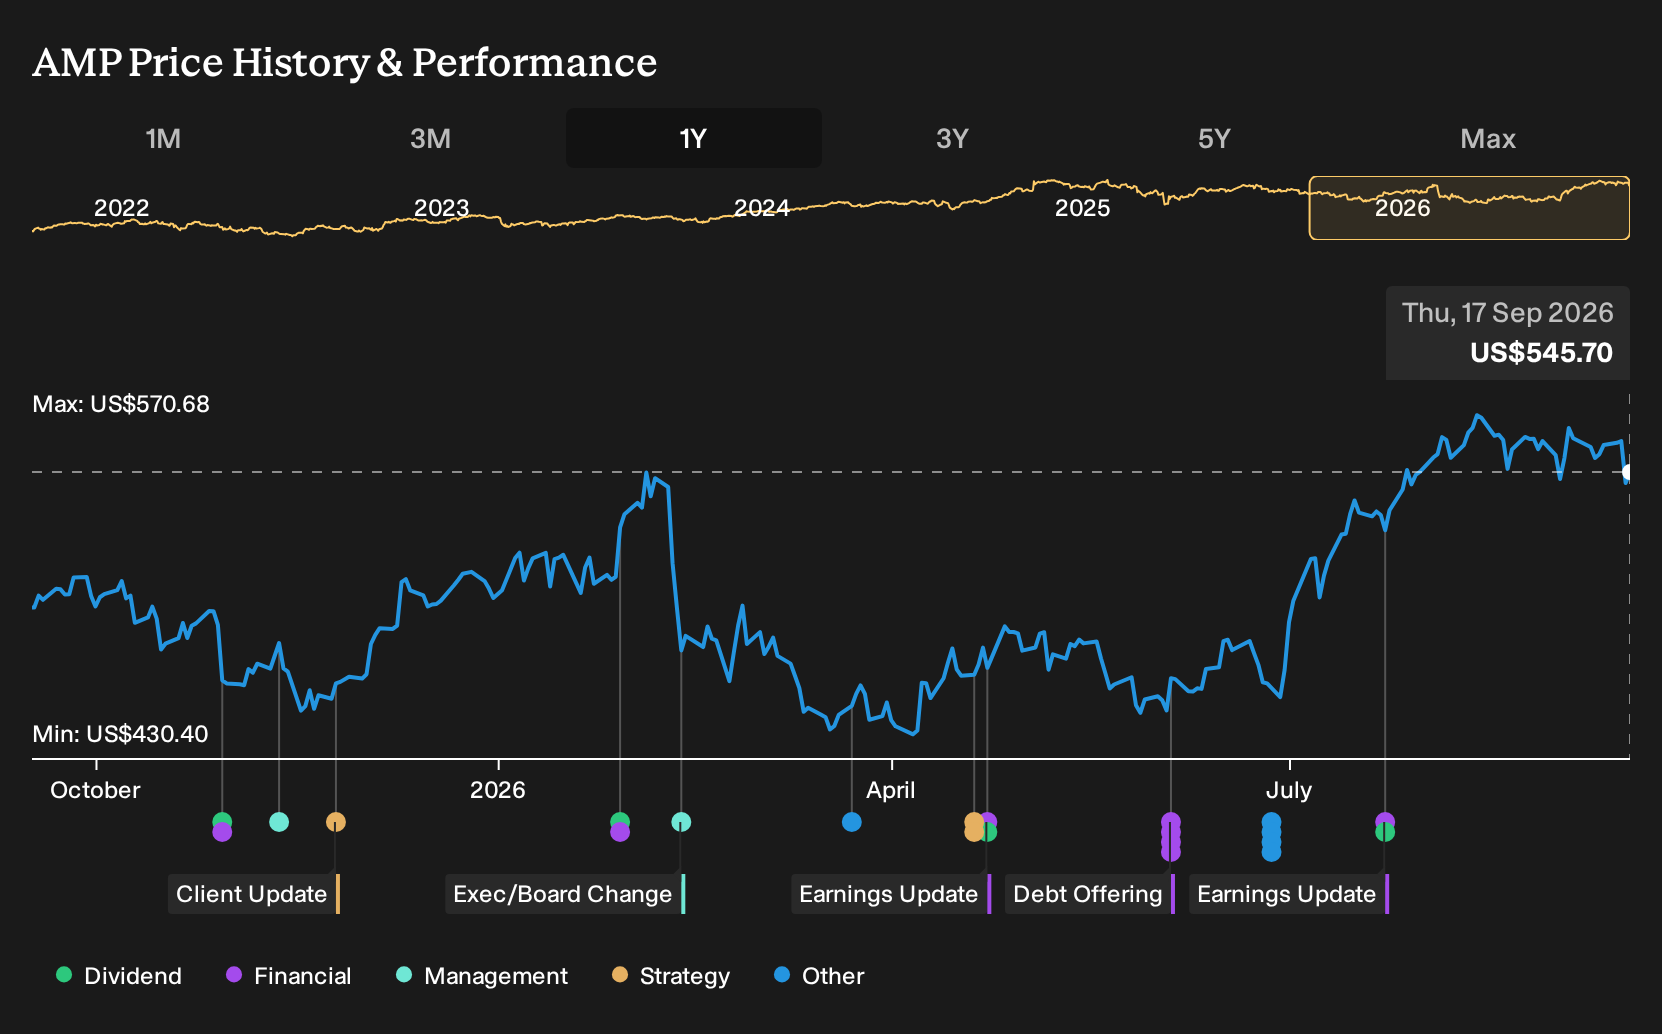
Exploring Other Perspectives
Some of the most optimistic analysts on Ameriprise Financial lean heavily on the banking build out as a catalyst, arguing that broader CDs, HELOCs, and checking could reshape earnings quality. Before the news, this group was penciling in about US$21.5b of revenue and US$4.6b of earnings by 2029. Be open to how those views might shift once the latest developments are fully reflected.
Explore 2 other Ameriprise Financial fair value estimates, including one that suggests as much as 103% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ameriprise Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ameriprise Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ameriprise Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ameriprise Financial?
If the Ameriprise Financial story has sharpened your thinking on valuation and quality, use that same lens to scan a wider universe of opportunities with the Simply Wall St Screener.
- For income focused portfolios that still care about balance sheet strength, check out 6 dividend fortresses that combine sizeable yields with robust fundamentals.
- If capital preservation ranks high on your list, review 30 resilient stocks with low risk scores that score well on resilience and financial risk metrics.
- For investors hunting for quality off the beaten path, sift through 16 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com