
How Is Waters Corporation's Stock Performance Compared to Other Health Care Stocks?
Milford, Massachusetts-based Waters Corporation (WAT) provides analytical workflow solutions. With a market cap of $41.1 billion, the company designs, manufactures, sells, and services high and ultra-performance liquid chromatography, as well as mass spectrometry (MS) technology systems and support products, including chromatography columns, other consumable products, and post-warranty service plans.
Companies worth $10 billion or more are generally described as “large-cap stocks,” and Waters perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the diagnostics & research industry. The leading player in liquid chromatography and mass spectrometry's focus on innovation through substantial R&D investment drives new product development. With a diverse customer base spanning biopharmaceutical, industrial, and academic/government sectors, WAT maintains a stable revenue stream and capitalizes on growth opportunities across multiple industries.
Despite its notable strength, WAT shares touched their 52-week high of $431.78 in the last trading session. Over the past three months, WAT stock has gained 20.4%, outperforming the State Street Health Care Select Sector SPDR ETF’s (XLV) 12% gains during the same time frame.
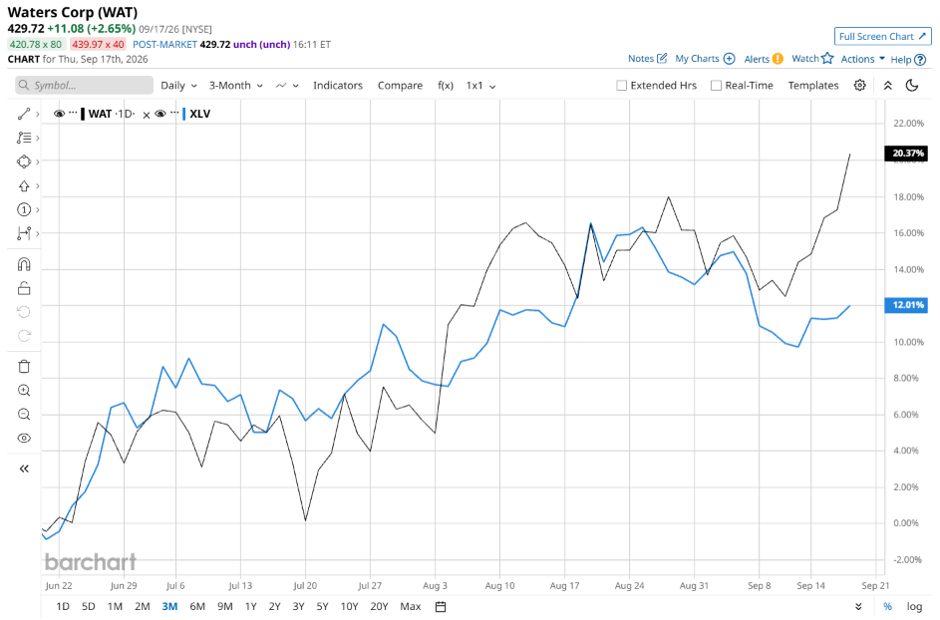
Shares of WAT rose 13.1% on a YTD basis and climbed 41.5% over the past 52 weeks, outperforming XLV’s YTD gains of 9.1% and 23% returns over the last year.
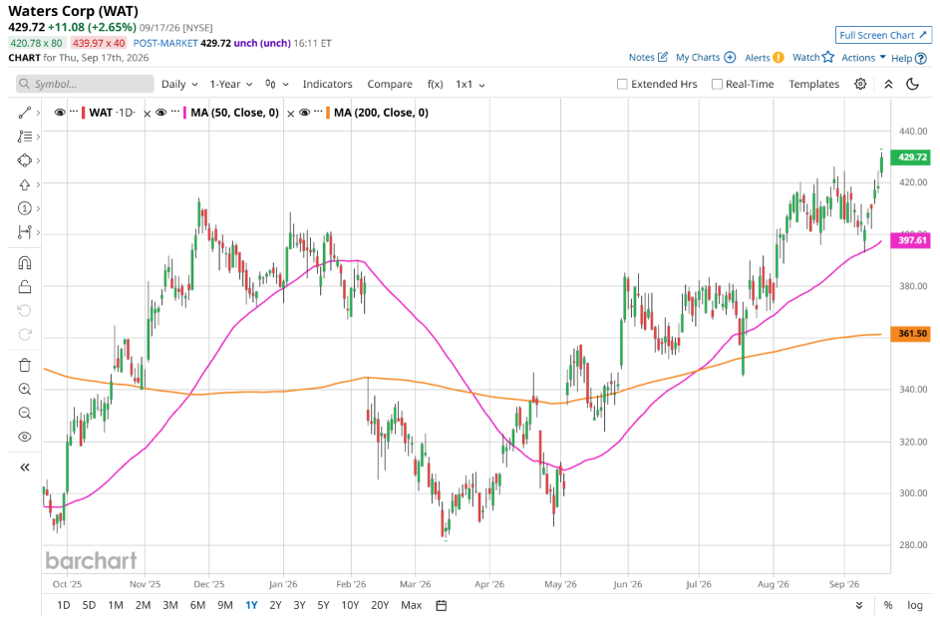
To confirm the bullish trend, WAT has been trading above its 50-day moving average since mid-April, experiencing some fluctuations. The stock has been trading above its 200-day moving average since early May, with slight fluctuations.
WAT outperformed on strong demand for lab equipment, chemicals and routine testing supplies with double-digit growth, plus momentum from its Biosciences & Diagnostics acquisitions. CEO Udit Batra cited broad-based pharma, academic, and government demand, with GLP-1 testing up over 40%, driven by new launches like Cyclic IMS P20 and Xevo MRT P10 and a successful 180-day revitalization of acquired assets. Pricing actions and $75 million cost savings are supporting margins, while replacement cycles and U.S. pharma reshoring provide forward tailwinds.
WAT’s rival, Agilent Technologies, Inc. (A) lagged behind the stock, with 23.4% gains over the past 52 weeks, but outpaced the stock with a 14.9% uptick on a YTD basis.
Wall Street analysts are reasonably bullish on WAT’s prospects. The stock has a consensus “Moderate Buy” rating from the 24 analysts covering it, and the mean price target of $444.83 suggests a potential 3.5% upside from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.