
Powell Industries (POWL) Tests Its Growth Narrative On A Pullback And Valuation
Powell Industries (POWL) is back in focus after a strong five year run in its financials, with revenue compounding over 20% annually and earnings per share rising at a very large compounded rate.
The recent pullback in Powell Industries’ share price, with a 30 day share price return down 13.17% and a 90 day share price return down 40.53%, sits against a much stronger backdrop. The year to date share price return is 50.42% and the 5 year total shareholder return is above 20x, which may suggest that investors are reassessing short term expectations rather than abandoning the longer term earnings story.
Scan for other industrials showing similar long term momentum to Powell Industries by exploring our curated list of list of solid balance sheet and fundamentals (23 results).
So is Powell Industries’ sharp pullback simply sentiment cooling after a huge multi year run, or does it hint that the current share price has moved out of line with the business? It is time to test the valuation.
Most Popular Narrative: 47% Undervalued
The most popular narrative around Powell Industries pegs fair value at $333 per share, well above the recent $176.75 close. This frames the recent pullback as a possible reset in expectations rather than a collapse in the underlying thesis.
The bullish analysts expect earnings to reach $372.0 million (and earnings per share of $10.15) by about August 2029, up from $190.9 million today. However, there is some disagreement amongst the analysts with the more bearish ones expecting earnings as low as $288.9 million.
See why 5 investors see Powell Industries as 47% undervalued.
Result: Fair Value of $333 (UNDERVALUED)
Still, Powell Industries’ bullish script depends on that US$1.4b backlog converting smoothly and on new Houston capacity filling. As a result, delays in LNG or data center projects could quickly test this optimism.
Find out about the key risks to this Powell Industries narrative.
Another View On Powell Industries Using Market Multiples
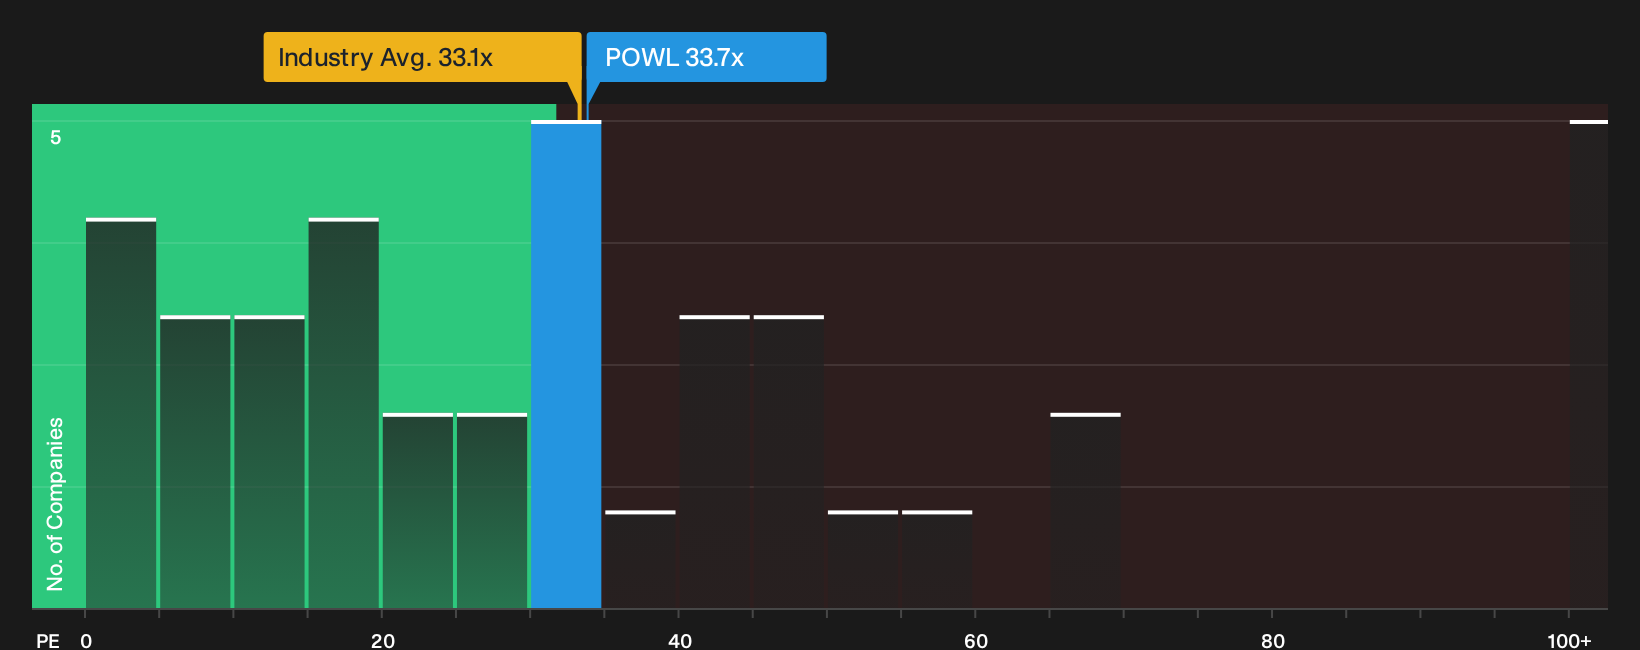
That bullish $333 fair value for Powell Industries runs into a reality check when looking at simple P/E maths. The stock trades at 33.7x earnings, slightly richer than the US Electrical sector on 33.1x and above its own fair ratio of 30.8x. This suggests some valuation risk if enthusiasm cools.
For investors who prefer to anchor decisions on market based ratios rather than narrative driven targets, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of Powell Industries so far and whether the market reaction fits the story or not. Move quickly, review the data yourself, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more Powell Industries style ideas?
If Powell Industries has sharpened your focus on quality, do not stop here. Use the Simply Wall St screener to surface fresh, data driven opportunities before the crowd.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (23 results) to help keep financial risk in check.
- Hunt for quality trading at appealing valuations by reviewing the 29 high quality undervalued stocks which combines robust metrics with more modest pricing.
- Anchor your watchlist with potential income ideas by checking out the 6 dividend fortresses which pairs higher yields with underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com